What Is a Transfer Pricing Disclosure Form?
What Is a Transfer Pricing Disclosure Form?
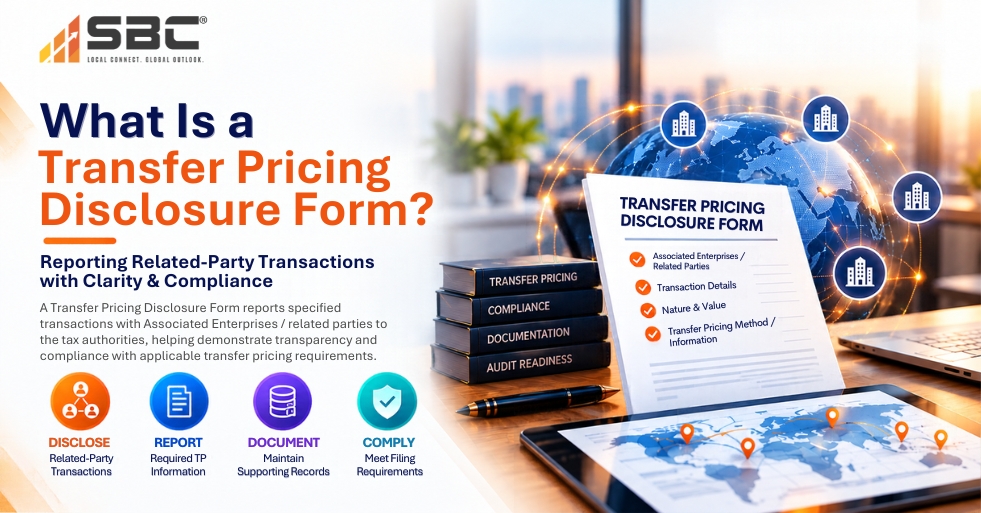
Quick answer: A transfer pricing disclosure form is a tax-return schedule or prescribed filing that reports a taxpayer’s related-party or controlled transactions, including transaction categories, values, counter parties and, depending on the jurisdiction, transfer pricing information.
Tax agencies look for risks and pick out specific taxpayers or deals needing closer review, all based on solid data. The real deal here is that this info has to come straight from the original transfer pricing analysis. Preparing the disclosure by piecing it together from the trial balance at the last minute during filing week just doesn’t work effectively. A clear, backed-up disclosure helps officials spot and judge transfer pricing issues more easily.
1. Transfer Pricing Disclosure Requirements at a Glance
| Jurisdiction | Disclosure / Filing | Key Trigger |
|---|---|---|
| UAE | Related Party Transaction Schedule within Corporate Tax Return; Connected Person Schedule where applicable | Related Party transactions > AED 40m; categories > AED 4m after threshold. Connected Person schedule: > AED 500k per person, subject to rules. |
| India | Form 3CEB – accountant’s report | International transactions; specified domestic transactions > ₹20 crore. |
| Saudi Arabia | Transfer Pricing Disclosure Form | Controlled transactions; disclosure applies irrespective of transaction value. |
| Qatar | Transfer Pricing Declaration through Dhareeba | Applicable taxpayers meeting Qatar TP declaration conditions; transaction-level requirements also apply. |
| Singapore | Related Party Transaction reporting with Form C | Related-party transactions disclosed in financial statements exceed S$15m. |
2. What Information Does a Transfer Pricing Disclosure Form Contain?
The exact information varies by jurisdiction, but a transfer pricing disclosure commonly captures:
- Related-party or associated-enterprise details
- Nature and category of transactions
- Transaction values
- Income and expenditure
- Loans and financing transactions
- Royalties and intellectual property transactions
- Management or support services
- Goods purchased or sold
- Transfer pricing methods, where required
- Arm’s length values or adjustments, where applicable
- Details of connected persons
- Other information required by the relevant tax authority
The disclosure therefore creates a structured picture of a multinational group’s cross-border or related-party dealings.
3. Why Is a Transfer Pricing Disclosure Form Important?
3.1 A disclosed method needs to be supportable. Where the disclosure requires a transfer pricing method or related TP position, that position should be consistent with the taxpayer’s transfer pricing analysis and supporting documentation.
3.2 Disclosed values should reconcile. Tax authorities increasingly use data from tax returns, financial statements and related-party disclosures to identify inconsistencies. A taxpayer should be able to reconcile accounting records → related-party transaction data → TP analysis → disclosure → tax return.
3.3 A disclosed TP adjustment should not be ignored. Where the disclosed information indicates that a transaction is not at arm’s length, the taxpayer should understand the tax and transfer pricing implications before filing.
4. How Do Tax Authorities Use Transfer Pricing Disclosure Data?
Transfer pricing disclosure data can be used as an initial risk-screening mechanism. Tax authorities may compare disclosed information with financial statements, corporate tax returns, previous-year filings, related-party disclosures, industry data, profit margins, transaction volumes, cross-border payment information and transfer pricing documentation.
Some potential risk indicators would include: continuing losses despite significant related party payments, significant outbound management or service charges, significant royalty payments, financing arrangements with related parties, transactions with low tax jurisdictions, significant year on year changes, unusual transfer pricing methods and margins not consistent with the functional profile of the taxpayer.5. UAE Transfer Pricing Disclosure Form
In the United Arab Emirates, certain schedules are used to include transfer pricing information in the corporate tax return.
The Related Party Transaction Schedule is applicable when the total value of transactions with all Related Parties surpasses AED 40 million, according to the Federal Tax Authority.
Disclosure is required where transaction categories exceed AED 4 million once the AED 40 million threshold is reached. If the total payments or benefits exceed AED 500,000 per connected person, a separate connected person schedule will be applicable in accordance with the relevant regulations. UAE taxpayers are required to reconcile related-party master data, general ledger transactions, financial statements, corporate tax returns, and TP analysis.
6. India: Form 3CEB and Transfer Pricing Disclosure
Form 3CEB is the accountant’s report on specified domestic transactions and international transactions in India. Transfer pricing provisions apply irrespective of the amount of international transactions. The aggregate value of specified domestic transactions shall be more than ₹ 20 crore for the relevant financial year.
Form 3CEB should align with transfer pricing documentation, financial statements, related-party ledgers, tax return disclosures, benchmarking analysis and the arm’s length determination.
7. Saudi Arabia: Transfer Pricing Disclosure Form
Taxpayers with controlled transactions in the Kingdom of Saudi Arabia are obligated to file a Transfer Pricing Disclosure Form. ZATCA said the disclosure form is submitted with the income tax return within 120 days from the end of the fiscal year, and that controlled transactions must be disclosed irrespective of their value.
Key principle: A low transaction value does not automatically mean that a taxpayer has no transfer pricing disclosure obligation.
8. Qatar: Transfer Pricing Declaration
The Transfer Pricing Declaration and documentation are designed to support the compliance with transfer pricing rules and the attainment of consistent TP positions. According to Qatar’s official service information, the declaration shall be applicable if the relevant group revenue exceeds QAR 10 million.
9. Singapore: Related Party Transaction Reporting
In Singapore, companies must file the Related Party Transaction Form when the value of related-party transactions disclosed in the financial statements exceeds S$ 15 million. This form is a component of Form C and is used by IRAS to assess transfer pricing risks. RPT value may include amounts received or receivable, amounts paid or payable, year-end loan balances and non-trade balances, subject to applicable exclusions.
10. Transfer Pricing Disclosure vs Transfer Pricing Documentation
A transfer pricing disclosure form and transfer pricing documentation are not the same thing.
Disclosure forms go with your tax return, list key transactions, help spot risks, and stay short.
Taxpayers usually keep the docs themselves; they show fair market dealings, back up claims with specifics, and get made when the rules say so. Disclosure and documentation are different duties, but they’ve got to match up on the real economic facts.
11. What Happens if the Disclosure and Local File Do Not Match?
If a disclosure doesn’t match the transfer pricing docs, auditors are more likely to flag it. You’ll see things like varying transaction amounts, categories, involved parties, pricing approaches, job roles, or profit numbers. The real issue is that the inconsistency might make people wonder how the taxpayer settled on its transfer pricing stance.
12. How Should a Company Prepare a TP Disclosure?
• First, find everyone involved.
• Step 2: Pull transaction records from accounting systems and related ledgers.
• Step 3: Sort transactions into types like goods, services, royalties, interest, financing, intangibles, management fees, and reimbursements.
• Step 4: Match up your values with the general ledger, trial balance, financials, tax return, and last year’s disclosures.
• Step 5: Check against the TP docs.
• Step 6: Find out what disclosure level applies.
• Step 7: Check for possible TP changes.
• Step 8: Finish and double-check the final disclosure before you send it.
13. Common Transfer Pricing Disclosure Mistakes
- Preparing the disclosure from memory
- Reusing last year’s transaction categories without review
- Ignoring smaller transactions without checking all applicable obligations
- Reporting a different method from the TP documentation
- Failing to reconcile financial statements
- Treating disclosure as a substitute for documentation
14. Why Transfer Pricing Disclosure Is Becoming More Important
Transfer pricing compliance is moving toward a data-driven environment. Tax administrations can increasingly compare Tax Returns → Financial Statements → Related-Party Disclosures → TP Documentation → Cross-Border Data → Prior-Year Filings.
For multinational groups, the objective should therefore not simply be “Did we file the disclosure?” The better question is: “Can every number and TP position in the disclosure be traced back to a defensible analysis?”
15. Transfer Pricing Disclosure Compliance Checklist
- Have all related parties been identified?
- Have all relevant transactions been extracted?
- Are transaction categories correct?
- Do disclosed values reconcile with the financial statements?
- Do the values agree with TP documentation?
- Is the transfer pricing method consistent?
- Have applicable thresholds been tested?
- Have Connected Person requirements been reviewed?
- Have potential TP adjustments been assessed?
- Has the filing deadline been confirmed?
- Has the final disclosure been reviewed by the responsible tax professional?
A disclosure should be the final output of the TP compliance process, not the starting point.
How SBC Can Help With Transfer Pricing Compliance
Steadfast Business Consulting (SBC) supports businesses and multinational groups with transfer pricing compliance, documentation and advisory requirements.
- Transfer pricing compliance reviews
- Related-party transaction analysis
- Form 3CEB support
- UAE transfer pricing compliance
- Local File and Master File support
- Benchmarking analysis
- Functional, Asset and Risk (FAR) analysis
- Transfer pricing policy reviews
- TP audit and assessment support
- Cross-border transaction review
- Transfer pricing risk assessment
Frequently Asked Questions
What is a transfer pricing disclosure form?
A transfer pricing disclosure form is a tax filing or return schedule that reports specified related-party or controlled transactions and related transfer pricing information to a tax authority.
Is a transfer pricing disclosure form mandatory?
It depends on the jurisdiction and the taxpayer’s circumstances. India, UAE, Saudi Arabia, Qatar and Singapore each have different rules, thresholds and filing mechanisms.
Is Form 3CEB a transfer pricing disclosure form?
Form 3CEB is an accountant’s report required in India for taxpayers entering into international transactions or specified domestic transactions covered by the applicable rules.
What is the UAE transfer pricing disclosure threshold?
For the UAE Related Party Transaction Schedule, the FTA states that the aggregate value of transactions with all Related Parties must exceed AED 40 million. Once exceeded, categories exceeding AED 4 million must be disclosed. A separate Connected Person Schedule applies where aggregate payment or benefit exceeds AED 500,000 per Connected Person, subject to applicable rules.
Does Saudi Arabia require a transfer pricing disclosure form for small transactions?
Yes. ZATCA states that the Transfer Pricing Disclosure Form must be filed for controlled transactions irrespective of whether the total value is below SAR 6 million.
What is the Singapore transfer pricing disclosure threshold?
Singapore requires the Related Party Transaction Form when the value of related-party transactions disclosed in the financial statements exceeds S$15 million.
What is the Qatar transfer pricing declaration threshold?
Qatar’s official service information states that the Transfer Pricing Declaration applies where relevant group revenue exceeds QAR 10 million. Qatar also has transaction-level requirements and thresholds that should be assessed separately.
Does filing a disclosure form replace the Local File?
No. A disclosure filing and transfer pricing documentation serve different purposes. The disclosure provides prescribed information to the tax authority, while the Local File provides detailed support for the taxpayer’s arm’s length position.
What happens if the TP disclosure and Local File disagree?
The inconsistency can attract additional scrutiny because the tax authority may question the accuracy of reported transaction values, methods, classification, or underlying transfer pricing position.
Can a transfer pricing disclosure be corrected after filing?
Correction or revision depends on the jurisdiction and filing mechanism. Where an error is identified, taxpayers should review the applicable correction procedure promptly.
How should companies prepare a transfer pricing disclosure?
Companies should identify related parties, extract transaction data, classify transactions, reconcile values to financial statements, compare the information with TP documentation, test applicable thresholds and review potential TP adjustments before filing.