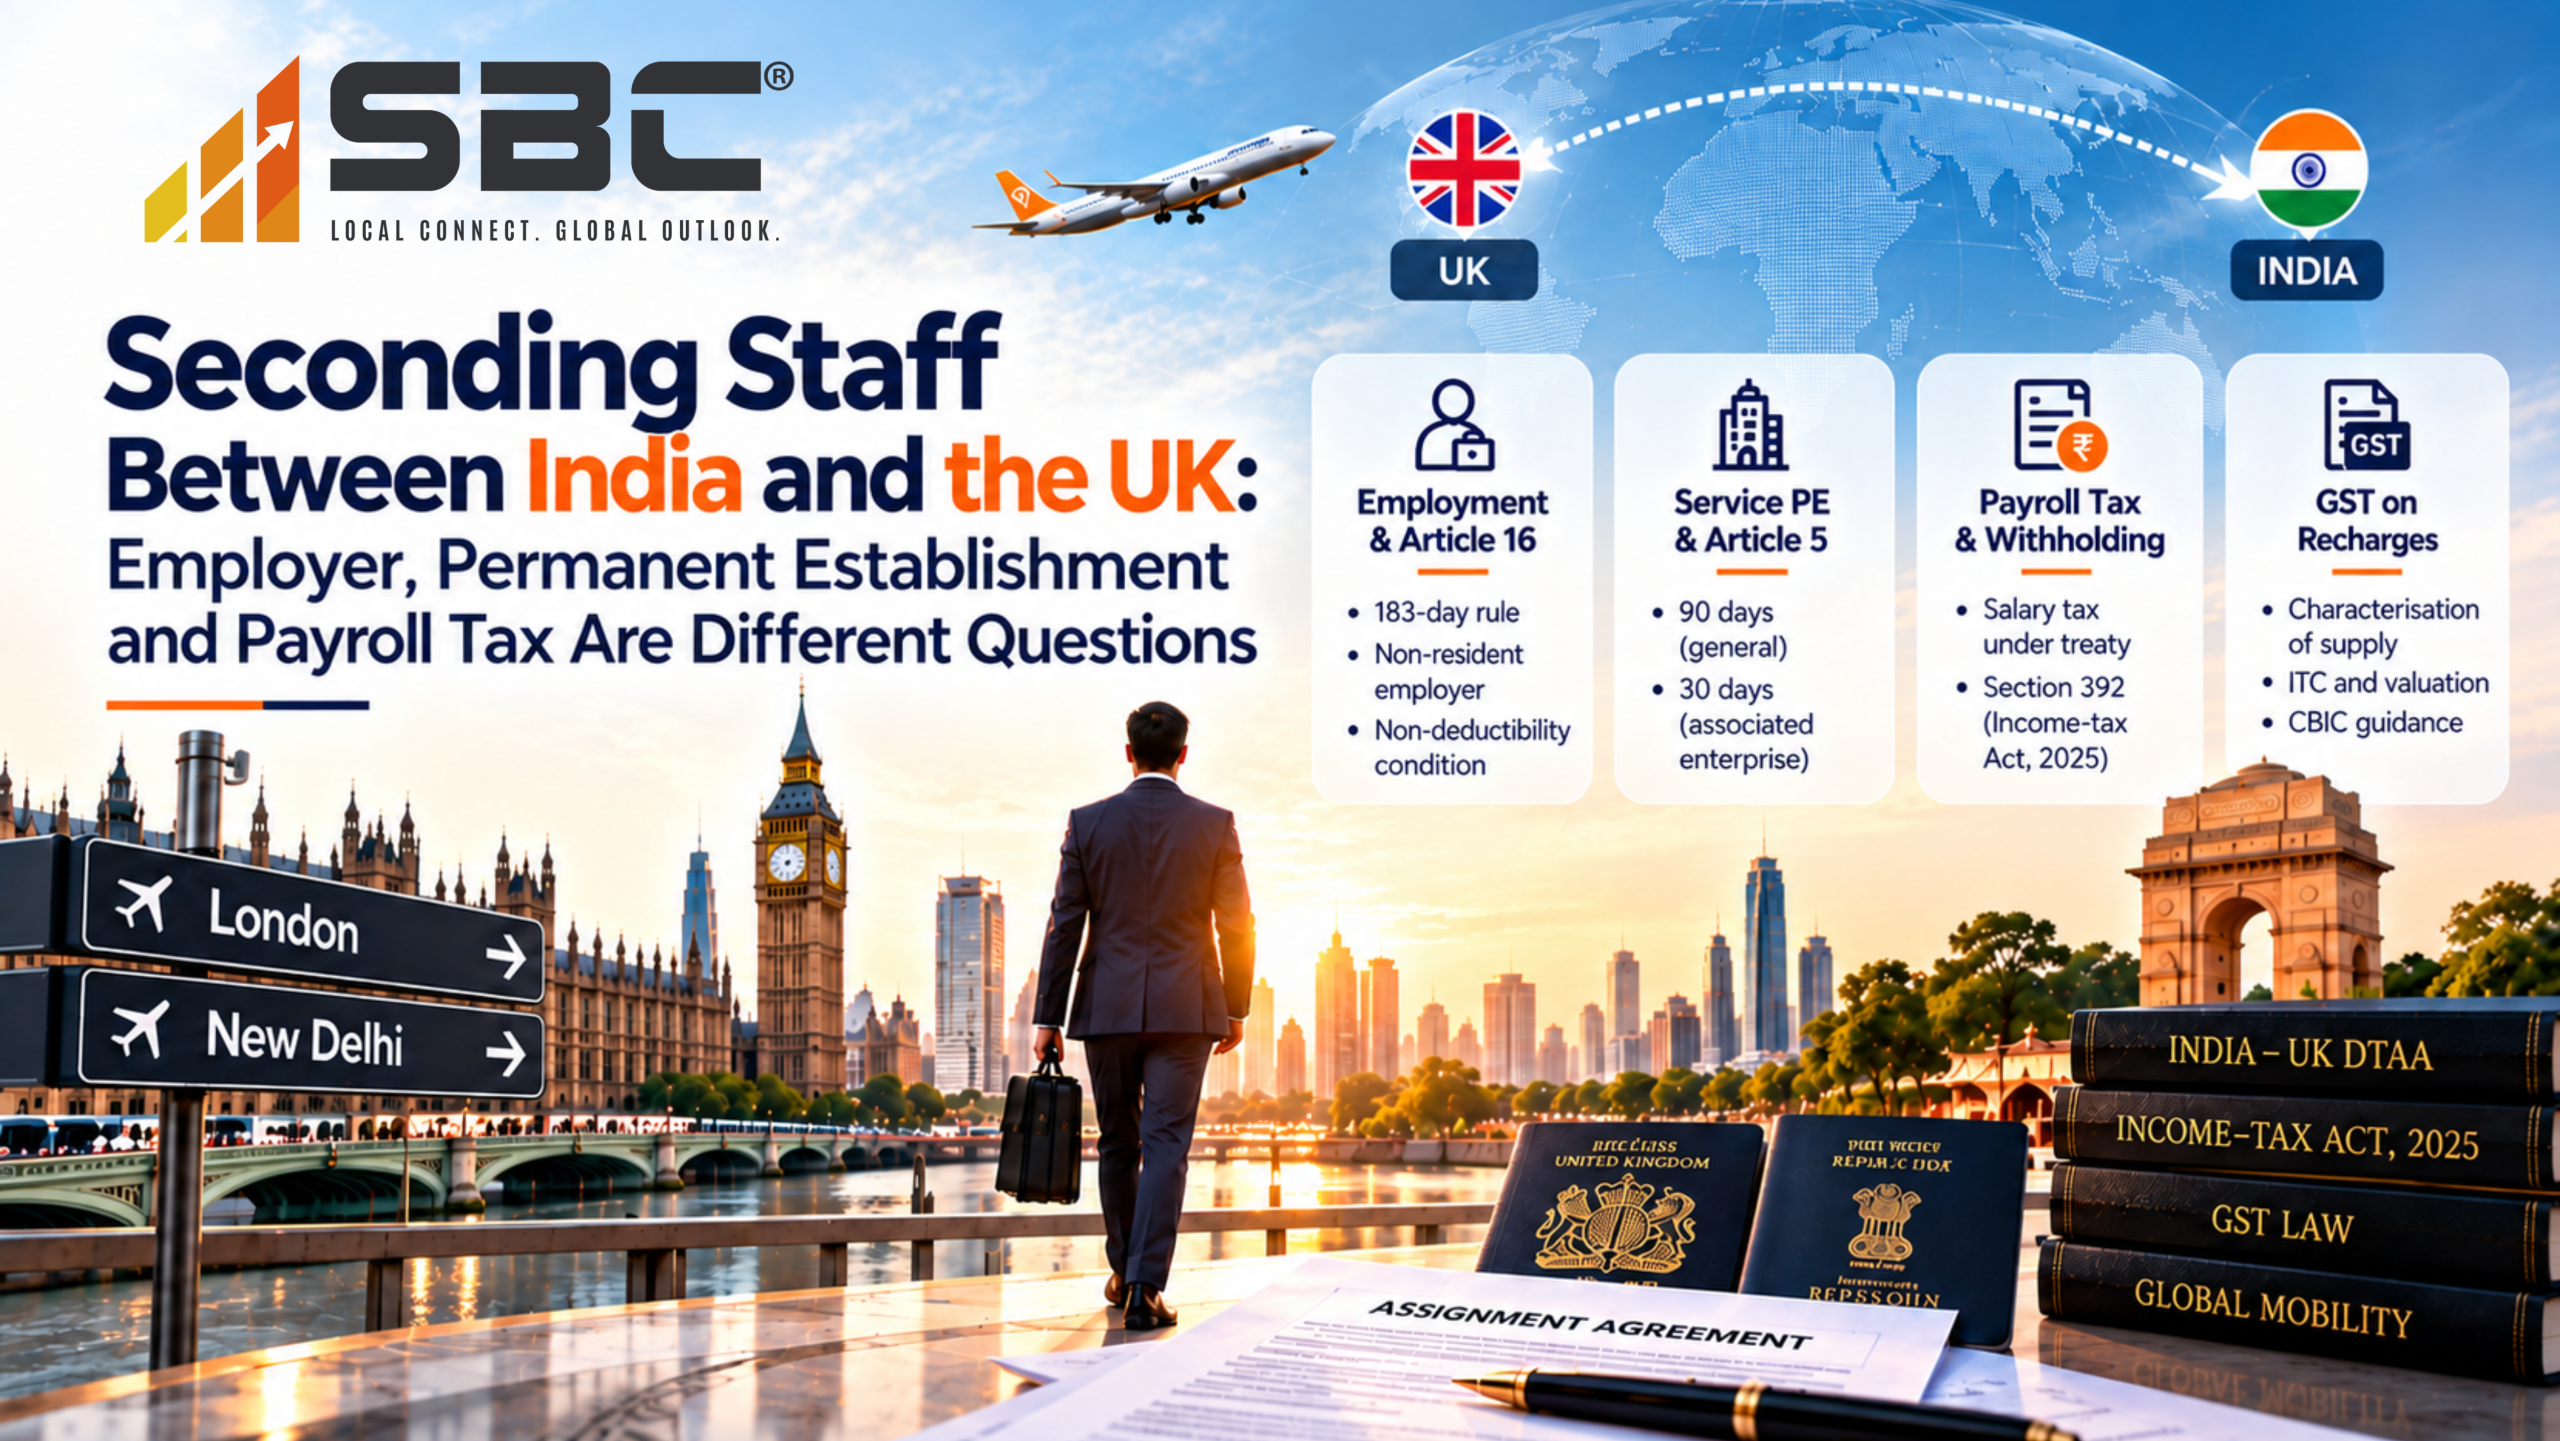
Seconding Staff Between India and the UK: Employer, Permanent Establishment and Payroll Tax Are Different Questions
Seconding Staff Between India and the UK: Employer, Permanent Establishment and Payroll Tax Are Different Questions
By CA Mithilesh Reddy, Founder and CEO, and CA Rajesh Vaishnav, Partner, Steadfast Business Consulting LLP | Direct Tax Advisory
Quick answer
In an India–UK secondment, salary tax, corporate permanent establishment and intercompany charging are separate questions. Article 16(2) of the India–UK treaty exempts short-stay salary only if the 183-day, non-resident employer and non-deductibility conditions are all met. Article 5(2)(k) service PE and the tax treatment of any recharge must be tested separately.
Key takeaways
- Salary tax, corporate permanent establishment and intercompany charging are three separate questions in an India-UK secondment; a favourable answer to one does not settle the others.
- Article 16(2) of the India-UK treaty exempts short-stay salary only if the individual is present for not more than 183 days in the relevant fiscal year, the employer is not resident in the State of work, and the remuneration is not deductible in computing the profits of an enterprise taxable in that State.
- Article 5(2)(k) is the service PE rule: more than 90 days in any twelve-month period, or more than 30 days where the services are performed for an associated enterprise.
- A recharge from the home entity to the host is not automatically fees for technical services or a taxable supply; characterisation depends on the real supply, the control matrix and the applicable statute and treaty.
- From 15 July 2026 the India-UK social security agreement (double contribution convention) is in force, so contribution exposure for detached workers should be re-examined separately from income tax.
Practice illustration: Tax treatment of temporary cross-border staff deployment
Issue. A group evaluated alternative contractual approaches for employees working across India and the United Kingdom.
Approach. The advisory compared employment characterisation, payroll withholding, service and agency permanent-establishment exposure, related-party recharges, indirect tax and social security.
Outcome. The group adopted a deployment compliance framework intended to mitigate the identified exposures. It was not a ruling that any particular tax liability was conclusively eliminated.
Practical lesson. Employment facts and legal obligations should match the chosen arrangement.
This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.
Introduction
International workforce deployment is often presented as a payroll question: which entity pays the employee and in which country does tax need to be deducted? That is rarely the whole problem. The economic employer may differ from the paying entity, and a group entity that deploys employees may create a permanent establishment through activities that have little to do with the salary remittance.
For an India–UK arrangement, one must analyse at least three separate taxpayers or tax positions: the employee, the entity supplying or deploying personnel, and the business that receives the work. The structure becomes especially sensitive where the host directs daily activities while the home entity retains the employment contract, compensation decisions or project risk.
This article provides a practical decision framework for that arrangement. It deliberately separates salary taxation, corporate profit attribution and intercompany-service characterisation, because a favourable answer to one does not settle the others.
1. The actual deployment model takes priority
Describe who recruited the employee, who may terminate the engagement, who decides the work programme, who evaluates performance, who bears employment risk and who receives the deliverables. A secondment agreement alone may not tell the whole story where the parties operate differently in practice.
The arrangement might be a temporary employment transfer, a foreign enterprise delivering services using its personnel, or a split arrangement in which the host has operational supervision while the home employer retains broader control. The answer should emerge from documents and practice, not from the title “secondment”.
2. Salary taxation under the India–UK treaty
The synthesised India–UK treaty places dependent personal services in Article 16. Its short-stay protection requires satisfying the relevant conditions together, including the presence threshold, the paying employer requirement and the treatment of remuneration in the source State.
The familiar 183-day test is not a free-standing exemption. If the conditions concerning employer residence and the bearing of remuneration are not met, salary may be taxable in the State where employment is exercised even for a short presence. Count days as the treaty directs and retain travel documentation.
3. Economic employer and the recharge trail
Payroll may continue with the home entity for administrative convenience. That fact should be tested against who is responsible for the work, who bears compensation cost, who controls the employee’s duties and whether the host is reimbursing salary or purchasing a wider commercial service.
Where a recharge is made, reconcile payroll records to the intercompany invoice and the receiving entity’s expense ledger. A recharge carrying overhead or a service margin may present a different corporate and withholding question from a pure cost recovery; it does not necessarily change the employee’s treaty position.
4. Service PE risk can arise independently
The India–UK treaty contains a service-related PE provision in its Article 5 framework, including a rule for services performed for an associated enterprise. The applicable day-counts and activity tests must be checked against the authenticated treaty wording and periods in question.
An employee may satisfy personal tax conditions without that resolving the deploying company’s PE risk. Track all relevant personnel, connected assignments, client projects and periods, not merely one employee’s travel in isolation. The company’s function in the host jurisdiction must be described.
5. Permanent establishment is not automatically a large profit
If a corporate PE is found, profit attribution remains a distinct exercise. It focuses on the functions, assets and risks of the PE rather than attributing all profits of the foreign employer to the country of deployment.
An engineer seconded to coordinate a discrete task may create an economic contribution very different from a team concluding customer contracts or independently delivering an integrated service. Payroll recharges, project accounting and management records should support the attributable profit analysis.
6. Payroll, social security and immigration cannot be combined into one rule
The tax residence of the employee, domestic salary withholding obligations, available foreign tax relief and any applicable social-security arrangements each require separate testing. A tax treaty article is not an immigration permission, and a visa designation does not determine tax ownership of a function.
Before departure, establish a host payroll policy, employer registrations where required, travel documentation, expected working-day count and the procedure to manage changes in deployment length. Late correction can be costly where work has already been performed.
7. Intercompany billing and indirect-tax characterisation
Where the home entity invoices the host, the supply may be characterised as a service depending on the facts. The GST or VAT analysis is separate from the employee’s income-tax treatment. The existence of an employment relationship does not automatically preclude scrutiny of an intercompany supply.
Where an Indian company receives employees from a related overseas entity, assess the law on import of services, valuation and input tax credit. The CBIC circular on related-party import-of-service valuation may be relevant, but it does not answer every secondment characterisation issue.
8. A deployment memorandum for the business
An effective memorandum should contain an employer and control matrix, compensation and recharge schedule, day-count tracker, corporate PE assessment, salary tax position, treaty evidence, GST or VAT analysis, immigration assumptions and escalation triggers.
Update that memorandum when deployment becomes longer, work shifts from execution to contract negotiation, the receiving company begins exercising substantive control, or recharge arrangements change. A well-drafted initial policy loses force if the actual deployment evolves without review.
What the India-UK treaty tests for salary and for service PE
Article 16(2) of the India-UK treaty exempts remuneration for employment exercised in the other State only if three conditions are met together: the individual is present for not more than 183 days in the relevant fiscal year, the remuneration is paid by or on behalf of an employer who is not resident in the State of work, and the remuneration is not deductible in computing the profits of an enterprise chargeable to tax in that State. A host company that bears the cost through a recharge can therefore defeat the exemption even for a short stay.
Article 5(2)(k) is the service PE rule. On the treaty text published by HM Revenue and Customs, furnishing services through employees or other personnel creates a permanent establishment where the activities continue for more than 90 days within any twelve-month period, and for more than 30 days within any twelve-month period where the services are performed for an enterprise associated with the provider. A secondment to an Indian group company should therefore be counted against the shorter threshold, across all connected personnel and assignments and not only for one traveller.
How have the courts treated seconded employees?
Two decisions show the range. In DIT v. Morgan Stanley & Co. (2007) 292 ITR 416, decided on 9 January 2007, the Supreme Court upheld the Authority for Advance Rulings’ view that employees deputed to an Indian affiliate can create a service PE for the foreign enterprise where it remains responsible for their work and they stay on its payroll or retain a lien on their jobs with it.
In Centrica India Offshore Pvt. Ltd. v. CIT, reported in May 2014, the Delhi High Court treated payments for seconded employees as fees for technical services under the India-UK and India-Canada treaties on the facts, rejected the ‘reimbursement’ label, and held that the host’s day-to-day control did not outweigh the fact that the individuals remained employees of the foreign parties. Neither decision says that every secondment is taxable. Both show that payroll location, the control matrix and the recharge basis will be read together.
What changed for social security from 15 July 2026?
The India-UK Comprehensive Economic and Trade Agreement and the Agreement on Social Security Contributions (the double contribution convention) enter into force on 15 July 2026, according to the Press Information Bureau. For detached workers, the convention is reported to exempt the worker and employer from host-country contributions while they remain covered in the home country, for a period reported as up to five years, provided a certificate of coverage is held. It does not cover workers recruited locally or who localise.
Earlier commentary on UK-India deployments noted the absence of any totalisation arrangement. That position changes for postings the convention covers, although income tax, treaty and permanent establishment analysis is unaffected. Confirm the period, the certificate process and the transitional rules from the agreement text.
A pre-deployment checklist
Before the first day of work, hold the signed secondment or service agreement and a control matrix showing who directs, evaluates, can terminate and bears the risk of the individual’s work. Add a compensation and recharge schedule reconciled to payroll and to the intercompany invoice, and a day-count tracker by individual and by project.
Record the employee’s residential status analysis, treaty position and Indian salary withholding plan under section 392 of the Income-tax Act, 2025 (section 192 of the 1961 Act). Add the corporate PE assessment under Article 5 and the profit attribution approach if a PE cannot be ruled out, the GST analysis of the recharge including the related-party import-of-service valuation position in Circular No. 210/4/2024-GST, Form 3CEB mapping where the deploying entity is an associated enterprise, and the foreign exchange and social security assumptions. Finally, list the events that require re-review: an extension, a shift from execution to contract negotiation, or a change in the recharge basis.
Conclusion
Cross-border staff deployment is a useful illustration of why tax analysis must follow economic facts. An employment contract, travel calendar and recharge invoice may each point to a different aspect of the arrangement.
A sustainable structure makes those records consistent from the outset. It does not treat an exemption under one tax regime as clearance under all the others.
Frequently asked questions
1. Is staying in the UK or India for fewer than 183 days sufficient?
Not by itself. All conditions in the applicable dependent-personal-services article must be satisfied.
2. Who is the employer if payroll is paid abroad?
The answer may require analysis of contractual and economic control; payroll location is one factor.
3. Can one seconded employee create PE exposure?
Potentially, depending on the treaty, activities and duration. There is no blanket exclusion.
4. Does a salary recharge always constitute fees for technical services?
No. Characterisation depends on the real supply, if any, and the applicable statute and treaty.
5. What should be prepared before deployment?
A work-scope and control matrix, day tracker, payroll and recharge plan, treaty assessment, and compliance checklist.
6. Does a seconded UK employee working in India for under 183 days pay Indian tax under the India-UK treaty?
Not necessarily. Under Article 16(2) the exemption applies only if presence does not exceed 183 days in the relevant fiscal year, the remuneration is paid by or on behalf of an employer not resident in India, and the cost is not deductible in computing the profits of an enterprise chargeable to tax in India. If the Indian host bears the cost through a recharge, the third condition can fail.
7. How many days create a service permanent establishment under the India-UK treaty?
Under Article 5(2)(k), services furnished through employees or other personnel can create a permanent establishment where the activities continue for more than 90 days within any twelve-month period, or more than 30 days where the services are performed for an associated enterprise. Check the wording in the MLI-modified text, and track days across all personnel and connected assignments, not one employee.
8. Is GST payable on salary recharged by a UK company to its Indian group company?
It can be. Where the overseas entity supplies services to a related Indian entity, the supply may be an import of services chargeable under reverse charge, depending on the facts. Circular No. 210/4/2024-GST dated 26 June 2024 addresses valuation of such imports where the recipient has full input tax credit, but it does not settle every secondment characterisation question.
Talk to SBC’s tax team
If you are planning to deploy staff between India and the UK, SBC’s team can discuss how the employment, permanent establishment, payroll, recharge and GST questions are tested together before the first posting. Explore our Income Tax services | Contact SBC
Related reading from SBC
- Employee Secondment and GST: Reading Northern Operating Systems with the CBIC Clarifications
- Attributing Profits to an Indian Project Office: Which Head Office Expenses Count?
- Shared Services from Singapore: Applying the ‘Make Available’ Test to Indian Withholding
- Parent Guarantee of an Indian Subsidiary: How Transfer Pricing, Withholding and GST Fit Together
- More articles on the SBC blog
About the author
CA Mithilesh Reddy, Founder and CEO, Steadfast Business Consulting LLP, led the team that handled this engagement.
CA Rajesh Vaishnav is a Partner at Steadfast Business Consulting LLP. SBC provides direct and indirect tax, international tax and transfer pricing advisory and dispute support.
Disclaimer
This article is general professional commentary and not advice on any particular facts. Treaty eligibility, applicable law, procedural requirements and statutory amendments must be verified for the relevant tax period. It is not a description of an identifiable client engagement.