CategoriesGST

GST Export Refunds When Receivables Are Netted Against Overseas Payables

GST Export Refunds When Receivables Are Netted Against Overseas Payables

By CA Rupesh Reddy and CA Mithilesh Sai Sannareddy, Founder and CEO, Steadfast Business Consulting LLP | Indirect Tax Litigation / Controversy

Quick answer

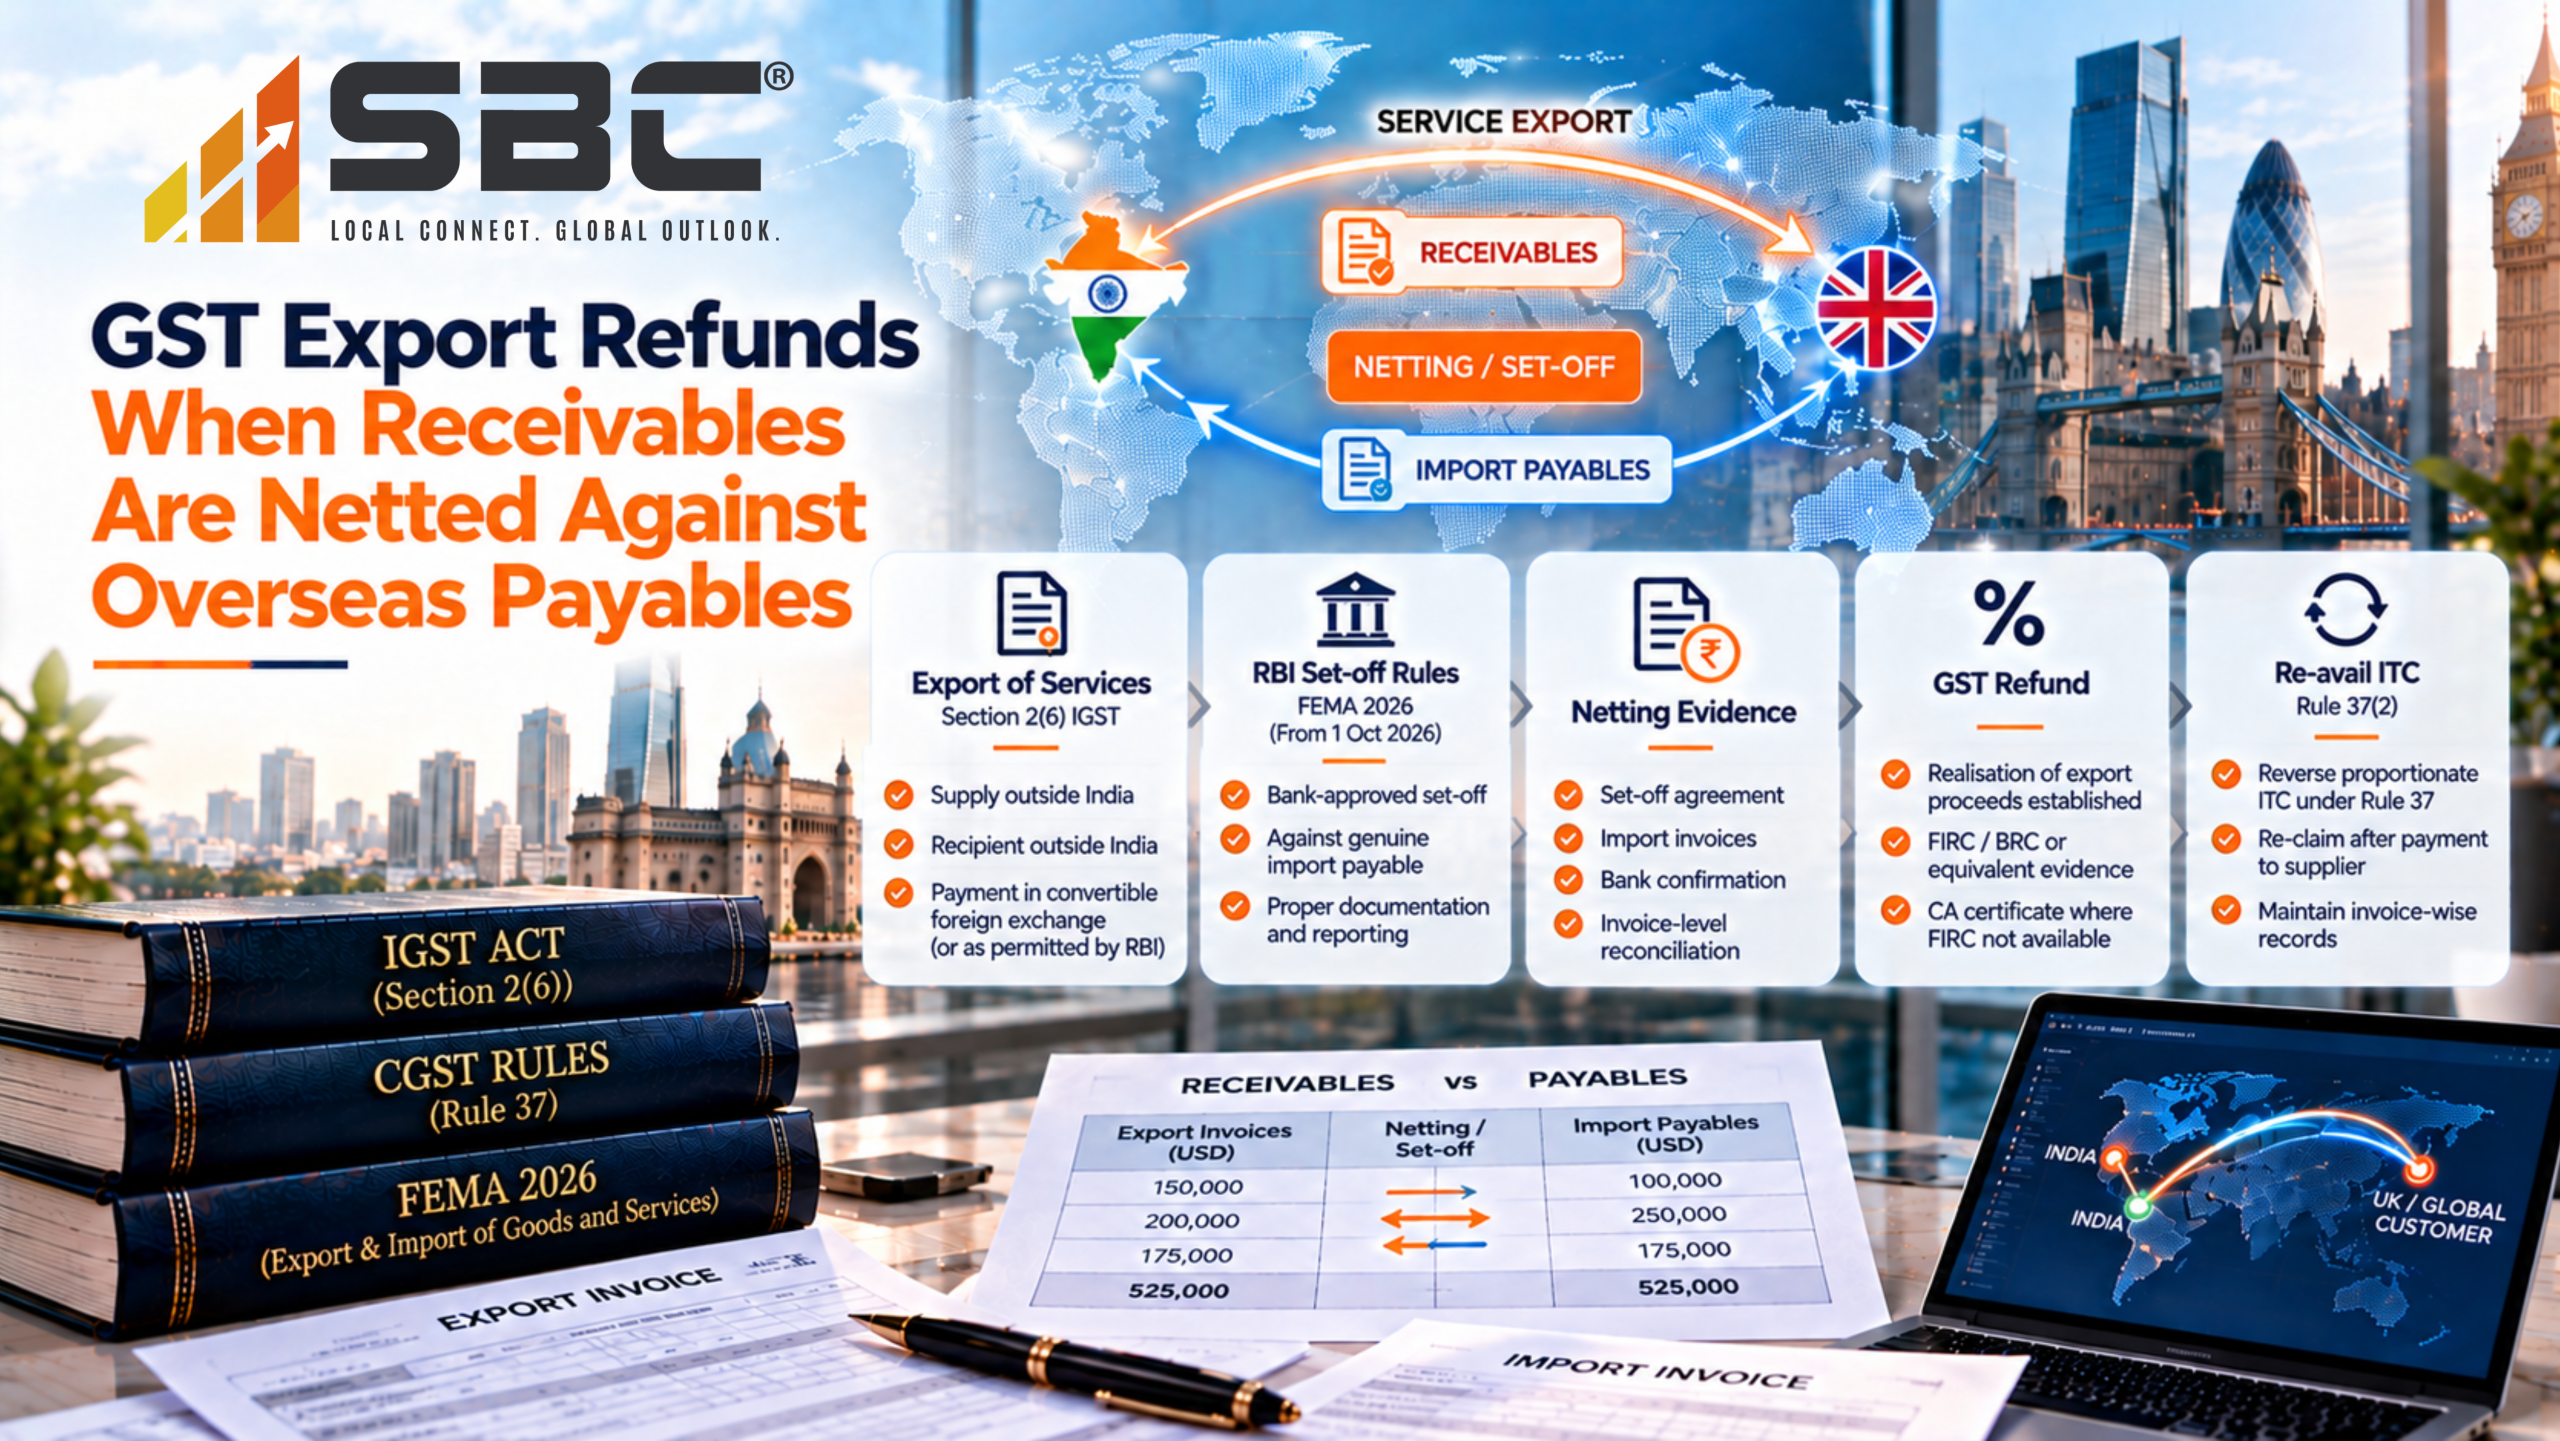
A bank-approved and legally documented set-off can be relevant evidence of settlement of export receivables, but a ledger netting entry alone is not enough. The supplier must establish the applicable RBI permission, the validity of the settlement, the corresponding import payable and satisfaction of the GST export-of-services conditions. Separate reconciliation of invoices, net receipts and bank reporting is essential.

Key takeaways

  • Section 2(6) of the IGST Act sets five cumulative conditions for export of services, and one of them is that payment is received in convertible foreign exchange or in Indian rupees where the Reserve Bank permits it.
  • A ledger netting entry alone does not prove realisation; a set-off permitted by the authorised dealer bank under RBI rules, against a genuine and enforceable import payable, is the evidence that matters.
  • The RBI set-off framework changed on 1 October 2026, when the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 (Notification No. FEMA 23(R)/2026-RB, 13 January 2026) replaced the 2015 export regulations; the rule in force on the settlement date applies.
  • The Gujarat High Court has set aside refund rejections based only on the absence of FIRCs where a CA certificate and RBI-approved netting records proved receipt (Kuehne + Nagel, reported November 2025).
  • The refund file should bridge each export invoice to the set-off agreement, the import payable, the bank confirmation and the GST returns, invoice by invoice.

Practice illustration: Netting of cross-border service receivables

Issue. An export-of-services refund claim was questioned because contract receivables were settled through a netting arrangement.

Approach. The response examined the applicable foreign-exchange permissions, authorised-dealer records and invoice-level matching of receivables and payables.

Reported position or outcome. The refund claim was defended on the basis of the permitted settlement mechanism and corresponding records. No final sanction or payment of the refund is claimed.

Practical lesson. An accounting set-off by itself is not evidence of permitted realisation.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

Cross-border groups regularly settle intercompany balances on a net basis. One group entity may owe service fees to an Indian company while another balance runs in the opposite direction. Instead of remitting the gross amounts twice, the group settles the difference through a controlled arrangement and records the set-off.

That treasury process may be commercially sensible and permitted under the applicable foreign exchange rules. Yet a GST refund officer reviewing an export-of-services claim can ask why the full invoice value is not supported by a separate foreign inward remittance certificate. The resulting dispute is not simply about a missing certificate. It is about whether the statutory receipt condition is satisfied and what evidence proves realisation.

A defensible refund file requires three records to agree: the contractual right to payment, the permitted netting arrangement and the invoice-level treatment in the GST refund working. This article sets out how to build that proof without assuming every internal journal entry constitutes receipt.

1. The export-of-services conditions are cumulative

Section 2(6) of the IGST Act defines export of services through separate conditions addressing supplier location, recipient location, place of supply, receipt of payment in permitted foreign exchange or rupees and the relationship between establishments. Fulfilling four of the five does not excuse the remaining condition.

The realisation requirement must be examined in the light of RBI permissions and the legal form of settlement. Classification as an export also requires a correct place-of-supply analysis. A refund application cannot be defended solely by proving that the customer is located overseas.

2. Netting is not synonymous with waiver or write-off

A valid set-off extinguishes an export receivable by applying it against a genuine corresponding payable under an enforceable arrangement. A commercial waiver, credit note, unapproved internal offset or later accounting write-off may have different consequences. The distinction must be demonstrated.

Describe the gross receivable, the gross payable, parties involved, settlement currency, agreement and date of discharge. Explain whether the Indian entity dealt with the same overseas counterparty or a group netting centre and whether the structure meets the particular RBI permission relied upon.

3. The RBI framework is a legal gateway

The RBI directions on set-off of export receivables against import payables provide specified conditions under which authorised dealer banks may permit bilateral and qualifying group settlements. Conditions include oversight by an authorised dealer bank, genuine underlying transactions and applicable reporting requirements.

Do not assume that every multilateral treasury netting programme qualifies. Some restrictions concern the category of imports and exports, counterparty arrangements, outstanding periods and documentary requirements. The instrument in force on the date of settlement should be checked. The RBI circular of 4 December 2020 (A.P. (DIR Series) Circular No. 08) applied to earlier settlements; from 1 October 2026 the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 (Notification No. FEMA 23(R)/2026-RB dated 13 January 2026), which supersede the 2015 export regulations, apply, with Regulation 7 dealing with set-off.

4. What a bank confirmation should actually say

A generic letter confirming a bank relationship adds little. Useful evidence identifies that the authorised dealer permitted the relevant set-off arrangement, the entities or group scheme involved, the invoice or settlement statements, and how the export and import legs were reported and closed.

Where an AD bank issues settlement advice or other confirmation, reconcile it against the company’s ledger and the group netting statement. If bank reporting remains incomplete, obtain clarification rather than treating the accounting entry as conclusive proof that foreign exchange requirements were satisfied.

5. The GST refund formula requires separate working

An application for refund of accumulated input tax credit under section 54 and the relevant rules uses prescribed turnover and eligible credit computations. These are not identical to a list of issued export invoices. Amounts realised in the relevant period and the statutory definition of export turnover must be addressed.

For services, refund rules call for documentation linking invoices to realisation. The CBIC refund rules resource describes invoice and bank-realisation evidence. Verify the latest notified rule text and portal instructions for the claim period.

6. Build an invoice-by-invoice settlement bridge

The reconciliation should contain export invoice number, date, customer, amount, currency, contract, outstanding balance, related import payable, set-off agreement reference, settlement period, bank confirmation, cash remittance if any, amount shown as realised, and any adjustment or credit note.

A single summary figure may conceal unapplied advances, reversals, duplicate settlement entries or transactions outside permitted netting. Reconcile the schedule to GSTR-1, GSTR-3B, books, foreign currency ledgers, bank records and the refund statement. Explain every difference.

7. The import leg should be real and independently evidenced

The credibility of set-off depends on the existence of an enforceable payable. Preserve invoices for the relevant import of goods or services, tax documentation, contract, receipt of service or goods, books and bank reporting. Where GST reverse charge applies, its treatment should be reconciled separately.

A netting arrangement cannot rescue an export-realisation claim where the supposed import payable is merely an unsupported journal provision or a balance between parties that do not fall within the relevant RBI permission.

8. Limitation, deficiency memos and appeal strategy

A refund notice often identifies absence of FIRCs as the shortcoming. Respond by explaining the alternative permitted settlement mechanism and providing a source-indexed evidence set. Where the officer disputes legal eligibility, isolate the statutory issue from a curable document deficiency.

Preserve prescribed response and appeal deadlines and maintain a timeline of refund filing, deficiency memos, supporting records and sanction or rejection orders. Interest and consequential re-credit issues should be reviewed independently after any favourable appellate outcome.

9. Treasury controls that prevent future refund disputes

Before implementing group netting, the treasury team should obtain tax and foreign-exchange clearance for the specific entities and transaction classes. Document the bank-approved method, use monthly invoice mapping and retain settlement statements in an audit-ready location.

Export GST compliance should receive the bank closure confirmation contemporaneously. A treasury settlement that cannot be reconstructed twelve months later may be valid commercially yet expensive to defend in a refund examination.

The RBI set-off framework changed on 1 October 2026

The Reserve Bank notified the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026 on 13 January 2026 (Notification No. FEMA 23(R)/2026-RB), with effect from 1 October 2026, superseding the 2015 export regulations without affecting things done before that date. Regulation 7 allows an authorised dealer bank to permit set-off of export receivables against import payables with the same overseas buyer or supplier, or with its overseas group or associate companies, within the period allowed for realisation of export proceeds or any extension granted by the bank. Commentary notes that set-off between goods and services legs, which the December 2020 circular did not allow, is now permitted. The RBI consolidated text, as amended up to 22 September 2026, also shows revised realisation periods for services exports, which should be confirmed from the notified amendment.

For a GST refund, the practical consequence is that the applicable instrument depends on the date of each settlement. Settlements up to 30 September 2026 were tested against the 2020 circular, which among other things required one authorised dealer bank to supervise the arrangement, a verifiable agreement or consent, gross reporting of each export and import leg, and legs falling within the same calendar year. Settlements from 1 October 2026 are tested against the 2026 Regulations and the bank’s internal policy. A multi-year refund file may need to deal with both.

How courts have treated FIRC requirements where netting is permitted

Rule 89(2)(c) of the CGST Rules requires a statement of invoices with the relevant Bank Realisation Certificates or Foreign Inward Remittance Certificates for export of services. Where there is no remittance of the net sum because the receivable was set off, an FIRC may not exist for the full invoice value. In Kuehne + Nagel Pvt. Ltd. v. Union of India, reported from the Gujarat High Court on 6 November 2025, exports were made under an RBI-permitted gearing account that allowed netting of foreign-currency receivables and payables. Refunds were rejected because FIRAs were produced instead of FIRCs and a CA certificate was treated as inconsistent. The High Court set aside the rejection, holding that an FIRC is not the only mode of proving foreign exchange realisation, that a CA certificate based on books and records must be considered, and that a circular cannot override undisputed evidence. A Gujarat High Court decision reported in July 2025 reached a similar result for a logistics business operating an RBI-approved netting mechanism.

These decisions help, but they turned on their own records, and the Court’s concern was that receipt was not in doubt. A taxpayer should not read them as removing the burden of proof. In particular, the Delhi High Court’s 2024 decision that BRCs are not a necessary condition rests on Circular No. 125/44/2019-GST, which concerns goods exports and does not carry over to services.

Limitation, documents and common mistakes

A claim for refund must be filed within two years of the relevant date under section 54 of the CGST Act. For services exported without payment of tax, the relevant date is generally the date on which payment is received in convertible foreign exchange or permitted rupees, so the date on which a set-off validly discharged the receivable should be established and recorded rather than assumed to be the invoice date. A refund rejection is appealable to the first appellate authority under section 107 and then to the GST Appellate Tribunal under section 112; the Tribunal was launched on 24 September 2025 and, per commentary, began hearing cases on 16 February 2026, with State Benches being added through 2026.

The documents to assemble are the export contract, the invoices and the GSTR-1 and GSTR-3B mapping; the set-off agreement and the authorised dealer’s permission or confirmation; the import-side contracts, invoices and evidence of receipt of service or goods; the gross export and import reporting in the RBI systems; the net settlement statement; and a CA certificate reconciling these to the refund claim. Common mistakes are relying on a summary schedule, mixing goods and services legs, treating a credit note or write-off as set-off, ignoring a difference between the realised and invoiced amounts, and failing to align the refund statement with the period in which payment was realised.

Conclusion

Cross-border netting cases turn on a distinction between accounting settlement and legally supported realisation. Treating every netting entry as a remittance is too broad; treating every arrangement without an individual FIRC as unrealised is equally simplistic.

The strongest refund file brings together the RBI authority, contractual netting mechanism, authorised dealer records and invoice-level GST reconciliation. That evidence needs to exist while the arrangement operates, not be invented after a deficiency memo.

Frequently asked questions

1. Does a journal entry establish receipt of export proceeds?

Not by itself. The legal settlement and applicable RBI permission must be demonstrated.

2. Are all multilateral group netting arrangements permitted?

No. The applicable RBI requirements, bank oversight and entity/transaction conditions must be checked.

3. Does an export invoice automatically qualify for refund turnover?

No. The relevant refund formula and realisation conditions must be applied.

4. Can a bank letter help defend netting?

Yes, especially where it specifically identifies the permitted arrangement and reconciles settlement records.

5. What is the best evidence to present first?

An invoice-level reconciliation tying contracts, set-off documents, authorised dealer evidence and GST returns together.

6. Is an FIRC mandatory for a GST refund on export of services?

Rule 89(2)(c) of the CGST Rules requires a statement of invoices with the relevant BRCs or FIRCs for export of services. Courts, including the Gujarat High Court in November 2025, have set aside rejections based only on a missing FIRC where a CA certificate and RBI-approved netting records proved receipt of foreign exchange. Each case turns on its evidence.

7. Can export receivables be netted against import payables under FEMA?

Yes, within limits. Under Regulation 7 of the Foreign Exchange Management (Export and Import of Goods and Services) Regulations, 2026, in force from 1 October 2026, an authorised dealer bank may permit set-off with the same overseas buyer or supplier or with overseas group or associate companies. Earlier settlements were governed by RBI’s December 2020 circular, which was more restrictive.

8. What is the time limit for a GST refund of unutilised ITC on export of services?

A refund application must be filed within two years from the relevant date under section 54 of the CGST Act. For services exported without payment of tax, the relevant date is generally the date of receipt of payment in convertible foreign exchange or permitted rupees. Where proceeds are netted, the date of a valid set-off should be recorded and supported.

9. Is payment in Indian rupees accepted as export of services under GST?

Yes, where the Reserve Bank permits it. Section 2(6)(iv) of the IGST Act accepts payment in Indian rupees wherever permitted by the RBI, and CBIC Circular No. 202/14/2023-GST dated 27 October 2023 clarifies that export proceeds received through a Special Rupee Vostro Account satisfy the condition, subject to the Foreign Trade Policy and RBI conditions.

Talk to SBC’s tax team

If an export refund is held up because proceeds were netted or no FIRC is available, an invoice-level review of the set-off permission, the import payable and the bank evidence can show where the file stands before a reply is due. Our GST team can discuss the facts. Explore our GST services | Contact SBC

Disclaimer

This article is general professional commentary and not advice on any particular facts. Applicable law, RBI directions, procedural requirements and statutory amendments must be verified for the relevant tax period. It is not a description of an identifiable client engagement.
CategoriesGST

Employee Secondment and GST: Reading Northern Operating Systems with the CBIC Clarifications

Employee Secondment and GST: Reading Northern Operating Systems with the CBIC Clarifications

By CA Rupesh Reddy and CA Mithilesh Sai Sannareddy, Founder and CEO, Steadfast Business Consulting LLP | Indirect Tax Litigation / Controversy

Quick answer

A cross-border secondment is not automatically a taxable manpower supply merely because the foreign group company processes payroll. Nor is every recharge outside GST. Characterisation follows the contracts, control, employment obligations and actual conduct. Where an import of services between related persons is established, valuation and full-credit treatment require a separate examination under the governing rules and CBIC guidance.

Key takeaways

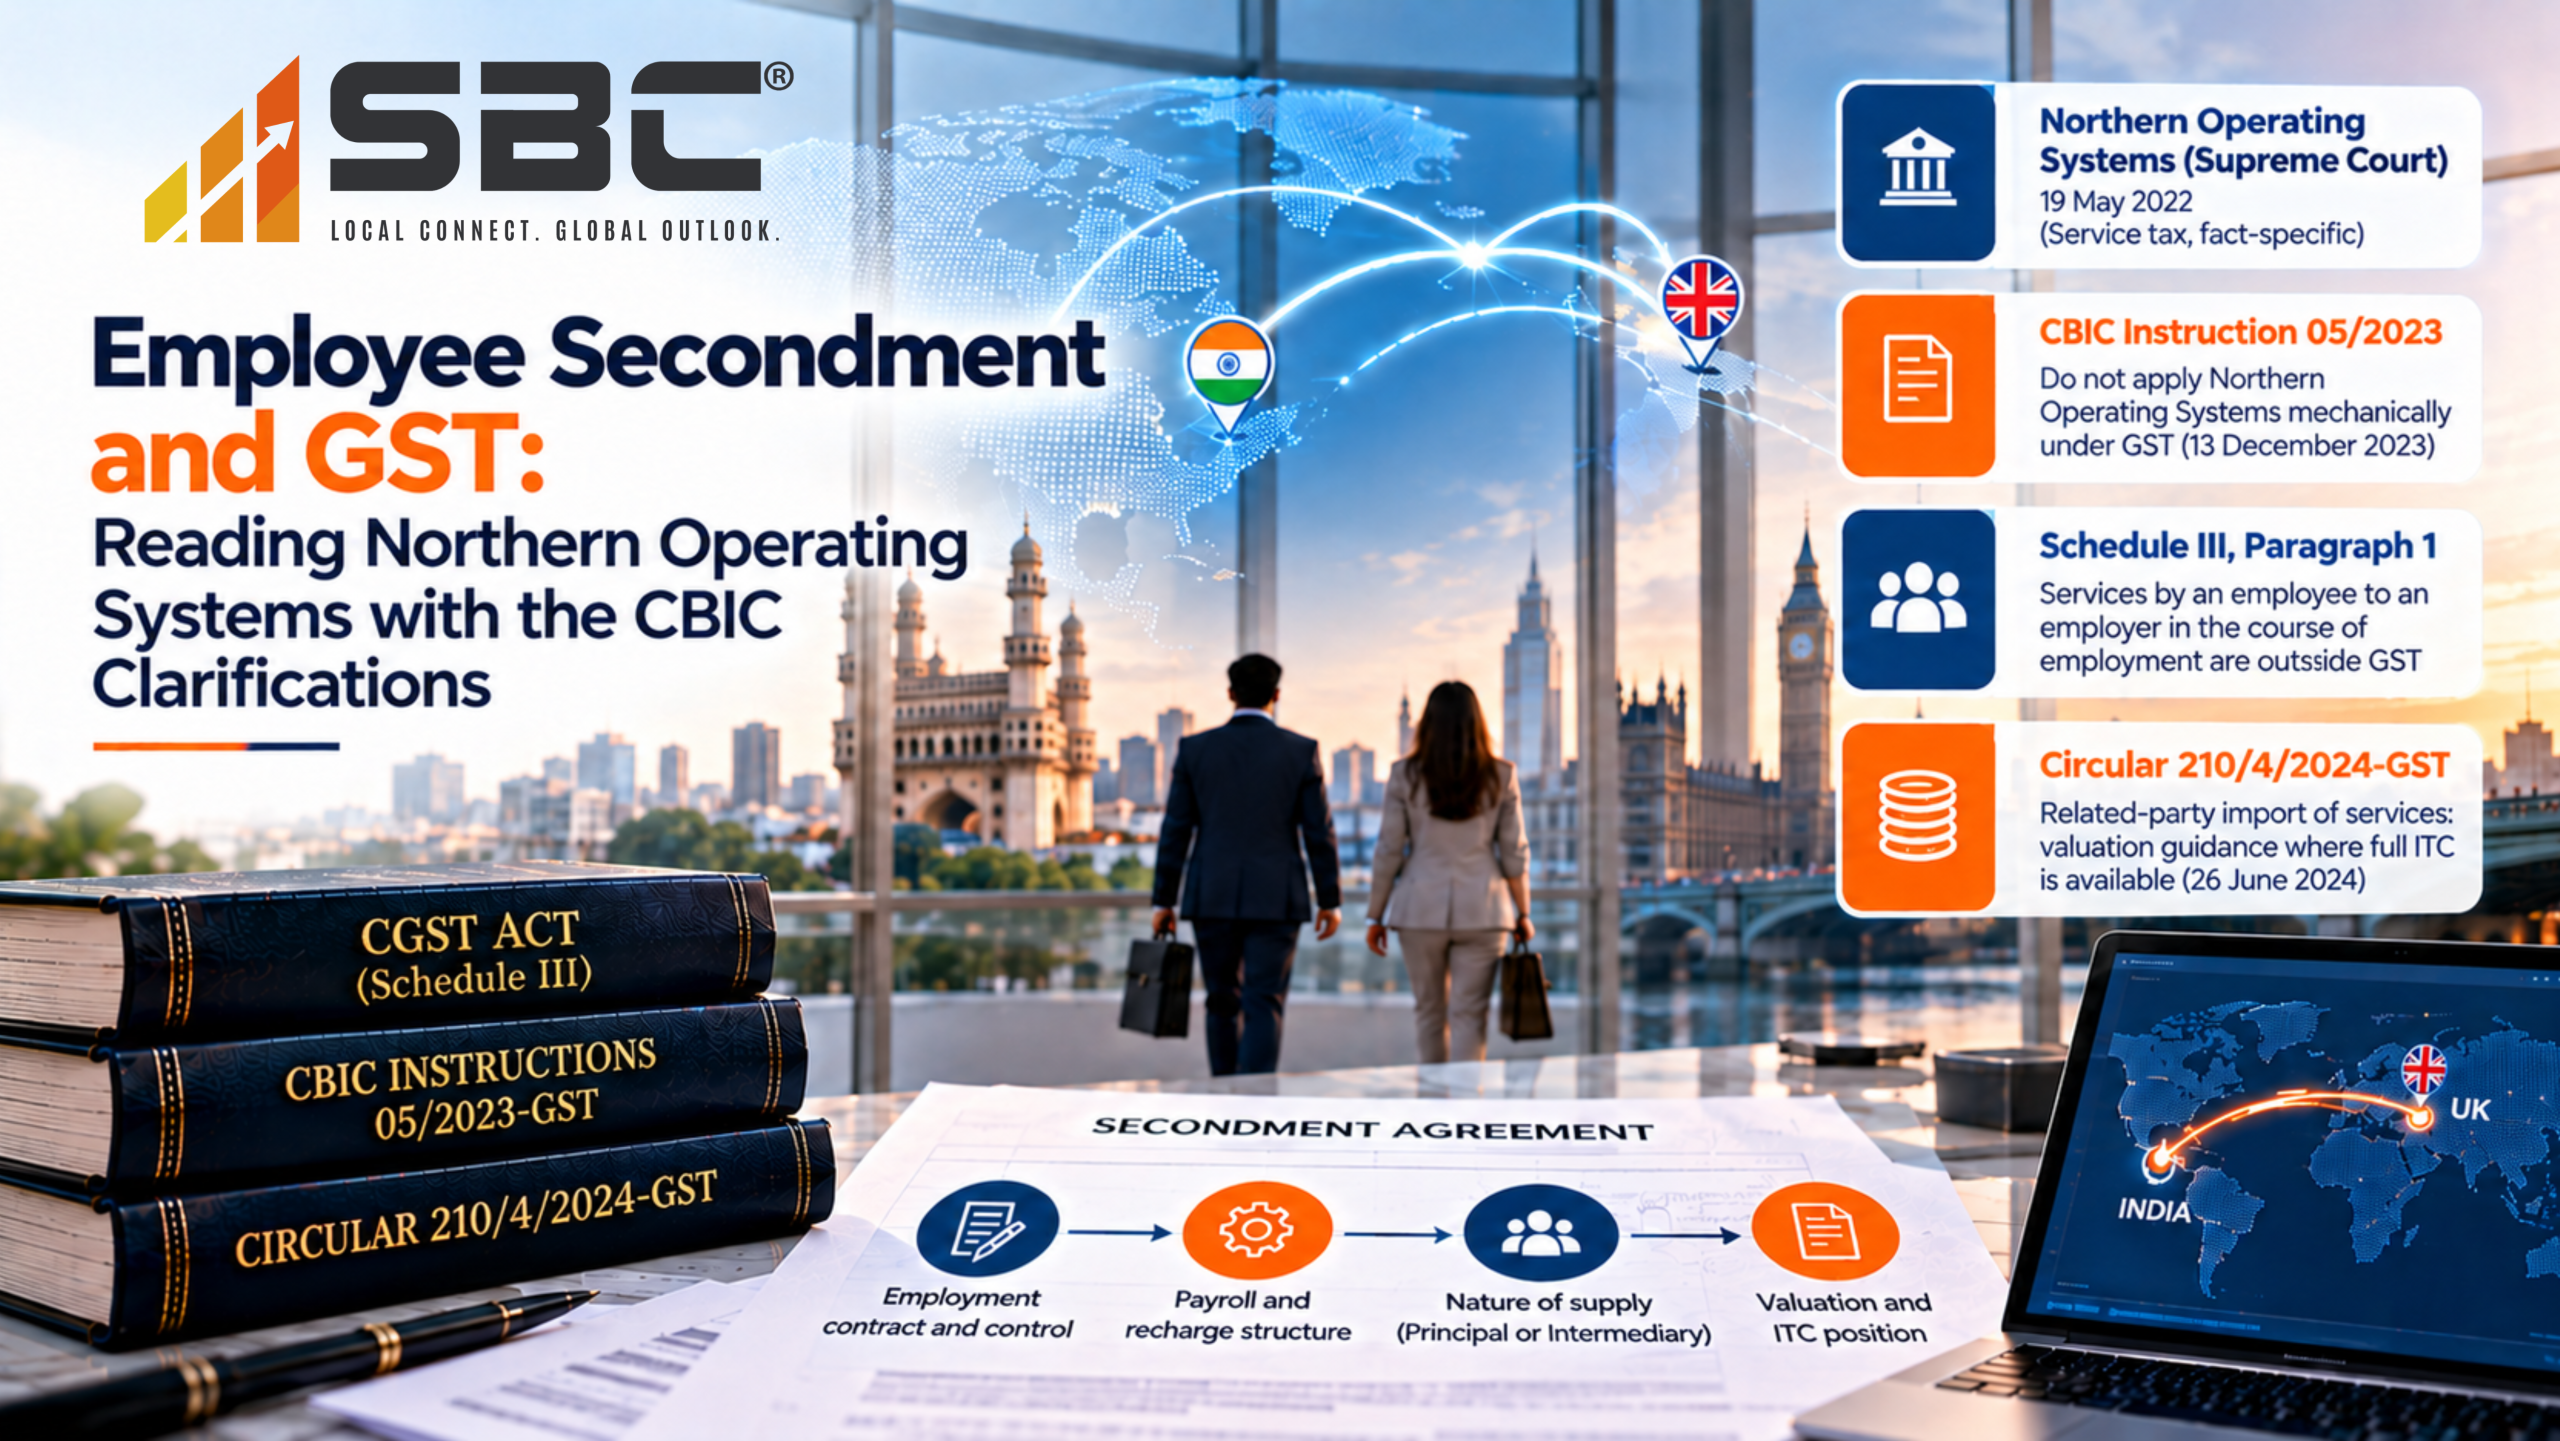
  • The Supreme Court’s decision in Northern Operating Systems (19 May 2022) was rendered under service tax and turned on its own facts, and CBIC Instruction No. 05/2023-GST dated 13 December 2023 tells officers not to apply it mechanically to GST.
  • Services by an employee to an employer in the course of employment are outside GST under paragraph 1 of Schedule III to the CGST Act, so the genuineness of the employment relationship is the primary question.
  • Circular No. 210/4/2024-GST dated 26 June 2024 deals only with valuation: where a related-party import of services is made to a recipient with full input tax credit, the invoice value is accepted and a nil value is accepted where no invoice is issued.
  • High Courts have applied the employment and valuation reasoning in the taxpayer’s favour on the facts before them, including the Delhi High Court in Metal One (2024) and the Karnataka High Court in Alstom Transport India (2025) and Huawei (reported 2026).
  • An employee-wise evidence matrix reconciled to payroll, books and bank records is the strongest response to a secondment notice.

Practice illustration: Taxability of employee secondment arrangements

Issue. A GST notice questioned whether employees working for an Indian enterprise were supplied by an overseas group entity.

Approach. The response relied on employment contracts, actual supervision, payroll records, statutory withholding and alternative valuation analysis.

Reported position or outcome. The response contested the secondment allegation and addressed the exposure using employment and payroll evidence. No departmental acceptance, withdrawal of the notice or completed adjudication is claimed.

Practical lesson. Characterisation must be established before discussing valuation.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

A secondment dispute often begins with a seemingly simple fact: employees working in India are paid by an overseas group company, and some or all of the cost is recharged to the Indian entity. The department may view the arrangement as a supply of personnel services, while the taxpayer may contend that the individuals are, in substance, its own employees.

The Supreme Court’s decision in Northern Operating Systems became a focal point for such disputes. Yet treating it as a universal declaration that every secondment is taxable is no more accurate than treating salary reimbursement as a universal exemption. The inquiry is highly dependent on the employment structure and the law applicable to the period.

The CBIC issued instructions after that decision and later clarified the valuation of certain related-party imports of services where the Indian recipient is entitled to full input tax credit. Those developments should be read together, but they address different questions and must not be collapsed into one defence.

1. What Northern Operating Systems decided and what it did not

The Supreme Court examined a particular employment arrangement under the service tax law, including the foreign entities’ continued roles, the contracts and the treatment of consideration. Its reasoning requires attention to the full factual structure. The case cannot simply be copied into a GST show-cause notice without testing the charging provisions and facts of the assessee under examination.

The pre-GST statutory setting and the post-2017 GST architecture are not identical. A proper submission identifies the taxable period, the nature of the alleged supply and the statutory mechanism said to create the liability before discussing the Supreme Court decision.

2. The department must identify the alleged supply

A notice should explain who supplied what, to whom, and against which consideration or statutory deeming provision. If a host company genuinely employs workers who operate under its direction and are integrated into its organisation, the contractual and functional evidence may support its position that the services of employees to the employer are outside the charge under Schedule III.

Where the foreign enterprise undertakes to provide skilled personnel or deliver specified services while retaining employer-like obligations and commercial responsibility, the analysis may point in another direction. Payment through foreign payroll is one fact, not the charging provision.

3. Why the employment documents matter

Compare the secondment agreement with appointment letters, visas, local HR policies, appraisal records, leave approval, termination rights, reporting lines, disciplinary authority, insurance and compensation obligations. Identify who controls the employee’s day-to-day work and who bears the consequences if it is not performed.

A secondment letter calling the host “employer” may be contradicted by the real arrangement. Conversely, an overseas payroll slip should not outweigh substantial evidence that the employee works under the host’s exclusive employment control during the period.

4. CBIC Instruction 05/2023: no mechanical invocation of the judgment

The CBIC issued Instruction No. 05/2023-GST on 13 December 2023 on the departmental treatment of the Supreme Court’s decision of 19 May 2022 in Northern Operating Systems in secondment cases. Practitioners should read the complete instruction, including its case-specific caution and directions about investigation.

The instruction is useful to insist on a proper factual inquiry. It is not a statutory declaration that all secondments are exempt. In an audit, the taxpayer should provide enough contemporaneous evidence for the officer to evaluate the arrangement actually implemented.

5. Related-party services and Schedule I

Under Schedule I of the CGST Act, certain imports of services from related persons or other establishments in the course or furtherance of business may be treated as supplies without consideration. That provision should be considered only once the alleged nature and source of the service are properly identified.

It is important to avoid circular reasoning: merely because the companies are related does not establish that a distinct overseas entity supplied manpower services on every occasion when salary costs were borne or reimbursed. The department still needs a coherent account of the supply relied upon.

6. What Circular 210/4/2024 addresses

Circular No. 210/4/2024-GST dated 26 June 2024 addresses valuation of import of services by a related person where the recipient is eligible for full input tax credit; its paragraph 3.7 treats the value declared in the recipient’s invoice as the open market value and accepts a nil value where no invoice is issued. It provides important guidance on the application of the valuation rules, including the significance of invoicing and the circumstances described in the circular.

The circular operates at the valuation stage. It does not eliminate the need to identify the supply or decide the applicability of Schedule III. Nor should full input tax credit be asserted without verifying the recipient’s actual eligibility and any blocked, exempt or mixed-use credit restrictions.

7. Zero valuation, full credit and evidentiary burden

A taxpayer may rely on the CBIC treatment where the conditions of the circular are satisfied. The assessment file should demonstrate eligibility to full input tax credit for the relevant supply and tax period and explain how invoices or absence of invoices were dealt with.

A demand based on a hypothetical payroll figure should be challenged with the correct valuation framework rather than an unsupported assertion that reimbursements never constitute consideration. Keep the primary classification and the alternative valuation arguments distinct.

8. Prepare an employee-wise evidence matrix

The matrix should list employees, home entity, host entity, employment agreements, local reporting manager, salary bearer, recharge basis, contractual termination and control rights, relevant dates, local tax withholding and any intercompany invoicing. Reconcile these data to payroll, general ledger and bank records.

Add a separate tab setting out the department’s factual allegation against the supporting or contradictory document. The strongest defence generally explains concrete inconsistencies in the notice, not simply quotes a court decision or a circular at length.

9. Procedural defence and alternative tax computation

If the show-cause notice is vague about the service or valuation, raise that defect expressly. At the same time, put forward the primary submission that no distinct taxable supply arose where the evidence supports it. Then, without concession, explain the alternative treatment if the authority finds a supply under Schedule I.

Any claimed interest, penalty or extended-period demand requires its own factual test. Do not concede suppression merely because the taxpayer used a different legal characterisation. Full disclosure in audited records and contemporaneous correspondence may be relevant to the limitation and penalty discussion.

What the Supreme Court decided in Northern Operating Systems, and what followed

In the Commissioner of Customs, Central Excise and Service Tax, Bangalore (Adjudication) v. Northern Operating Systems Pvt. Ltd. (Civil Appeal Nos. 2289-2293 of 2021, decided on 19 May 2022), the Supreme Court held, under the service tax law, that the Indian company was the recipient of manpower supply services from overseas group companies and was liable to service tax under reverse charge. The Court looked at the substance of the arrangement over its form, including control over the seconded employees and who gained economically from their work, and said that no single factor is conclusive.

After that decision, field formations began issuing GST notices on secondment arrangements. The CBIC responded with Instruction No. 05/2023-GST of 13 December 2023, which says that secondment is not only a service tax issue, that each arrangement must be examined on its facts, that the judgment should not be applied mechanically, and that the extended period under section 74(1) cannot be invoked merely because GST was not paid. Circular No. 210/4/2024-GST of 26 June 2024 then addressed valuation of related-party imports of services where the recipient has full input tax credit.

How High Courts have applied these clarifications

In Metal One Corporation India Pvt. Ltd. v. Union of India, decided by the Delhi High Court on 22 October 2024, the Court applied the second proviso to Rule 28(1) of the CGST Rules and the Circular, holding that where no invoice is raised and the Indian company has full credit, the value of the related-party service may be treated as nil. In Alstom Transport India Ltd., decided by the Karnataka High Court on 15 July 2025, expatriates on the Indian payroll and under the Indian entity’s control were held to be employees, so the arrangement fell outside supply under Schedule III; the Court added that even if a supply existed, the absence of an invoice meant a nil value under the Circular. In Huawei Technologies India Pvt. Ltd., reported in February 2026, the Karnataka High Court quashed a notice on similar reasoning that the individuals were employed directly.

These are decisions on their own records, and the Revenue can still rely on Northern Operating Systems where the overseas entity retains control, a mark-up is charged, or the employment is in substance with the foreign company. They show, however, that courts examine the employment documents and the payroll flow closely.

A practical evidence checklist and common mistakes

A useful file contains, for each individual: the secondment or assignment agreement; the Indian appointment letter and any foreign contract; visa and work permit sponsor; the reporting line and performance records kept in India; the entity with disciplinary and termination rights; payroll and income-tax withholding records (for example Form 16 and Form 12BA); social security and insurance arrangements; and the intercompany recharge schedule with the basis of computation and any mark-up. These should be reconciled to the general ledger and bank statements, and the department’s allegation should be set against each document in a separate column.

Common mistakes are quoting the judgment without the employee-wise facts, calling every recharge a reimbursement without testing for a mark-up or a management fee, asserting full input tax credit without checking blocked or exempt-use credits, running the primary and alternative arguments together so that one reads as a concession of the other, and conceding suppression because a different legal characterisation was adopted. The evidence should be assembled while the arrangement is running; a reconstruction created after the notice carries less weight.

Conclusion

Secondment disputes are decided by their commercial and employment facts. The Supreme Court decision supplies important guidance, while the CBIC instruction and valuation circular define how officers should approach particular questions in the GST framework.

A credible defence separates the threshold supply question from related-party valuation and builds both positions from documents that existed during the arrangement.

Frequently asked questions

1. Does Northern Operating Systems make every secondment taxable?

No. The facts and statute relevant to the actual secondment must be examined.

2. Is a payroll recharge always consideration for a service?

No universal conclusion follows from recharge alone; contractual and functional substance matter.

3. What is the importance of CBIC Instruction 05/2023?

It directs attention to the proper assessment of the judgment and facts rather than an indiscriminate approach.

4. Does Circular 210/4/2024 resolve secondment characterisation?

No. It addresses related-party import-of-service valuation in the circumstances covered by the circular.

5. Can full input tax credit be assumed merely because the recipient is registered?

No. Actual full-credit eligibility must be established under the governing provisions.

6. Is GST payable on salary reimbursed to a foreign parent for seconded employees?

Not automatically. If the individuals are in substance employees of the Indian entity, their services fall under Schedule III of the CGST Act and are not a supply. If the overseas company supplies manpower, an import of services may arise. Where it does, Circular 210/4/2024-GST may allow a nil value if no invoice is issued and full input tax credit is available.

7. What did the Karnataka High Court hold in Alstom Transport India on secondment?

On 15 July 2025, in W.P. 1779 of 2025, the Karnataka High Court quashed a GST demand on expatriate secondment, holding that employees on the Indian payroll and under the Indian entity’s control were in an employment relationship outside supply, and that even if a supply existed the value was nil under Circular 210/4/2024-GST. The reasoning is specific to its facts.

8. Can the extended limitation period be invoked in secondment cases?

Not merely because GST was not paid. CBIC Instruction No. 05/2023-GST states that section 74(1) of the CGST Act applies only where there is fraud, wilful misstatement or suppression of facts to evade tax, and that the evidence must be set out in the show cause notice. The facts of each case, including disclosure in audited accounts, remain relevant.

9. Does Circular 210/4/2024-GST apply to all secondment arrangements?

No. It deals with the valuation of an import of services between related persons, and does not mention secondment. It applies only after a supply from a foreign related person is established, and only where the Indian recipient is eligible for full input tax credit. Whether the secondment is a supply at all is decided first, on the employment facts.

Talk to SBC’s tax team

If a show cause notice or audit query treats seconded or expatriate staff as a supply of manpower, a review of the employment documents and the payroll flow against the points above is a sensible starting point. Our GST team can discuss the facts of your arrangement. Explore our GST services | Contact SBC

Disclaimer

This article is general professional commentary and not advice on any particular facts. Applicable law, procedural requirements, circulars and statutory amendments must be verified for the relevant tax period. It is not a description of an identifiable client engagement.
CategoriesGST

The 180-Day Payment Condition: Why an ERP Clearing Date Is Not a Payment Date

The 180-Day Payment Condition: Why an ERP Clearing Date Is Not a Payment Date

By CA Rajesh Vaishnav, Partner and CA Mithilesh Sai Sannareddy, Founder and CEO, Steadfast Business Consulting LLP | Indirect Tax Litigation / Controversy

Quick answer

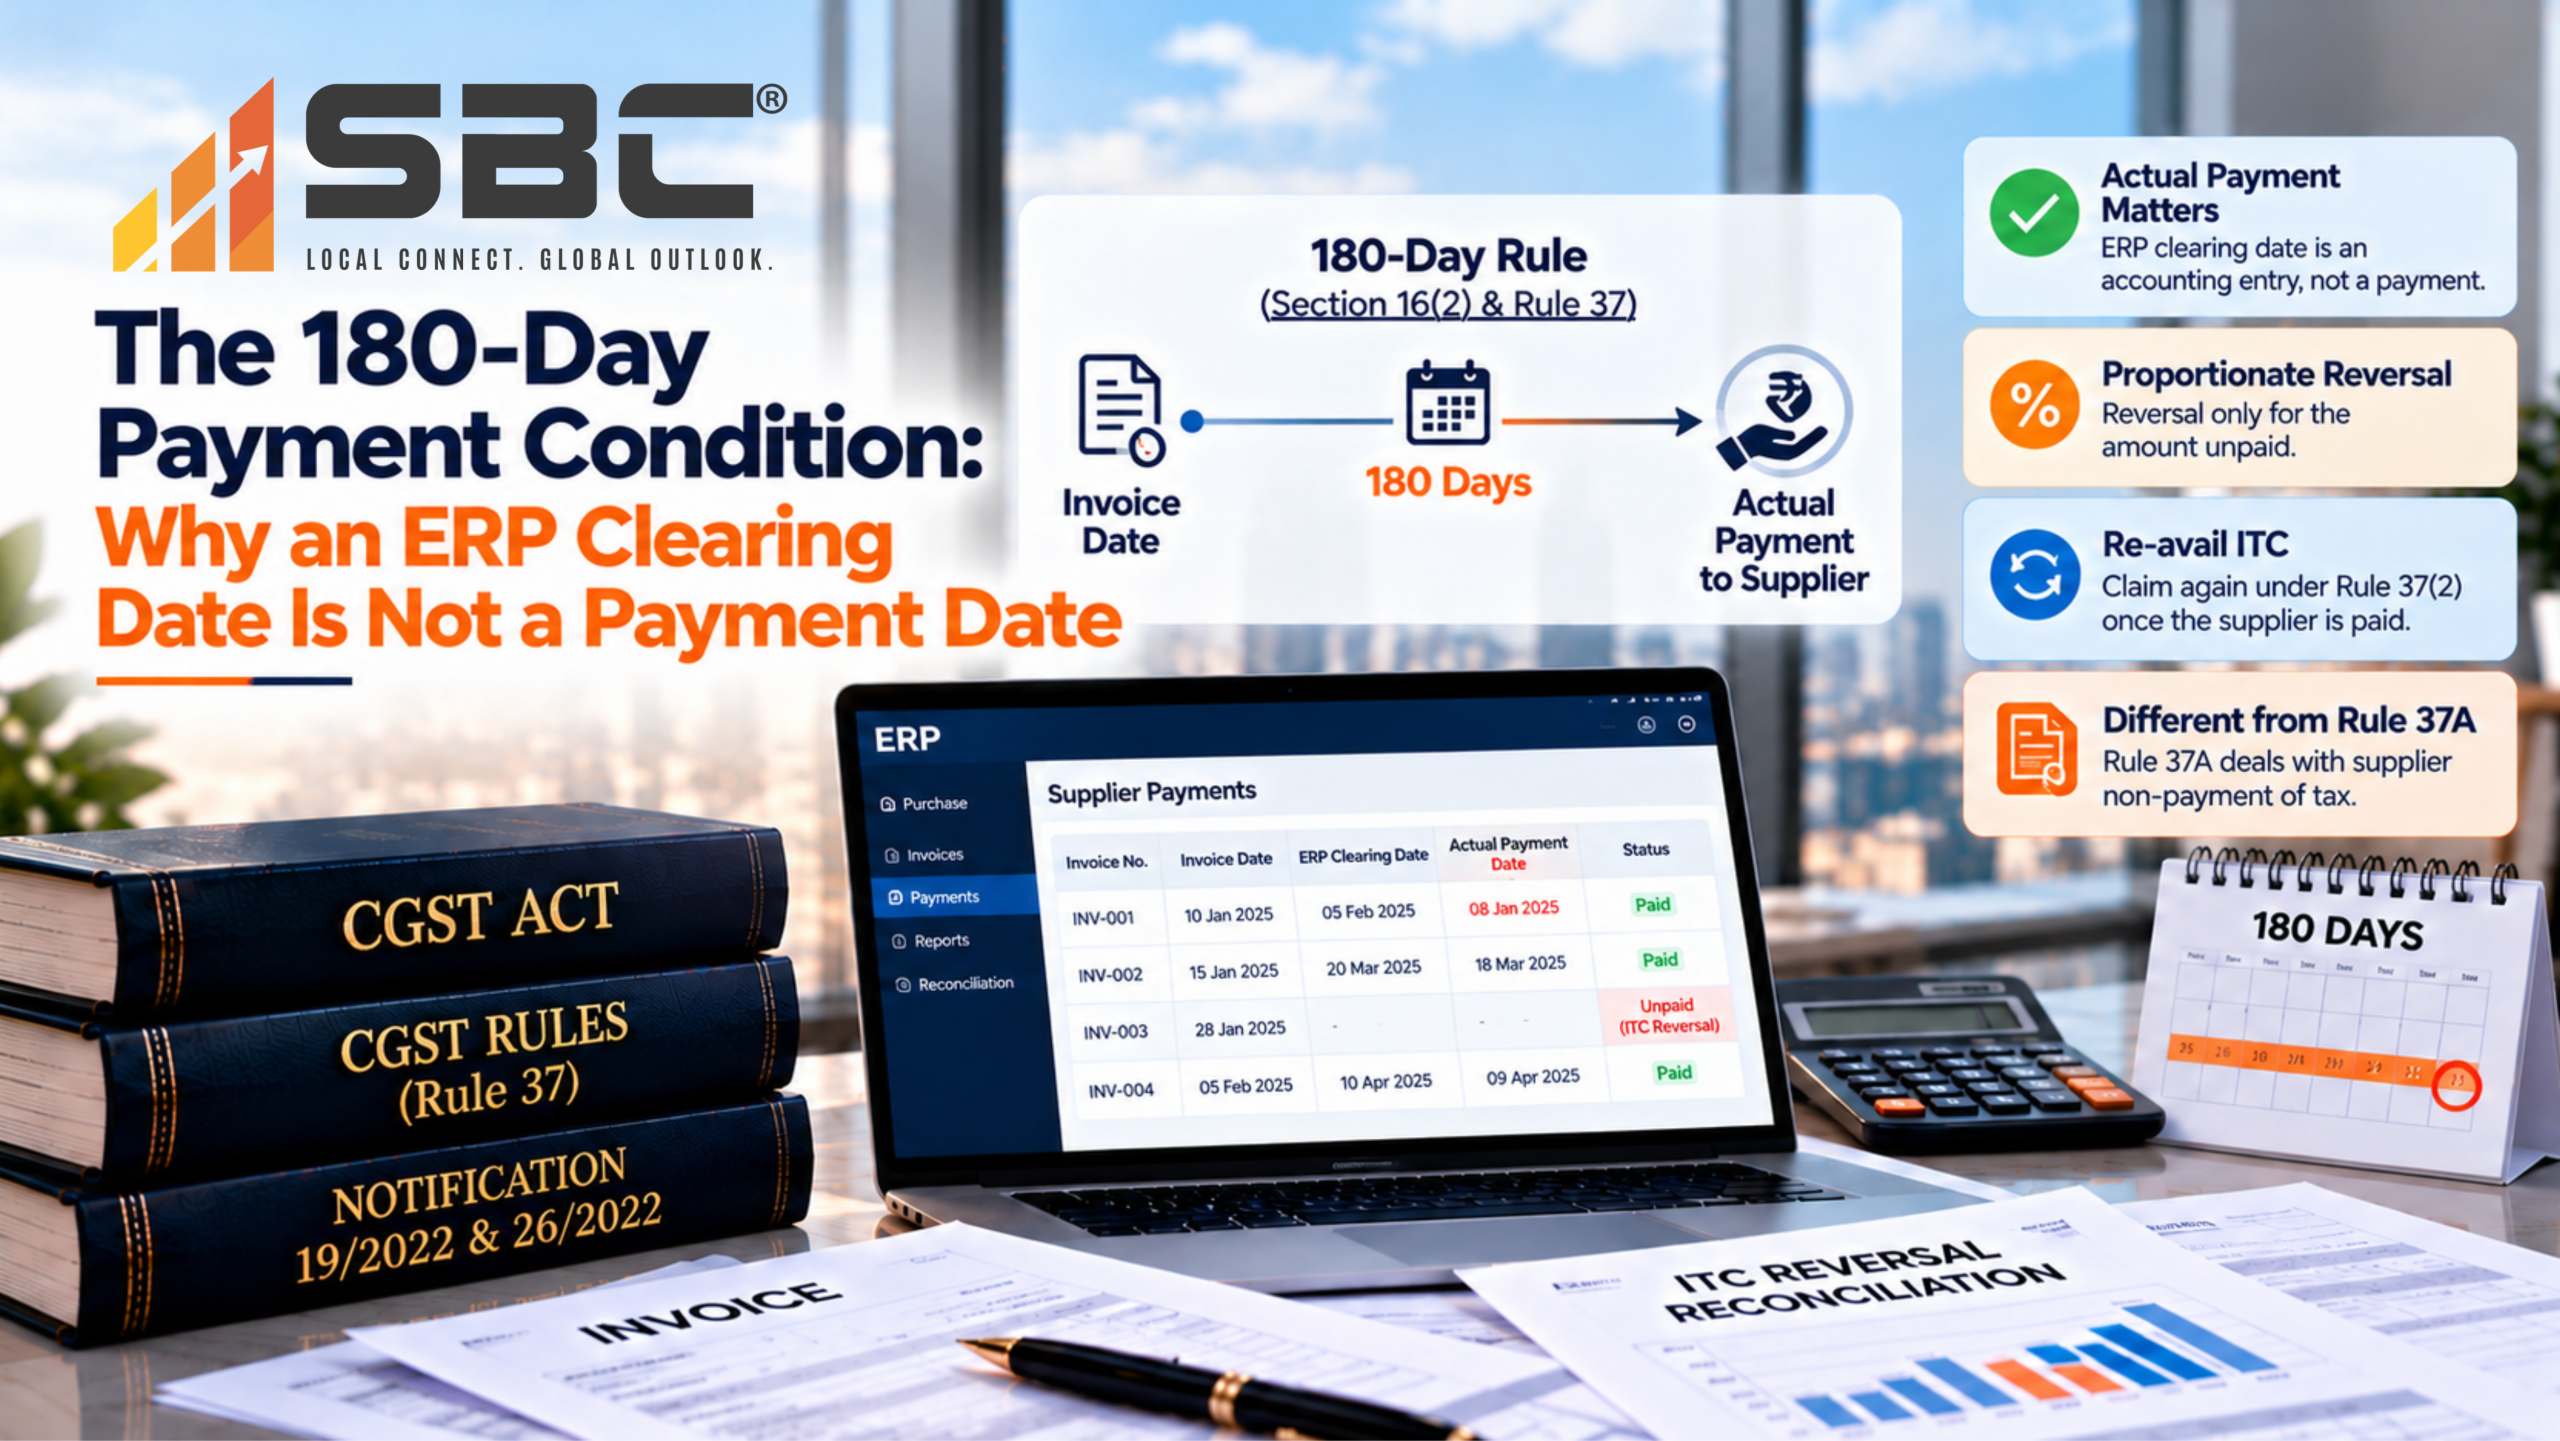
Rule 37 of the CGST Rules requires reversal of input tax credit, proportionate to the amount unpaid, only where the recipient has not actually paid the supplier within 180 days of the invoice date (second proviso to section 16(2)). An ERP clearing date is an accounting entry, not proof of non-payment; the invoice-level settlement evidence, including banking records where applicable, decides the question.

Key takeaways

  • Rule 37 of the CGST Rules requires reversal of input tax credit only where the recipient has failed to pay the supplier the value and tax within 180 days of the invoice date; an accounting entry is not that failure.
  • Since 1 October 2022 the reversal is proportionate to the amount unpaid (Notification No. 19/2022-Central Tax and No. 26/2022-Central Tax), and the credit can be re-availed under Rule 37(2) once the supplier is paid.
  • Reverse charge supplies, supplies without consideration under Schedule I and amounts added to value under section 15(2)(b) are outside the reversal.
  • The practical answer to an ERP-driven allegation is an invoice-level reconciliation of the department’s own list to bank value dates, with a systems note explaining how clearing dates were generated.
  • Rule 37 is different from Rule 37A, which deals with ITC where the supplier has not paid tax to the government, and the 180-day condition is itself under constitutional challenge in the Gujarat High Court.

Practice illustration: An ERP clearing date was mistaken for a payment date

Issue. A GST audit used accounting-system entries to infer delay in settlement of supplier invoices.

Approach. The response reconciled invoices, supplier accounts, banking records and system-migration entries against the 180-day statutory condition.

Reported position or outcome. The broader audit closed without a show cause notice, subject to a limited adjustment. This article addresses the Rule 37 question only, not every allegation considered in that audit.

Practical lesson. The evidence must establish actual payment rather than reliance on a single system field.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

Input tax credit under GST is conditional. One of the conditions is commercial rather than documentary: the recipient must actually pay the supplier, and must do so within a prescribed period running from the invoice date. If it does not, the credit attributable to the unpaid amount has to be reversed, with interest, and re-availed only when payment is eventually made. The condition exists to prevent credit being taken on invoices that are never settled.

The allegation that the condition has been breached has become a standard audit finding, and it is almost always a data problem rather than a compliance failure. It surfaces most often after an enterprise system migration, when historical payments are carried across with system generated dates that bear no relationship to the underlying bank transactions. The answer is an invoice level reconciliation against bank records, and a submission that makes the statutory point explicitly rather than assuming it.

This note deals with the audit allegation that now arises most often under that condition, which is not that a supplier went unpaid but that the taxpayer’s own accounting records appear to say so. It covers the statutory condition and the current text of the rule, why an accounting clearing date is not evidence of payment, the invoice level reconciliation that answers the allegation, the partial payment and retention cases where a genuine exposure does arise, the interest computation, and the controls that prevent the issue arising at all.

1. The statutory condition

The second proviso to section 16(2) of the CGST Act provides:

Provided further that where a recipient fails to pay to the supplier of goods or services or both, other than the supplies on which tax is payable on reverse charge basis, the amount towards the value of supply along with tax payable thereon within a period of one hundred and eighty days from the date of issue of invoice by the supplier, an amount equal to the input tax credit availed by the recipient shall be paid by him along with interest payable under section 50, in such manner as may be prescribed:

The closing words were substituted by the Finance Act 2023 with effect from 1 October 2023, replacing the earlier formulation under which the amount was added to the recipient’s output tax liability. The third proviso preserves the right to re-avail the credit on subsequent payment, and the words “to the supplier” were inserted into it by the same Act from the same date.

Three features of the proviso decide most disputes. The trigger is a failure to pay to the supplier, which is a factual question about money. The period runs from the date of issue of the invoice, not from the accounting date or the goods receipt date. And reverse charge supplies are expressly outside the condition.

2. The current text of Rule 37

Rule 37 was substituted by Notification No. 19/2022-Central Tax dated 28 September 2022, with effect from 1 October 2022. It was further amended by Notification No. 26/2022-Central Tax, which is dated 26 December 2022 but also takes effect from 1 October 2022. Sub-rule (3) was omitted. The current text provides:

(1) A registered person, who has availed of input tax credit on any inward supply of goods or services or both, other than the supplies on which tax is payable on reverse charge basis, but fails to pay to the supplier thereof, whether wholly or partly, the amount towards the value of such supply along with the tax payable thereon, within the time limit specified in the second proviso to sub-section (2) of section 16, shall pay or reverse an amount equal to the input tax credit availed in respect of such supply proportionate to the amount not paid to the supplier, along with interest payable thereon under section 50, while furnishing the return in FORM GSTR-3B for the tax period immediately following the period of one hundred and eighty days from the date of the issue of the invoice:

Provided that the value of supplies made without consideration as specified in Schedule I of the said Act shall be deemed to have been paid for the purposes of the second proviso to sub-section (2) of section 16:

Provided further that the value of supplies on account of any amount added in accordance with the provisions of clause (b) of sub-section (2) of section 15 shall be deemed to have been paid for the purposes of the second proviso to sub-section (2) of section 16:

(2) Where the said registered person subsequently makes the payment of the amount towards the value of such supply along with tax payable thereon to the supplier thereof, he shall be entitled to re-avail the input tax credit referred to in sub-rule (1).

(4) The time limit specified in sub-section (4) of section 16 shall not apply to a claim for re-availing of any credit, in accordance with the provisions of the Act or the provisions of this Chapter, that had been reversed earlier.

The emphasis in sub-rule (1) is added. The words “whether wholly or partly”, “or reverse” and “proportionate to the amount not paid to the supplier” were inserted by Notification No. 26/2022-Central Tax, and they are the words that convert the reversal from an all or nothing consequence into a proportionate one.

The 2022 substitution made two changes that matter in practice. Reversal is now proportionate to the unpaid value rather than of the whole credit on the invoice, which is significant where an invoice is partly settled or partly in dispute. And the amount is paid directly rather than added to output tax liability, which affects how it is reported and reconciled.

The two provisos are worth noting because they are routinely forgotten. Supplies made without consideration under Schedule I are deemed paid, which disposes of the question for related party supplies made without a payment. So are amounts added to value under section 15(2)(b), which covers amounts the recipient was liable to pay that were incurred by the supplier.

3. Why an ERP clearing date is not a payment date

The allegation in a typical audit runs as follows. The department extracts payment dates from the taxpayer’s system, compares them against invoice dates, identifies invoices where the gap exceeds the prescribed period, and proposes reversal of the credit on those invoices with interest across several years.

The flaw is in the first step. A clearing date in an enterprise system records when an accounting entry was posted or cleared, which is a book-keeping event. It is affected by the posting calendar, by batch processing, by period end procedures and, most dramatically, by a system migration in which historical transactions are loaded with the migration date or with a default. None of those is the date the supplier was paid.

The statutory condition is not drafted by reference to anything in the recipient’s accounting system. It asks whether the recipient failed to pay. Payment is a transfer of funds, and it is evidenced by the bank. Where bank records show that the supplier received the money within the period, the condition is not satisfied and no reversal arises, whatever the ledger says.

Framed that way, the dispute becomes evidential rather than legal, and the taxpayer holds the better evidence.

4. The reconciliation

The reconciliation has to be at invoice level. A summary comparison of aggregate payables against aggregate payments does not answer an allegation made invoice by invoice, and offering one invites the response that the taxpayer has not addressed the specific transactions identified.

The working should link, for each invoice in the department’s list:

  1. The supplier invoice, with its number, date and value, and the tax charged.
  2. The entry in the vendor ledger, with the system clearing date that the department has relied on.
  3. The bank statement line showing the outward remittance, with its value date.
  4. The payment advice or remittance reference tying the bank line to the invoice.
  5. The computed interval between the invoice date and the bank value date, and whether it falls within the period.
  6. Where a payment covered several invoices, the allocation applied and its basis.

Two supporting documents materially strengthen the submission. A short note from the systems team explaining how clearing dates were generated during the migration, with an illustration, converts the explanation from an assertion into a documented account of what happened. And a sample of supplier confirmations, acknowledging receipt on the dates claimed, corroborates the bank evidence from the other side of the transaction.

5. The partial payment and disputed invoice cases

Since the 2022 substitution, reversal is proportionate to the unpaid value. That matters in two common situations.

Retention and holdback. Where a contract provides for a retention released on completion or after a defect liability period, the retained amount is unpaid within the meaning of the proviso until it is released. The credit attributable to the retained portion is reversible, and it is re-availed on release under Rule 37(2). The right answer is to track retentions as a class and reverse proportionately rather than to argue that the whole invoice is paid.

Disputed amounts. Where part of an invoice is withheld pending resolution of a dispute, the same analysis applies to the withheld portion. A credit note issued by the supplier is a different matter, because it reduces the value of the supply rather than leaving it unpaid, and the treatment follows the credit note provisions instead.

In both cases the position should be computed and disclosed rather than left for an auditor to find. A taxpayer who has reversed proportionately on retentions, voluntarily and with workings, is in a very different position from one who has not considered the question.

6. A worked example

A manufacturer migrates its enterprise system during a financial year. In a departmental audit covering four years, the officers extract vendor clearing dates, identify a population of invoices where the interval from invoice date to clearing date exceeds the prescribed period, and propose reversal across all four years with interest.

Step one. Obtain the department’s working, invoice by invoice. A reconciliation cannot be built against an allegation stated in aggregate.

Step two. For each invoice, extract the bank value date and the remittance reference. Where the payment was made by a batch run covering multiple invoices, obtain the batch detail and the allocation.

Step three. Build the reconciliation table, showing the clearing date, the bank value date and the interval on each basis. The pattern that usually emerges is that the clearing dates cluster around the migration date while the bank dates are spread normally, which is itself persuasive.

Step four. Prepare the systems note explaining how the clearing dates were generated, with one worked illustration traced end to end.

Step five. Make the statutory argument explicitly. The proviso and Rule 37(1) are triggered by a failure to pay. Payment is evidenced by the bank. An accounting date that does not correspond to the transfer of funds is not evidence of non payment.

Step six. Identify any invoices that genuinely were paid late, compute the proportionate reversal with interest, and disclose it. A submission that concedes the small true exposure is considerably more persuasive on the rest than one that contests everything.

7. Interest, which is often the larger number

Where a reversal is genuinely due, the interest can exceed the tax, because the period runs from the date the credit should have been reversed to the date it is paid, and audits reach back several years.

Three points are worth making in any submission that concedes part of the population. The interest runs under section 50, and the rate and the period should be computed rather than accepted as stated in the notice, because departmental computations frequently run interest from the invoice date rather than from the end of the period in which the reversal fell due. Where credit has been re-availed on subsequent payment, interest runs only for the intervening period and not beyond, and a computation that ignores re-availment overstates the liability. And where the reversal is proportionate, the interest is proportionate too, which a computation built on the full invoice value will miss.

It is worth preparing the taxpayer’s own interest computation and putting it in the submission rather than contesting the department’s in the abstract. A notice that proposes tax and interest, met by a response that concedes a small tax figure with a worked interest computation attached, is very often closed at that stage.

8. Credit notes, which are a different question

A reduction in the amount payable is not always a failure to pay, and the distinction decides which provision applies.

Where the supplier issues a credit note reducing the value of the supply, the value itself falls. There is no unpaid amount to trigger the proviso, and the consequences follow the credit note provisions instead, including the requirement that the recipient reverse the corresponding credit. Where the recipient simply withholds part of the invoice without a credit note, the value is unchanged and the withheld portion is unpaid, so the proportionate reversal applies.

The practical problem is that commercial teams often treat a disputed invoice and a credit noted invoice as the same thing, and the accounting may not distinguish them. A response that applies the wrong provision to either category invites a correction on a point the taxpayer could have got right.

9. What the department is working from

It helps to understand the shape of the extraction, because it explains both the allegation and the answer.

The typical working is built from two tables: the purchase register or vendor ledger, and a payments extract. The invoice date comes from the first, the payment date from the second, and the interval is computed between them. Nothing in that process looks at a bank statement, and nothing in it distinguishes a posting date from a value date.

That has two consequences for the response. The first is that the error is systematic rather than random, so it will affect a whole class of transactions in a recognisable pattern, and demonstrating the pattern is more persuasive than contesting invoices one at a time. The second is that the department’s own extract is the right starting point: asking for it, reconciling against it line by line, and returning it with two additional columns showing the bank value date and the corrected interval is far more effective than submitting a reconciliation built on the taxpayer’s own schedule, which the officer then has to map back to the allegation.

10. Where these responses go wrong

First, the response is a legal argument without a reconciliation. The point is correct and the officer will not accept it unsupported.

Second, the reconciliation is at summary level. It must be at invoice level and it must address the department’s own list.

Third, the taxpayer contests the entire population. Where some invoices were genuinely paid late, contesting them costs credibility on the rest.

Fourth, retentions are not considered. This is the most common genuine exposure in the area, and a response that does not address retentions leaves an open flank.

Fifth, reverse charge supplies are included in the population. They are expressly excluded by the proviso and by Rule 37(1), and their presence in the department’s list should be pointed out.

Sixth, the Schedule I and section 15(2)(b) provisos are overlooked, with the result that related party supplies made without consideration are treated as unpaid.

Seventh, re-availment is not tracked. Where credit has been reversed and the supplier is later paid, the credit is re-available under Rule 37(2), and a taxpayer that reverses without tracking re-availment pays twice. Rule 37(4) is important here and is frequently overlooked: the time limit in section 16(4) does not apply to a claim for re-availing credit that was reversed earlier, so a reversal made in an earlier year does not become irrecoverable merely because the ordinary time limit for taking credit has passed.

11. Preventing the allegation

The exposure is systemic and so is the fix. Three controls remove most of it.

An ageing report run on invoice date. Most payables ageing is run on due date or on posting date. A report run on invoice date, flagging invoices approaching the prescribed period, identifies the exposure before it crystallises.

A documented mapping between the bank and the ledger. Where the enterprise system holds a payment date field that is populated from the bank rather than from the posting run, the entire dispute disappears. Where it does not, the reconciliation should be maintained as a standing control rather than built under audit pressure.

A retention register. Retentions tracked as a class, with proportionate reversal and scheduled re-availment, convert the single largest genuine exposure into a routine computation.

Where a system migration is planned, the treatment of historical payment dates should be specified as a requirement before the migration rather than discovered afterwards. The cost of specifying it is trivial. The cost of reconstructing four years of payment dates under audit is not.

Practitioner’s perspective

This issue illustrates something broader about how GST audits are now conducted. The department works from extracted data, and the data it extracts is the data the taxpayer’s system happens to hold. Where a field means something different from what its name suggests, the extraction produces a false positive, and the burden of explaining it falls on the taxpayer.

On the statutory construction there is little room for argument. Rule 37 and the second proviso to section 16(2) are triggered by a failure to pay the supplier, and a clearing date is not a payment. What makes the difference between a response that closes the issue at audit stage and one that proceeds to a show cause notice is whether the reconciliation exists and whether it is at the right level of granularity.

For businesses with large payable populations, the right investment is in the controls rather than in the defence. An ageing report on invoice date and a documented bank to ledger mapping cost very little and remove the issue entirely. For businesses already facing the allegation, concede the genuine late payments, compute the proportionate reversal, and contest the rest on evidence.

Rule 37A and the pending challenge to the 180-day condition

Rule 37 should not be confused with Rule 37A. Rule 37 deals with the recipient’s own failure to pay the supplier within 180 days. Rule 37A was inserted by Notification No. 26/2022-Central Tax dated 26 December 2022, following the 48th GST Council meeting, and deals with a different default: where the recipient has taken credit but the supplier has not furnished the return in Form GSTR-3B for the corresponding period by 30 September following the end of the financial year, the credit must be reversed, through Form GSTR-3B, on or before 30 November following the end of that financial year, with interest under section 50. It first applied to financial year 2022-23. The credit can be re-availed if the supplier later files the return. The two rules have different triggers, evidence and timelines, and a notice that cites one should be checked against the facts of the other.

Two further developments are worth tracking. First, the 180-day condition in the second and third provisos to section 16(2) is under constitutional challenge before the Gujarat High Court in Priya Blue Industries v. Union of India, in which notice was reported in November 2025; no stay of the provisos was reported, so the provisions and Rule 37 continue to apply and should be complied with. Any later amendment must be checked for the actual tax period involved; an ongoing constitutional challenge by itself does not suspend the statutory obligation.

Appeals against an adjudication order that confirms a Rule 37 demand lie first to the first appellate authority under section 107 of the CGST Act and then to the GST Appellate Tribunal under section 112. The Tribunal was launched on 24 September 2025 and, per commentary, began hearing cases on 16 February 2026, with benches being added through 2026. The pre-deposit and time limits for each stage should be confirmed from the statute and the GSTAT portal at the time of filing.

Conclusion

The test for Rule 37 is payment and the supporting records, not the ERP clearing field. A defensible response reconciles each invoice and distinguishes genuine overdue payments from migration or posting artefacts.

Frequently asked questions

1. What triggers reversal under Rule 37?

A failure to pay the supplier the value of the supply together with the tax within the period specified in the second proviso to section 16(2), being one hundred and eighty days from the date of issue of the invoice. Supplies on which tax is payable under reverse charge are excluded.

2. Is the reversal of the whole credit or only part?

Proportionate. Rule 37(1) requires payment or reversal of the credit availed on the supply proportionate to the amount not paid to the supplier, following the amendments that took effect from 1 October 2022. It is no longer an all or nothing reversal of the credit on the whole invoice.

3. From what date does the period run?

From the date of issue of the invoice by the supplier. Not from the goods receipt date, the accounting date or the due date under the contract.

4. Is an ERP clearing date evidence of the payment date?

No. A clearing date records an accounting event. The statutory condition looks to whether the recipient paid the supplier, which is evidenced by the bank. Where bank records show payment within the period, no reversal arises.

5. How should the reversal be reported?

Rule 37(1) requires the amount to be paid along with interest under section 50 while furnishing the return in Form GSTR-3B for the tax period immediately following the one hundred and eighty day period. Since the Finance Act 2023 amendment effective 1 October 2023 the amount is paid rather than added to output tax liability.

6. Can the credit be taken back if the supplier is paid later?

Yes. Rule 37(2) entitles the recipient to re-avail the credit on subsequently making payment of the value together with the tax to the supplier, and the third proviso to section 16(2) preserves that right. Rule 37(4) provides that the time limit in section 16(4) does not apply to a claim for re-availing credit reversed earlier.

7. How are retentions treated?

A retained amount is unpaid until released, so the credit attributable to it is reversible proportionately and re-availed on release. Retentions should be tracked as a class and reversed voluntarily with workings.

8. Do related party supplies made without consideration attract reversal?

No. The first proviso to Rule 37(1) deems supplies made without consideration as specified in Schedule I to have been paid for the purposes of the second proviso to section 16(2).

9. What about amounts the supplier incurred that the recipient was liable to pay?

The second proviso to Rule 37(1) deems amounts added to value under section 15(2)(b) to have been paid, so they do not trigger reversal.

10. What controls prevent this becoming an audit issue?

A payables ageing report run on invoice date, a documented mapping between the bank and the ledger so that the system holds a true payment date, and a retention register with scheduled re-availment.

11. What is the difference between Rule 37 and Rule 37A of the CGST Rules?

Rule 37 requires the recipient to reverse input tax credit if it has not paid the supplier within 180 days of the invoice. Rule 37A requires reversal where the supplier has not filed its GSTR-3B for the period by 30 September following the financial year. Both allow re-availment once the default is cured, but their triggers and evidence differ.

12. What interest is payable when ITC is reversed under Rule 37?

Rule 37(1) requires the reversal to be made along with interest under section 50 of the CGST Act. The rule does not state the start date or the rate, and commentary is divided on whether 18 per cent under section 50(1) or 24 per cent under section 50(3) applies. The computation should be worked out and disclosed rather than accepted from a notice without checking.

13. Is the 180-day rule for ITC under challenge in any High Court?

Yes. The Gujarat High Court issued notice in November 2025 in Priya Blue Industries v. Union of India on the second and third provisos to section 16(2) of the CGST Act. No stay was reported, so the provisions and Rule 37 remain in force. The current status of the petition should be confirmed before relying on it.

14. Does an ERP clearing date prove that a supplier was paid late for GST purposes?

No. The second proviso to section 16(2) asks whether the recipient paid the supplier within 180 days of the invoice date. A clearing date records when an accounting entry was posted, which can differ from the bank value date, especially after a system migration. An invoice-level reconciliation to bank statements answers the allegation.

Talk to SBC’s tax team

If a GST audit has proposed reversal of credit on supplier payments, the first step is usually to obtain the department’s invoice list and test it against bank records. Our GST team can walk through what the reconciliation should contain. Explore our GST services | Contact SBC

Disclaimer

This article is for general information and does not constitute professional advice. It reflects the law as understood at the date of publication and does not take account of later developments. Rule 37 was substituted with effect from 1 October 2022 and the second proviso to section 16(2) was amended with effect from 1 October 2023, so the applicable text depends on the period concerned. Outcomes turn on the specific facts and the documentary record. No reader should act on the basis of this article without taking advice on their own circumstances.

CategoriesGST

Intermediary or Principal? How Section 2(13) IGST Decides Zero Rating of Service Exports

Intermediary or Principal? How Section 2(13) IGST Decides Zero Rating of Service Exports

By CA Rajesh Vaishnav, Partner and CA Mithilesh Sai Sannareddy, Founder and CEO, Steadfast Business Consulting LLP | Indirect Tax Litigation / Controversy

Quick answer

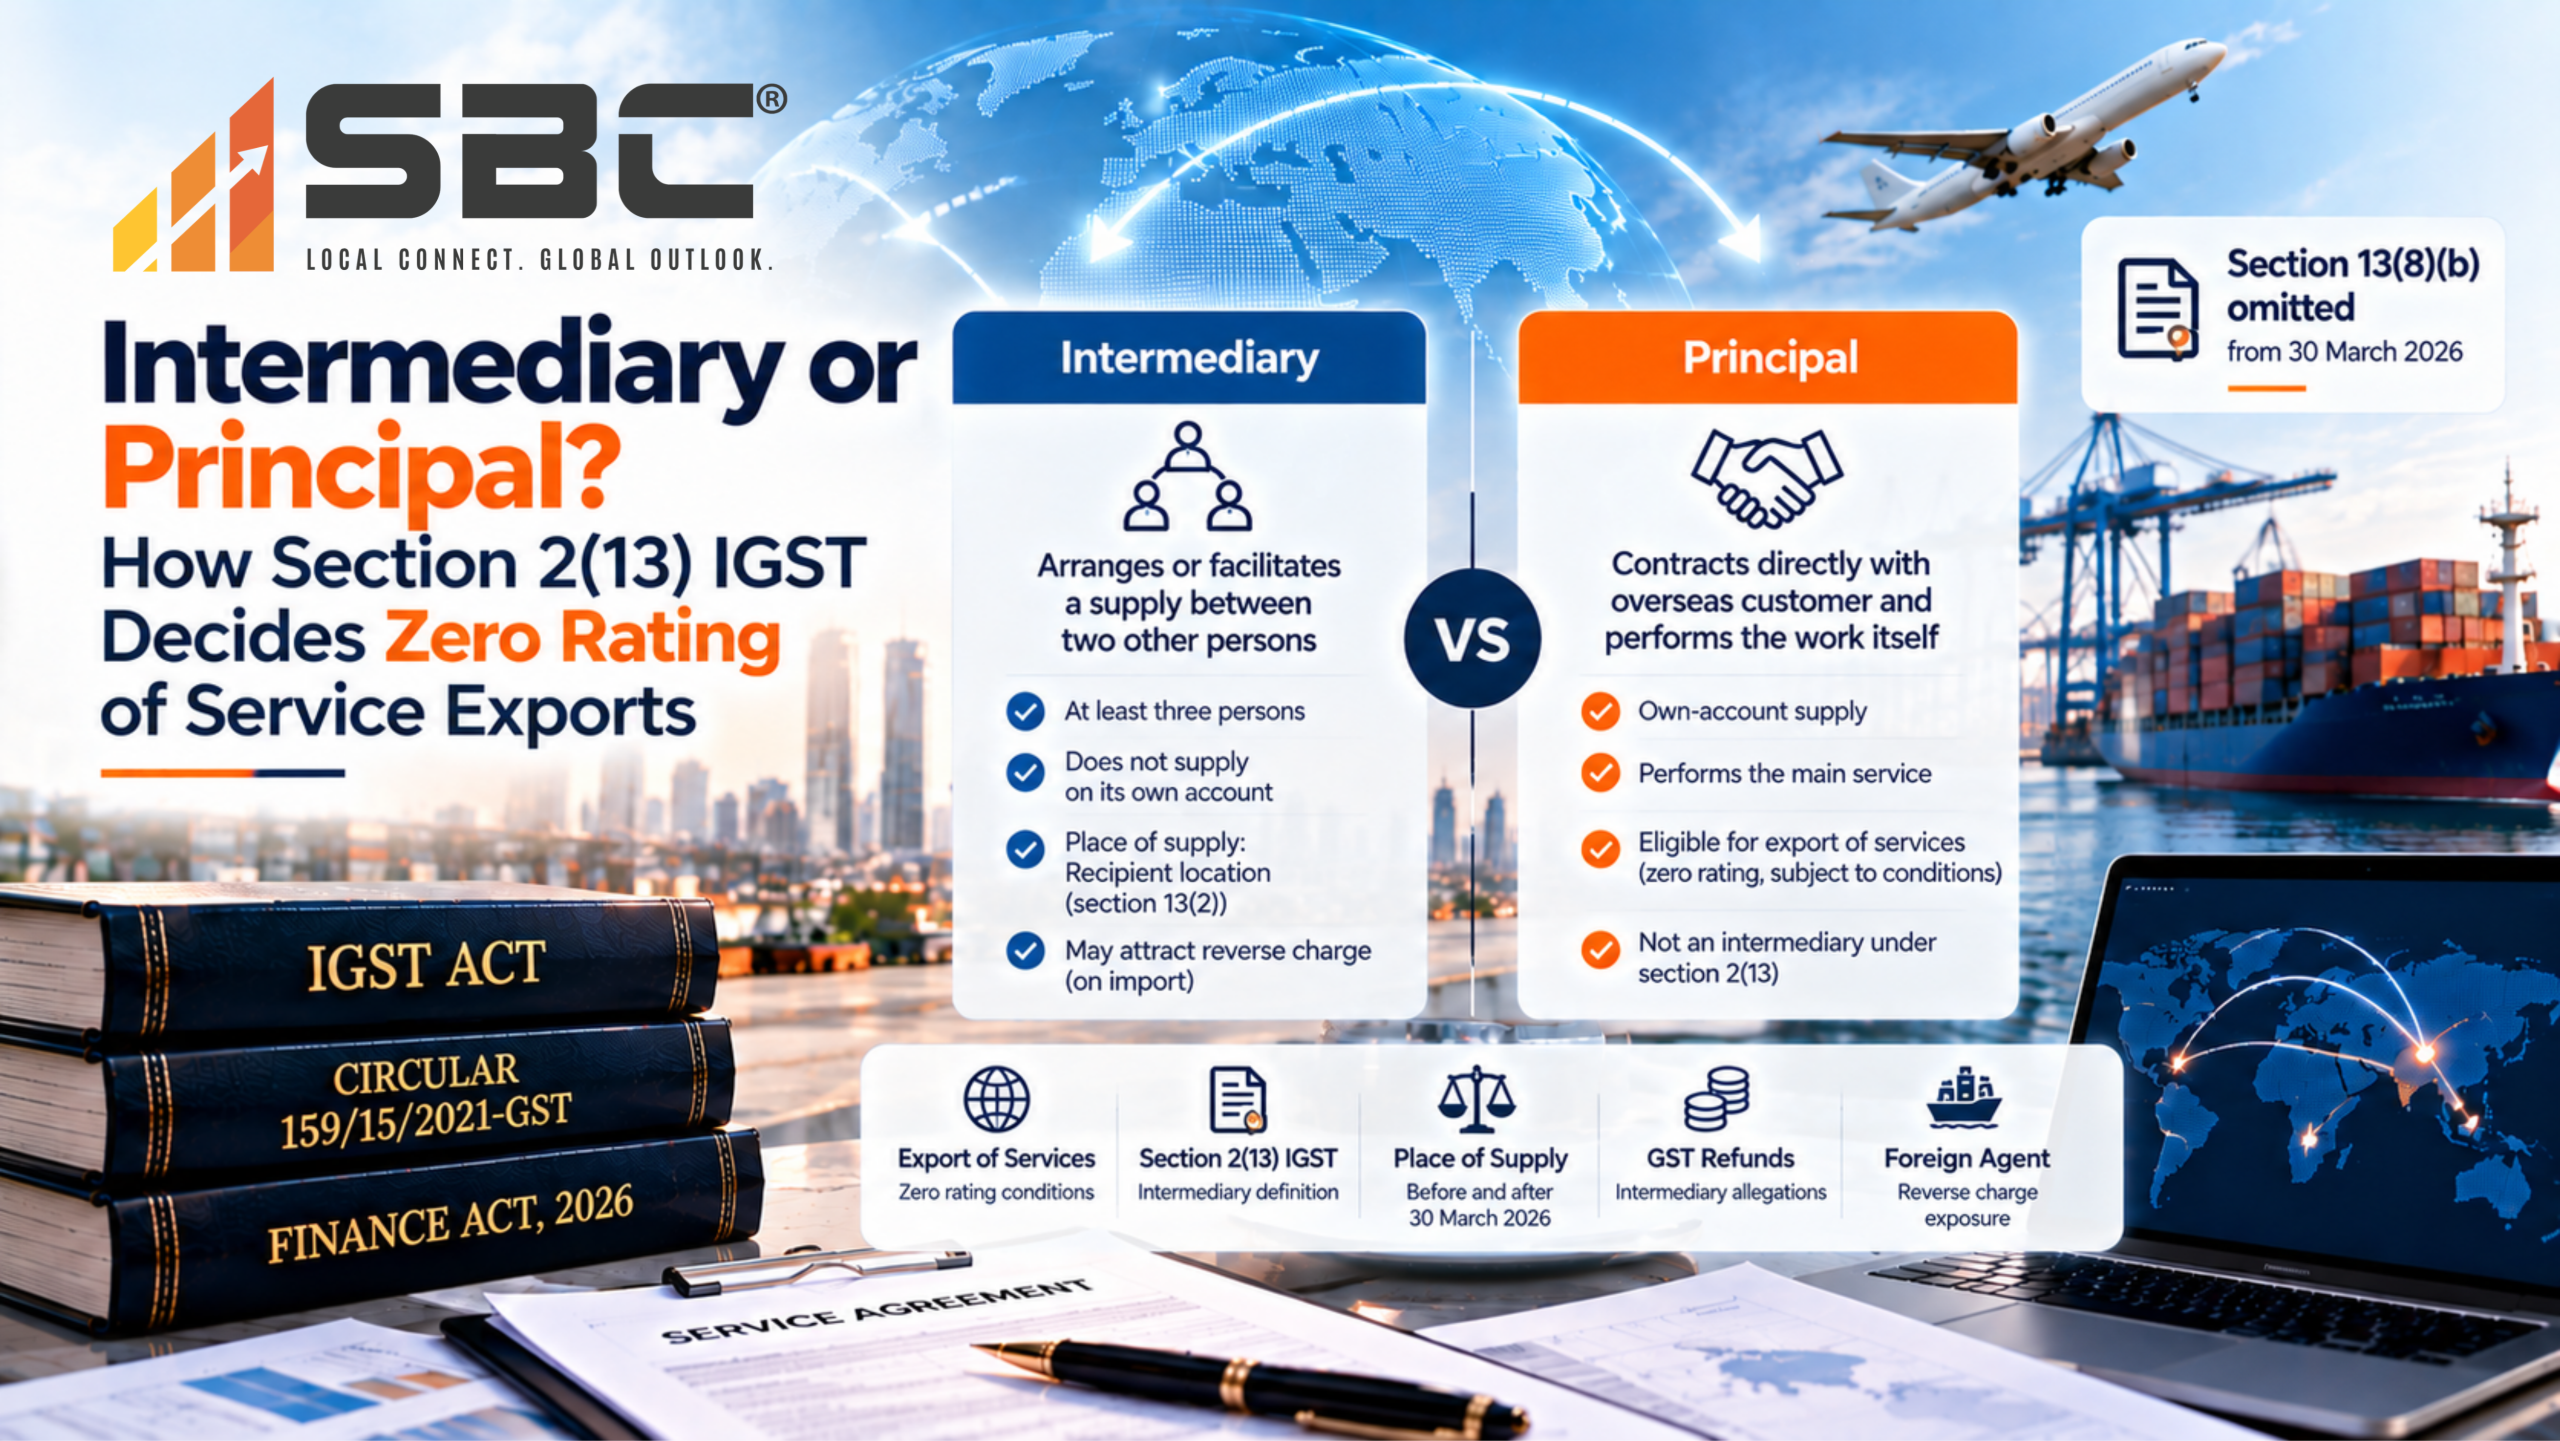
Under section 2(13) of the IGST Act, an intermediary arranges or facilitates a supply between two other persons and does not supply on its own account. A provider that contracts directly with an overseas customer and performs the work itself is a principal. Section 13(8)(b) was omitted from 30 March 2026, so earlier periods still turn on this classification.

Key takeaways

  • Section 2(13) of the IGST Act applies only where there are at least three persons, two distinct supplies, and a person who arranges the main supply between the other two without supplying it on its own account (Circular No. 159/15/2021-GST dated 20 September 2021).
  • A sub-contractor that performs the main service itself is not an intermediary, so working alongside other contractors on a customer’s project does not by itself create intermediary status.
  • Section 13(8)(b) of the IGST Act was omitted by section 157 of the Finance Act 2026, with effect, according to published commentary, from Presidential assent on 30 March 2026; intermediary services now follow the recipient-location rule in section 13(2).
  • For supplies before 30 March 2026 the classification remains decisive, and High Court decisions in 2025 and 2026 (Bombay, Delhi) have favoured exporters who supply on their own account to foreign recipients.
  • The omission creates an import-side exposure: a foreign agent or introducer supplying an Indian recipient now has its place of supply in India, so reverse charge may apply.

Practice illustration: Own-account service versus intermediary classification

Issue. A service exporter was challenged on whether it made its own supply or merely facilitated a transaction between others.

Approach. The defence distinguished the principal supply from any alleged facilitation, tested the contracts and applied the export-of-services conditions.

Reported position or outcome. The own-account service characterisation and related export position were preserved in the matter. The result is fact-specific and is not a precedent applying automatically to other arrangements.

Practical lesson. The distinct underlying supplies and the provider’s own obligations are decisive.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

An intermediary, in GST, is not simply a business that sits between two others. The term has a statutory definition, and the definition describes a particular commercial structure: a person who brings about a supply between two other parties while not making that supply itself. A great many businesses operate within a chain of parties without answering that description, and the distinction between facilitating someone else’s supply and making one’s own is the question on which the classification turns.

What turns on the classification is the whole of the export position. If it is sustained, the place of supply shifts, zero rating is denied, accumulated credit becomes unrefundable, and the exposure is retrospective across open periods. The defence is contractual and functional, and it is built before the refund application rather than after the objection.

This note deals with establishing the distinction for a service provider exporting to overseas customers. It covers the statutory definition, the five prerequisites the Board has set out, the contractual and functional evidence that establishes principal status, the export conditions that must independently be satisfied, and the change in the place of supply rule that alters the analysis for periods going forward while leaving earlier periods untouched. It also covers the new liability that change creates on the import side. For the related question of sourcing a supply connected with an overseas event, see our note on place of supply for events held outside India.

1. The definition

Section 2(13) of the IGST Act provides:

“intermediary” means a broker, an agent or any other person, by whatever name called, who arranges or facilitates the supply of goods or services or both, or securities, between two or more persons, but does not include a person who supplies such goods or services or both or securities on his own account;

The definition has not been amended since the Act came into force. Every word of the exclusion matters, and the exclusion is where most defences are won.

2. What the Board’s circular requires

Circular No. 159/15/2021-GST dated 20 September 2021 sets out the prerequisites for intermediary status, and it is the most useful single document in the area because it is the department’s own statement of the test.

  1. A minimum of three parties. Two principals transacting with each other, and the intermediary who arranges or facilitates that transaction. An arrangement between two parties cannot produce an intermediary.
  2. Two distinct supplies. The main supply between the two principals, and an identifiable ancillary supply of facilitation. Both must exist.
  3. The character of a broker or agent. The person must act in a subsidiary capacity in relation to the main supply, not as a party to it.
  4. No supply on one’s own account. A person supplying the main service on a principal to principal basis, in whole or in part, is excluded.
  5. Sub-contracting is expressly outside the definition. A sub-contractor who performs the main service is not an intermediary.

The fifth point is frequently decisive and frequently overlooked. A department that characterises a service provider as an intermediary because it works within a larger project, alongside contractors engaged by the customer, is characterising a sub-contractor, and the circular says in terms that a sub-contractor is not an intermediary.

3. Building the defence

The analysis is contractual first and functional second, and the two must agree.

Identify the parties and the supplies. The submission should state, in a short numbered passage, who the parties are, what each supplies to whom, and where the alleged main supply between two other persons is said to be. Very often this exercise alone disposes of the allegation, because the department has not identified a main supply at all. It has identified a service provider working in a complex environment and inferred facilitation from the complexity.

Show that the provider contracts on its own account. The evidence is the agreement: who the counterparty is, what obligations are assumed, what the deliverables are, who is liable for defective performance, who carries the risk of non performance, and how consideration is determined. A provider paid for its own output at its own price is not earning a facilitation fee.

Show that the provider performs the service. Resource deployment, personnel, methodology, the deliverables themselves. A person who arranges a supply does not produce the work product.

Address the pricing structure. Remuneration on a commission basis, or calculated as a percentage of the value of a transaction between two other parties, is an indicator of facilitation. A fee for the provider’s own services, computed on its own cost base or on a defined scope, is not.

Deal with the counter indicators directly. Where the provider coordinates with third party contractors, attends meetings on the customer’s behalf, or holds a role described in the agreement as coordination or liaison, those facts will be in the notice. They should be addressed and explained rather than left for the department to emphasise. Coordination performed as part of delivering one’s own scope is not facilitation of someone else’s supply.

4. The export conditions, which must also be satisfied

Defeating the intermediary allegation is necessary but not sufficient. Section 2(6) of the IGST Act defines export of services, and all five conditions must hold:

(i) the supplier of service is located in India; (ii) the recipient of service is located outside India; (iii) the place of supply of service is outside India; (iv) the payment for such service has been received by the supplier of service in convertible foreign exchange or in Indian rupees wherever permitted by the Reserve Bank of India; and (v) the supplier of service and the recipient of service are not merely establishments of a distinct person in accordance with Explanation 1 in section 8.

Two points on these. The words permitting receipt in Indian rupees were inserted by the IGST (Amendment) Act 2018 with effect from 1 February 2019, and Circular No. 202/14/2023-GST dated 27 October 2023 confirms that rupees received through a Special Rupee Vostro Account under the Reserve Bank’s framework satisfy the condition. The fifth condition is the one that catches captive arrangements: where the Indian supplier and the overseas recipient are merely establishments of the same person, the transaction is not an export however it is contracted.

Zero rating itself flows from section 16 of the IGST Act, and the structure of that provision changed with effect from 1 October 2023. Following the substitution of section 16(3) by the Finance Act 2021, the general route is supply under bond or letter of undertaking without payment of tax, with refund of unutilised credit under section 54 of the CGST Act. The route of paying tax and claiming refund is now available only to a class of persons or a class of goods or services notified under section 16(4) as amended by the Finance (No. 2) Act 2024. Section 16(5), inserted by the same Act, bars refund of unutilised credit or of tax paid on zero rated supply of goods subject to export duty. A submission that describes the two routes as freely interchangeable is describing the pre-2023 position.

5. The place of supply rule has changed

For the whole of the period in which this dispute has been litigated, section 13(8)(b) of the IGST Act placed the supply of intermediary services at the location of the supplier. That is what made the classification so consequential: an Indian provider held to be an intermediary had its place of supply in India, and the export fell away.

The constitutional challenge produced a divided answer. In Dharmendra M. Jani v. Union of India, Writ Petition No. 2031 of 2018, a Division Bench of the Bombay High Court delivered a split verdict, one judge holding the provision ultra vires and the other upholding it. On reference, the third judge held the provision valid and constitutional but confined in its operation to the IGST Act alone, so that it could not found a levy under the central and state legislation, and held that the petitioners’ transactions were exports under section 2(6).

The provision has since been omitted. Section 13(8)(b) was omitted by the Finance Act 2026. The consequence is that intermediary services fall to the default rule in section 13(2), under which the place of supply is the location of the recipient.

One point of detail should be settled against the gazette before any position is taken for supplies made in the early part of 2026. Published commentary treats the omission, made by section 157 of the Finance Act 2026, as effective from Presidential assent on 30 March 2026, because that section falls outside the commencement clauses of section 1(2) of the Act and carries no separate commencement date. The enacted text, and any later notification or clarification, should still be checked for supplies made around that date, particularly where an invoice or payment straddles 30 March 2026.

Three practical consequences follow, and they pull in different directions.

  • For periods from 30 March 2026, the classification question loses most of its force in the export context. A provider characterised as an intermediary, supplying an overseas recipient, now has its place of supply outside India under section 13(2) and the export analysis proceeds on the remaining conditions in section 2(6).
  • For earlier periods, nothing has changed. Open assessments, pending refund rejections and appeals for periods before the omission continue to be governed by section 13(8)(b), and the classification remains determinative. The omission is not expressed to be retrospective, and whether pending demands and refund rejections for earlier periods are affected remains open to argument before the forum concerned, so earlier periods should still be defended on the law as it stood.
  • The classification still matters for other purposes, including the identity of the person liable, documentation and the treatment of domestic arrangements. The definition in section 2(13) is unchanged.

There is a consequence running the other way, and for many Indian businesses it is the more important one. Because the place of supply for intermediary services now follows the general rule in section 13(2) and is the location of the recipient, a foreign intermediary supplying an Indian recipient now has its place of supply in India. That makes the supply an import of services, on which the Indian recipient is liable to discharge integrated tax under reverse charge, with credit available where the recipient is otherwise eligible.

Indian businesses that pay overseas agents, introducers, placement agents or similar facilitators should therefore review those arrangements. Under the previous rule those payments attracted no Indian tax because the place of supply was the overseas supplier’s location. A business that reads the omission only as relief for its own exports, and does not look at what it buys, may acquire a reverse charge liability it has not budgeted for.

6. A worked example

An Indian company supplies specialised infrastructure support services, including system design optimisation, operational performance monitoring and infrastructure planning, to overseas group companies running large projects abroad. It contracts directly with those companies, treats the supplies as exports and claims refund of accumulated credit. During scrutiny the department alleges that the company is an intermediary facilitating services between the overseas project developers and the engineering contractors working on those projects.

The three party test. The submission identifies the parties: the Indian company and the overseas recipient. It then asks the department to identify the main supply between two other persons that the Indian company is said to arrange. Where the department points to the relationship between the overseas developer and its contractors, the answer is that the Indian company is not a party to that relationship, does not arrange it, and is not remunerated by reference to it.

Own account. The agreement records a defined technical scope, deliverables, liability for defective performance and a fee for the Indian company’s own services. Those terms are inconsistent with a facilitation role.

Performance. Engineering personnel, methodology and the deliverables themselves establish that the company performs the service rather than procuring it from someone else.

Sub-contracting. Where the department’s real complaint is that the company works alongside other contractors on the customer’s project, Circular 159 answers it: a sub-contractor performing the main service is not an intermediary.

Export conditions. Each of the five conditions in section 2(6) is addressed separately, with the banking evidence for the consideration condition and the group structure addressed for the distinct person condition.

Period. The submission states the periods in issue and, where any fall after 30 March 2026, makes the further point that the place of supply would in any event be outside India under section 13(2).

7. Where these defences are weak

First, the agreement uses agency language. Words such as coordinate, liaise, facilitate, on behalf of and arrange appear in commercial drafting without anyone intending their legal consequence, and they are the first thing quoted in the notice.

Second, remuneration is commission based or linked to the value of a third party transaction. This is the single strongest indicator against the taxpayer and it is very difficult to explain away.

Third, the main supply is not identified and the taxpayer does not force the point. The burden of establishing the three party structure is on the department, and a submission that argues only about its own role concedes the frame.

Fourth, the export conditions are assumed rather than proved. Refund rejections frequently rest on the consideration condition or the distinct person condition rather than on classification at all.

Fifth, positions differ across group entities. Where a comparable entity elsewhere in the group has been treated as an intermediary, the inconsistency will be found.

Sixth, the pre and post omission periods are run together. A single submission covering several years has to distinguish the periods, because the place of supply analysis differs.

8. A review checklist

  1. List the parties and the supplies, and identify whether any main supply exists between two other persons.
  2. Read every agreement for agency language, and renegotiate it at the next renewal.
  3. Check whether remuneration is for the provider’s own scope or is calculated by reference to a third party transaction.
  4. Assemble evidence of performance: personnel, methodology, deliverables.
  5. Test the facts against each of the five prerequisites in Circular 159, and record the conclusion on each.
  6. Consider whether the sub-contracting exclusion applies, and say so if it does.
  7. Verify each of the five conditions in section 2(6) separately, with evidence for the consideration and distinct person conditions.
  8. Confirm the zero rating route actually used, and that it is available under section 16 as it now stands.
  9. Identify the periods in dispute and apply the correct place of supply rule to each.
  10. Reconcile refund claims to the credit ledger and the returns, and verify the computation under Rule 89(4).
  11. Check the position taken by other group entities in India and abroad.
  12. Where an adverse position has been taken for an earlier period, decide whether to contest it before it becomes a precedent within the group.

Practitioner’s perspective

The intermediary classification has been among the most actively litigated questions in Indian indirect tax, and the reason is structural: a broadly worded definition was coupled with a place of supply rule that produced a severe consequence. The omission of that rule removes much of the sting for periods going forward, and it is a welcome and overdue change for India’s services export sector.

It changes nothing for the periods already in dispute, and those periods will take years to work through. For a business with open refund claims or pending appeals, the classification defence remains exactly as important as it was, and it remains a defence built on contractual and functional evidence rather than on argument.

The practical lesson is the one that applies across this area. The words used in the commercial agreement are read as legal terms, whatever the parties intended by them. A clause describing a provider as coordinating on behalf of a customer costs nothing to draft and a great deal to defend. Reviewing agreements for that language, and changing it at renewal, is the cheapest risk reduction available in this area.

What courts have said since 2025 on exporters who supply on their own account

For periods before 30 March 2026, the classification still decides the refund, and recent decisions show how High Courts approach it. In Union of India v. KC Overseas Education Pvt. Ltd., the Bombay High Court held that an Indian provider of recruitment and referral services, paid in convertible foreign exchange by foreign universities, was not an intermediary and had made an export of services; the Supreme Court dismissed the Revenue’s special leave petition in 2025. The Delhi High Court reached a similar view in Commissioner of Delhi GST v. Global Opportunities Pvt. Ltd., and the Supreme Court declined to interfere on 27 January 2026.

In Fateh Education Consulting Pvt. Ltd. v. Assistant Commissioner, decided on 8 May 2026, the Delhi High Court set aside a refund rejection that rested on the intermediary ground, directed the refund with statutory interest, and noted that the respondents did not dispute the legal position. These are decisions on their own facts, and a dismissal of a special leave petition is not itself a declaration of law, so the reasoning of the High Court judgments is what a taxpayer should cite. They do, however, show that contracting with the foreign recipient, invoicing it and being paid by it are weighty facts.

Where a refund has been rejected, the usual route is an appeal to the first appellate authority under section 107 of the CGST Act and then to the GST Appellate Tribunal (GSTAT) under section 112. The GSTAT was inaugurated on 24 September 2025 and, according to commentary, started hearing cases from 16 February 2026, with State Benches being brought into operation through 2026 and an e-filing portal in use. The window for appealing older orders was extended to 31 July 2026, so any rejection order not yet appealed should be checked for limitation immediately; the current position of the bench covering your State should be confirmed on the GSTAT portal.

Reviewing the import side after the omission

Because section 13(8)(b) no longer applies, a supply of intermediary services by a foreign agent to an Indian recipient has its place of supply in India under section 13(2). The supply is then an import of services, and the Indian recipient is liable to pay integrated tax under reverse charge, issue a self-invoice and claim credit only if the underlying use is eligible. Businesses in sectors where credit is restricted or blocked, such as some financial and hospitality businesses, should model the cost of this change.

A practical review has four steps. List every overseas payee described as an agent, introducer, placement agent, sourcing agent or commission recipient. For each, read the agreement to see whether the payee arranges a supply between the Indian business and a third party (an intermediary) or supplies a service on its own account. Identify the time of supply by reference to the invoice and payment dates, since commentary treats services supplied on or after 30 March 2026 as governed by the amended rule. Finally, decide whether past payments for periods before 30 March 2026 need any attention, which is generally a question of the old place-of-supply rule rather than of the amendment.

Frequently asked questions

1. What is the statutory test for an intermediary?

Section 2(13) of the IGST Act defines an intermediary as a broker, agent or other person who arranges or facilitates the supply of goods, services or securities between two or more persons, excluding a person who supplies those goods, services or securities on his own account.

2. How many parties are needed before the definition can apply?

At least three. Circular No. 159/15/2021-GST requires two principals transacting with each other and the intermediary who arranges or facilitates that transaction. An arrangement between two parties cannot produce an intermediary.

3. Is a sub-contractor an intermediary?

No. Circular No. 159/15/2021-GST states expressly that sub-contracting is excluded, because a sub-contractor performs the main service rather than arranging it.

4. Does working alongside other contractors make a provider an intermediary?

Not by itself. Coordination performed as part of delivering one’s own contractual scope is not facilitation of a supply between two other persons. The department must identify the main supply said to be arranged.

5. What is the significance of commission based remuneration?

It is a strong indicator of facilitation, because a fee calculated as a share of the value of a transaction between two other parties suggests the provider is remunerated for bringing that transaction about rather than for its own output.

6. What happened to section 13(8)(b)?

It placed the supply of intermediary services at the location of the supplier. It was omitted by the Finance Act 2026, so intermediary services now fall to the default rule in section 13(2), under which the place of supply is the location of the recipient. Published commentary treats the omission as effective from Presidential assent on 30 March 2026, because section 157 of the Finance Act 2026 has no separate commencement date; the enacted text should be checked for supplies made around that date.

7. Does that omission help periods already under dispute?

No. The omission operates prospectively. Open assessments, refund rejections and appeals for earlier periods continue to be governed by section 13(8)(b), and the classification remains determinative for them.

8. Does the omission create any new liability?

Yes, on the import side. Because the place of supply now follows the recipient’s location under section 13(2), a foreign intermediary supplying an Indian recipient has its place of supply in India. The supply is an import of services on which the Indian recipient discharges integrated tax under reverse charge, with credit where otherwise eligible. Payments to overseas agents and introducers should be reviewed on that footing.

9. What did the Bombay High Court decide in Dharmendra M. Jani?

A Division Bench split, one judge holding section 13(8)(b) ultra vires and the other upholding it. On reference the third judge held the provision valid but confined in its operation to the IGST Act alone, so that it could not found a levy under the central and state legislation, and held the transactions to be exports under section 2(6).

10. What are the conditions for export of services?

Section 2(6) of the IGST Act requires that the supplier is in India, the recipient is outside India, the place of supply is outside India, payment is received in convertible foreign exchange or in Indian rupees where permitted by the Reserve Bank, and the supplier and recipient are not merely establishments of a distinct person.

11. Can export be made with payment of tax and refund claimed?

Only for a notified class of persons or a notified class of goods or services. Following the substitution of section 16(3) with effect from 1 October 2023, the general route is supply under bond or letter of undertaking without payment of tax with refund of unutilised credit under section 54 of the CGST Act, and the with payment route is available under section 16(4), as amended by the Finance (No. 2) Act 2024, only as notified.

12. Is an intermediary service an export of service after the Finance Act 2026?

It can be. Section 13(8)(b) of the IGST Act was omitted with effect from 30 March 2026, so intermediary services follow section 13(2) and the place of supply is the recipient’s location. If the recipient is outside India and the other conditions of section 2(6) are met, including payment in convertible foreign exchange or permitted rupees, the supply can be an export. Earlier periods follow the old rule.

13. Is GST payable on commission paid to a foreign agent after section 13(8)(b) was omitted?

It may be. Where the foreign agent is an intermediary supplying an Indian recipient, the place of supply is now in India, so the supply is an import of services and the Indian recipient pays IGST under reverse charge. Input tax credit is available only if the recipient is otherwise eligible. Each agreement should be read to confirm that the payee is in fact an intermediary.

14. Does section 2(13) of the IGST Act still matter after 2026?

Yes. The Finance Act 2026 omitted only the place of supply rule in section 13(8)(b) and left the definition in section 2(13) unchanged. The classification still governs disputes for supplies before 30 March 2026 and may matter for other provisions that refer to intermediaries, so the three-party test in Circular 159/15/2021-GST remains relevant.

15. What did the Supreme Court do in the KC Overseas Education case?

The Supreme Court dismissed the Revenue’s special leave petition against the Bombay High Court, which had held that referral services supplied to foreign universities and paid for in foreign exchange were an export of services and not intermediary services. A dismissal of a special leave petition is not a declaration of law, so the High Court’s reasoning is what is usually cited.

Talk to SBC’s tax team

If an intermediary allegation or a refund rejection is open for your export of services, a document review of the contracts and the performance record is the usual first step. Our GST team can discuss the position for each period. Explore our GST services | Contact SBC

Disclaimer

This article is for general information and does not constitute professional advice. It reflects the law as understood at the date of publication and does not take account of later developments. The place of supply rule applicable to intermediary services changed during 2026, so the analysis depends on the period in question, and the classification of any arrangement turns on its contractual terms and the functions actually performed. No reader should act on the basis of this article without taking advice on their own circumstances.

CategoriesGST

Your GST Return May Be Correct and Still Be Wrong: Why GSTR-1 vs GSTR-3B Reconciliation Is Not Enough

Your GST Return May Be Correct and Still Be Wrong

Why GSTR-1 and GSTR-3B Reconciliation Alone Is Not Enough to Establish GST Compliance

Quick Answer

Matching GSTR-1 and GSTR-3B does not establish complete GST compliance. It only proves that two returns agree with each other. Transactions that never reached the returns, such as scrap sales, expense recoveries, advances, asset disposals or related-party supplies, will not show up as a mismatch at all. A complete GST review must also test the returns against books of accounts, GSTR-2B and the Invoice Management System (IMS), Form 26AS/Form 168, GST TDS credits, e-invoices, e-way bills and bank statements.

Introduction: The Reconciliation That Gives False Comfort

In many years of reviewing GST positions for companies of every size, I have seen one sentence more often than any other at the start of an engagement: “Our GSTR-1 and GSTR-3B are fully reconciled.” It is usually said with confidence, and usually it is true. The two returns do agree.

The difficulty is that the GST department, and increasingly its analytics systems, do not stop there. A notice rarely asks whether your two returns match. It asks why your income-tax return shows higher receipts than your GST turnover, why your e-way bills suggest more outward movement than your invoices, why a government customer has deducted GST TDS on contracts you have not reported, or why you claimed credit that your supplier never paid.

In other words, your GST return may be arithmetically correct and still be wrong. This article explains why, which records you should reconcile, and how to set up a review that holds up when the department looks at your data from every angle.

Why Return-to-Return Matching Has Become the Easy Part

The GST system itself has made the GSTR-1 vs GSTR-3B match more automatic over the past few years. On the GST Portal, liability in GSTR-3B is auto-populated from GSTR-1, and input tax credit (ITC) is auto-populated from GSTR-2B. Some recent changes have tightened this further:

  1. GSTR-1A was introduced in 2024 so that taxpayers can correct the current period’s GSTR-1 before filing GSTR-3B, rather than overriding figures directly in GSTR-3B.
  2. The Invoice Management System (IMS), operational from October 2024, lets a recipient accept, reject or keep pending each supplier invoice before it flows into GSTR-2B.
  3. Table 3.2 of GSTR-3B (inter-state supplies to unregistered persons, composition dealers and UIN holders) has been made non-editable from the November 2025 tax period, with corrections routed through GSTR-1A or GSTR-1/IFF.
  4. System-generated intimations now flag mismatches automatically: Form GST DRC-01B under Rule 88C for liability differences between GSTR-1 and GSTR-3B, and Form GST DRC-01C under Rule 88D for ITC claimed in excess of GSTR-2B.

Process manuals and advisories on these features are published on the GSTN tutorial portal. The practical consequence is that the two returns will increasingly match by design. That makes the match a weaker test of compliance than ever. The real exposure now sits in what never entered GSTR-1 in the first place, and in credit that appears in GSTR-2B but is not legally eligible.

1. Matching Returns Does Not Mean Complete Compliance

GSTR-1 and GSTR-3B may match even when certain business transactions remain unreported. Miscellaneous income, expense recoveries, advances or sale of fixed assets may not have been examined while preparing returns, because the return preparer typically works from the sales register and not from the general ledger.

Section 35 of the CGST Act, 2017 requires every registered person to keep true and correct accounts of production or manufacture, inward and outward supplies, stock, ITC availed, output tax payable and tax paid. The full text of the Act and the CGST Rules, 2017 is available on the CBIC GST website. The obligation is to report what actually happened in the business, not what was captured in a register.

GST compliance must therefore be verified against the underlying books and business transactions, rather than relying only on return-to-return reconciliation.

A simple illustration

Consider a manufacturer with monthly sales of ₹8 crore. GSTR-1 and GSTR-3B match to the rupee every month. During a review, the general ledger shows:

  • ₹42 lakh credited to “Miscellaneous Income” from sale of process scrap
  • ₹18 lakh recovered from a group company towards shared office rent and staff costs
  • A used machine sold for ₹25 lakh, recorded directly against the fixed asset account

None of these passed through the sales register, so none reached GSTR-1. The returns matched perfectly, yet more than ₹85 lakh of potentially taxable value was never examined. The issue is not a mismatch; it is an omission.

2. Examine Books of Accounts for Unreported Transactions

Books of accounts give a far broader picture of business activity than any return. The reconciliation should cover sales and purchase registers, general ledgers, journal entries, the fixed asset register, debit and credit notes, expense recoveries and miscellaneous income.

Particular attention should be given to:

  1. Sale of scrap and fixed assets. These are supplies in the course or furtherance of business and are often booked outside the sales module.
  2. Liquidated damages, reimbursements and other expense recoveries. Each needs to be tested against the definition of supply and Schedule II.
  3. Related-party transactions and stock transfers. Supplies between related persons or distinct persons (for example, branches in different States) are treated as supply even without consideration under Schedule I. Valuation also follows the specific rules for related-party supplies, which is why GST reviews often need to be read alongside the group’s transfer pricing position.
  4. Schedule I supplies without consideration. Permanent transfer of business assets on which ITC has been availed and gifts to employees beyond ₹50,000 in a year are common examples.
  5. Cross-charges within the group. For Global Capability Centres (GCCs) and shared-service models, cost allocations, secondment arrangements and recoveries of common expenses frequently carry GST implications that are not visible in the sales register.
  6. Advances received for services. Under the time-of-supply provisions, GST on services is generally triggered on receipt of an advance. Advances for goods stand on a different footing, as most taxpayers have been relieved from paying GST on such advances.

Each transaction must be examined under the definition of supply in Section 7, Schedules I, II and III, applicable exemptions and the time-of-supply provisions. Rule 33 of the CGST Rules should also be considered to determine whether the pure-agent exclusion is genuinely available for reimbursements. In practice, many reimbursements do not meet all the pure-agent conditions, and the recovery is then part of the value of supply.

3. ITC: Eligibility, Reconciliation and Reversals

An invoice appearing in GSTR-2B does not by itself establish ITC eligibility. Businesses must independently verify the conditions under Section 16 and the restrictions under Section 17 of the CGST Act, including blocked credits under Section 17(5).

Under Section 16, credit is available only where the recipient holds a valid tax invoice or debit note, the details have been furnished by the supplier and communicated to the recipient, the goods or services have been received, the tax has actually been paid to the Government by the supplier, and the recipient has filed its return. Credit must also be claimed within the time limit in Section 16(4), which is generally 30 November following the end of the financial year, or the date of filing the annual return, whichever is earlier.

Reconciliation between the purchase register, IMS, GSTR-2B and GSTR-3B should identify:

  1. Missing or duplicate invoices.
  2. Incorrect GSTINs and differences in taxable value or tax amount.
  3. Unreported credit and debit notes, including credit notes rejected or kept pending in IMS.
  4. Ineligible or blocked credits, such as motor vehicles, food and beverages, works contracts for immovable property and goods or services used for personal consumption.
  5. Reversals required for non-payment to suppliers within 180 days (Rule 37), for exempt or non-business use (Rules 42 and 43), and for supplier default (Rule 37A).

Rule 37A: the reversal most businesses miss

Rule 37A deals with a specific risk. Where a supplier has reported an invoice in GSTR-1 but has not filed GSTR-3B for that period by 30 September following the end of the financial year, the recipient must reverse the related ITC in a GSTR-3B filed on or before 30 November. If not reversed in time, the amount is payable with interest. The credit can be re-availed once the supplier files the pending return. Because this depends on the supplier’s filing status, it cannot be caught by comparing your own two returns.

How to report reversals

CBIC has clarified how ITC availed, reversed and reclaimed should be reported in Table 4 of GSTR-3B in Circular No. 170/02/2022-GST. Getting the table right matters, because it is the basis on which the system tracks credit that has been reversed and can later be reclaimed.

Businesses should also respond promptly to any DRC-01C intimation under Rule 88D. The objective of this entire exercise is simple: ITC claimed should be both correctly reported and legally eligible.

4. Form 26AS / Form 168, GST TDS and Bank Statements

Form 26AS and Form 168

Form 26AS, available on the Income Tax e-filing portal, records income-tax TDS and TCS reported by customers against your PAN, along with other reported transactions. It is a useful independent check on customer receipts. With the Income-tax Act, 2025 now in force, this statement is issued as Form No. 168 (the Annual Information Statement) under Rule 245 of the Income-tax Rules, 2026, as explained in the Income Tax Department’s Form 168 FAQs. For periods up to 31 March 2026, Form 26AS remains the relevant reference.

When comparing these figures with GST turnover, remember that the tax base is different. CBDT Circular No. 23/2017 dated 19 July 2017, issued under the Income-tax Act, 1961 and available through the Income Tax Department, clarified that where GST on services is indicated separately in the agreement, income-tax TDS is to be deducted on the amount excluding GST. Differences in timing, PAN-level versus GSTIN-level reporting, and the treatment of the GST component should all be expected. Readers should also confirm the corresponding position under the Income-tax Act, 2025 for tax years from 2026-27. This is one area where coordination between the GST team and the income-tax compliance team pays for itself.

GST TDS under Section 51

GST TDS under Section 51 of the CGST Act is a separate mechanism. Notified deductors, mainly Government departments, local authorities and specified public sector bodies, deduct GST TDS on payments to suppliers of taxable goods or services above the prescribed contract value. They report it in GSTR-7, and the credit is made available to the supplier on the GST portal, including in Part C of GSTR-2A.

A GST TDS credit is, in effect, a customer telling the department that you made a taxable supply. If the corresponding invoice is not in GSTR-1, the gap is visible. Differences should be examined with reference to invoices, contracts and accounting records.

Bank statements

Bank statements should be reconciled with the books to identify customer receipts, advances, security deposits, loans, capital contributions, inter-account transfers and refunds. Every bank credit is not taxable turnover. Its underlying nature and the applicable time-of-supply provisions must be established before determining GST liability. What matters is that every material credit can be explained with documents.

5. Reconcile E-Invoices and E-Way Bills

E-invoices

Under Rule 48(4), notified taxpayers must report specified invoices and credit or debit notes on the Invoice Registration Portal (IRP) and obtain an Invoice Reference Number (IRN). Since 1 August 2023, e-invoicing applies to taxpayers whose aggregate turnover in any financial year from 2017-18 onwards exceeds ₹5 crore. From 1 April 2025, taxpayers with aggregate annual turnover of ₹10 crore or more cannot report a document on the IRP more than 30 days after its date. The e-invoice portal is the official source for the applicable schema and advisories.

E-invoice details are auto-populated into the relevant tables of GSTR-1. Businesses should reconcile accounting invoices, generated and cancelled IRNs, GSTR-1 and GSTR-3B to identify omissions, duplicate entries and reporting differences. A common gap is an IRN cancelled on the IRP but not reversed in the books, or the reverse.

E-way bills

Rule 138 governs the movement of goods, including movements for reasons other than supply, such as job work, branch transfers, sales returns and goods sent on approval. E-way bills generated on the e-way bill portal should be compared with tax invoices, delivery challans, stock records, quantities and recipient GSTINs.

An e-way bill does not necessarily represent a taxable outward supply. However, an e-way bill with no matching invoice or challan is exactly the kind of data point that leads to questions. The purpose of every movement must be established and documented.

6. Integrated GST Reconciliation

An effective reconciliation covers multiple records rather than only two GST returns. The table below sets out the comparisons that I recommend as a minimum:

Records compared Purpose What it typically reveals
Books of accounts vs GSTR-1 Identify omitted supplies Scrap, asset sales, recoveries, related-party supplies
GSTR-1 vs GSTR-3B Verify liability and payment Short payment, period mismatches, DRC-01B risk
Purchase register vs IMS / GSTR-2B Identify ITC differences Missing invoices, supplier errors, DRC-01C risk
GSTR-2B vs eligibility review Confirm legal eligibility Blocked credits, Rule 37/37A/42/43 reversals
Form 26AS / Form 168 vs sales records Examine receipt differences Unreported customers, timing gaps
GST TDS (GSTR-2A Part C) vs GSTR-1 Test Government contract reporting Invoices not reported, rate errors
E-invoices vs GSTR-1 Identify reporting gaps Cancelled IRNs, duplicates, late reporting
E-way bills vs stock records Verify movement of goods Unexplained outward movements
Bank statements vs books Identify unreconciled receipts Advances, unrecorded income
Expense ledgers vs GSTR-3B Examine RCM and ITC Missed reverse-charge liability

Classifying the differences

Not every difference is a tax exposure. Once differences are identified, classify each one into one of the following categories before deciding on the action:

  1. Timing differences that reverse in a later period.
  2. Accounting adjustments such as provisions, reclassifications and accruals.
  3. Reporting errors where tax was paid but reported in the wrong table or period.
  4. Incorrect tax treatment, for example wrong rate, wrong place of supply or wrong classification.
  5. Documentation gaps, where the treatment is right but the evidence is missing.
  6. Actual tax exposure, where tax, interest or reversal is genuinely due.

Only the last category needs to be paid. The others need to be corrected, documented or explained. This classification is also the most useful format for discussing the outcome with management and auditors.

7. A Step-by-Step Approach to a GST Health-Check

Businesses should undertake periodic reviews rather than waiting for annual return filing. A structured GST health-check typically follows these steps:

  1. Define scope and period. Cover each GSTIN separately and decide the financial years in scope.
  2. Collect data. Extract the trial balance, ledgers, sales and purchase registers, fixed asset register, GSTR-1, GSTR-1A, GSTR-3B, GSTR-2A/2B, IMS actions, e-invoice and e-way bill data, Form 26AS/Form 168 and bank statements.
  3. Map the general ledger. Tag every income and recovery ledger as taxable, exempt, non-GST or not a supply, with reasons.
  4. Run the reconciliations. Perform the comparisons in the table above.
  5. Test ITC eligibility. Review Section 16 conditions, Section 17(5) blocked credits and required reversals.
  6. Review reverse-charge liability. Check legal services, goods transport agency services, import of services, renting by unregistered persons and other notified categories.
  7. Classify and quantify. Sort differences into the six categories above and compute tax and interest under Section 50 where applicable.
  8. Correct and document. Use GSTR-1A, subsequent returns or Form DRC-03 for voluntary payment, and build a file of evidence for positions taken.

The annual return in GSTR-9 and, where applicable, the reconciliation statement in GSTR-9C are good occasions for this review, but they should not be the first time it happens. Corrections are time-bound. ITC is lost after the Section 16(4) date, and following amendments made by the Finance Act, 2023, returns generally cannot be filed after three years from their due date. Many organisations choose to run these reviews monthly or quarterly as part of their finance and compliance outsourcing framework so that issues are caught while they can still be fixed.

Common Red Flags That Return Matching Will Not Catch

From practical experience, the following situations are the ones that most often lead to notices even when returns match:

  1. Income-tax turnover or Form 26AS receipts higher than GST turnover with no reconciliation on file.
  2. Large “Other Income” or “Miscellaneous Income” balances with no GST analysis.
  3. Group cost recharges and secondment arrangements treated as non-taxable without a documented basis.
  4. ITC claimed on invoices from suppliers who have stopped filing returns or whose registration has been cancelled.
  5. E-way bills generated for outward movement where no invoice or challan was raised.
  6. GST TDS credits from Government customers with no matching outward supply in GSTR-1.
  7. Reverse-charge liability on legal fees, transport or imported services not paid.
  8. Credit notes issued commercially but not reported, or reported without the required reduction of ITC by the recipient.

Why This Matters Now: Consequences of Getting It Wrong

GST is increasingly enforced through data. The department has access to e-invoice, e-way bill, GSTR-1, GSTR-2B, GSTR-3B and income-tax data, and the GST Council continues to recommend changes that put more reliance on system-based matching. Unexplained differences can lead to:

  1. Automated intimations in DRC-01B or DRC-01C that require a reply or payment, failing which the filing of subsequent GSTR-1 may be restricted.
  2. Scrutiny of returns under Section 61 and audit under Section 65.
  3. Demand proceedings under Section 73 or 74 for earlier years, and under Section 74A for financial year 2024-25 onwards, with interest under Section 50 and penalties.
  4. Blocking of credit in the electronic credit ledger and, in serious cases, suspension of registration.

Policy and enforcement are administered by the Central Board of Indirect Taxes and Customs (CBIC) under the Department of Revenue, Ministry of Finance. For practitioners, the Institute of Chartered Accountants of India (ICAI) also publishes technical guidance on GST audits and reconciliations that is useful for structuring reviews.

The Practitioner’s Perspective

Over the years, three principles have consistently separated businesses that handle GST scrutiny well from those that struggle:

  1. Transaction-level verification. Compliance should reflect actual business activities, not merely figures reported in returns.
  2. Evidence-based examination. Every difference must be evaluated with invoices, contracts, bank statements and ledger records, and the conclusion must be documented at the time, not reconstructed years later in response to a notice.
  3. Early identification. Timely reconciliation helps correct reporting errors, address genuine liabilities and keep interest and litigation to a minimum.

GST compliance must be evaluated against the transaction, not merely against the return.

Frequently Asked Questions

1. If GSTR-1 and GSTR-3B match, does it mean that GST compliance is complete?

No. Matching only shows that the two returns are consistent for the information reported. It does not show that all business transactions were captured, correctly valued or correctly taxed, or that ITC claimed is eligible.

2. Why should books of accounts be reconciled with GST returns?

Section 35 of the CGST Act requires registered persons to keep true and correct accounts of supplies, stock, ITC, output tax and tax paid. Reconciling books with returns identifies transactions that never reached the sales register, such as scrap sales, asset disposals and expense recoveries.

3. Does every difference between books of accounts and GSTR-1 result in additional GST liability?

No. Differences may arise from timing, accounting treatment, non-GST transactions, exempt supplies, capital receipts or other reasons. Each difference must be examined based on its nature and the applicable GST provisions, and only genuine exposures require payment.

4. Does the appearance of an invoice in GSTR-2B automatically make ITC eligible?

No. GSTR-2B reflects what the supplier has reported. The recipient must independently satisfy the conditions in Section 16, check the restrictions in Section 17 including blocked credits under Section 17(5), and make reversals required under Rules 37, 37A, 42 and 43.

5. What is the role of the Invoice Management System (IMS) in ITC reconciliation?

IMS allows a recipient to accept, reject or keep pending each invoice uploaded by suppliers before it flows into GSTR-2B. It is a useful control point, but accepting an invoice in IMS does not by itself confirm that the credit is legally eligible.

6. Can Form 26AS be used to identify unreported GST turnover?

Form 26AS (now Form 168 under the Income-tax Rules, 2026) can serve as an additional source because it contains income-tax TDS and TCS reported by customers. Differences may arise due to periods, tax bases, PAN-level reporting and the GST component, so it should be used as an investigative tool, not as a direct measure of taxable turnover.

7. Is GST TDS the same as income-tax TDS reflected in Form 26AS?

No. Income-tax TDS operates under income-tax law, while GST TDS operates under Section 51 of the CGST Act. GST TDS is reported by the deductor in GSTR-7 and made available to the supplier on the GST portal.

8. Why should e-invoices be reconciled with GSTR-1?

E-invoice data is auto-populated into GSTR-1 for applicable taxpayers. Reconciliation identifies invoices not reported on the IRP, cancelled IRNs still in the books, duplicate entries and documents that cannot be reported because of the 30-day time limit for taxpayers with turnover of ₹10 crore or more.

9. Does every e-way bill indicate a taxable outward supply?

No. E-way bills may relate to taxable supplies, movements for reasons other than supply such as job work or branch transfers, inward supplies from unregistered persons and other prescribed movements. The purpose and supporting documents must be examined for each movement.

10. Can bank credits be treated as taxable turnover for GST purposes?

Not automatically. Bank credits may represent customer receipts, loans, capital contributions, inter-account transfers, refunds or deposits. Their nature must be established before determining GST implications, though advances for services may trigger GST on receipt.

11. What happens if there is a difference between GSTR-1 and GSTR-3B?

Where the difference exceeds the prescribed limits, the system issues an intimation in Form GST DRC-01B under Rule 88C. The taxpayer must pay the difference or explain it within the prescribed time, failing which the filing of subsequent GSTR-1 can be restricted and recovery proceedings may follow.

12. What happens when ITC claimed in GSTR-3B exceeds the amount in GSTR-2B?

Where the excess crosses the prescribed thresholds, an intimation is issued in Form GST DRC-01C under Rule 88D. The taxpayer must either pay the excess with interest through Form DRC-03 or explain the difference in Part B of DRC-01C within the prescribed time.

13. What is Rule 37A and why does it matter?

Rule 37A requires a recipient to reverse ITC where the supplier has reported the invoice in GSTR-1 but has not filed GSTR-3B for that period by 30 September following the financial year. The reversal must be made by 30 November, and the credit can be re-availed once the supplier files.

14. How often should businesses undertake integrated GST reconciliation?

Monthly or quarterly, depending on transaction volume and complexity, with a comprehensive annual review before filing GSTR-9 and GSTR-9C. Waiting until the year end risks losing ITC after the Section 16(4) deadline and missing the window for correcting returns.

Talk to SBC’s Tax Team

SBC assists businesses in identifying GST reconciliation gaps, evaluating statutory implications, quantifying potential tax exposure and establishing a defensible compliance framework. Explore our GST advisory services or Contact SBC to discuss a review of your GST position.

Disclaimer

This article is provided for general informational and educational purposes only and should not be considered legal, tax, financial or professional advice. GST applicability depends on the facts of each transaction, the relevant statutory provisions and the amendments applicable to the tax period. Tax laws, rules, notifications, thresholds and portal functionalities change from time to time, and the information in this article may not reflect the latest position. Readers should verify the current position from official government sources such as the CBIC, the GST Portal and the Income Tax Department, and should consult a qualified professional for advice specific to their circumstances before acting on any information in this article.

CategoriesGST SBC

India’s Transfer Pricing Reporting Framework Enters a New Era: Transition from Form 3CEB to Form 48

India Union Budget 2026-27

Home > Common GST Compliance Mistakes That Trigger Tax Notices in 2026

Preparing for the Next Phase of Transfer Pricing Compliance

The introduction of the Income-tax Act, 2025 marks a significant development in India’s transfer pricing framework. Among the notable changes is the replacement of Form 3CEB with Form 48, introducing a more comprehensive reporting framework for transfer pricing compliance. This is especially relevant for businesses relying on Transfer Pricing Services in India to stay compliant through the transition.

While this change may appear to be a simple replacement of forms, it has far-reaching implications for businesses undertaking international transactions and specified domestic transactions. Form 48 requires taxpayers to provide more detailed information supporting their transfer pricing positions, making it essential for businesses to strengthen their documentation and compliance processes well in advance.

The transition also provides taxpayers with an opportunity to review their existing transfer pricing documentation and ensure they are prepared for the enhanced reporting requirements under the new law.

Which Form Applies and When?

One of the most common questions among taxpayers is whether Form 48 is applicable for the current financial year.

The answer is straightforward.

Financial Year Applicable Form Governing Law
FY 2025–26 Form 3CEB Section 92E of the Income-tax Act, 1961
FY 2026–27 onwards Form 48 Section 172 of the Income-tax Act, 2025 read with Rule 85 of the Income-tax Rules, 2026

Accordingly, taxpayers filing their accountant report for FY 2025–26 will continue to furnish Form 3CEB. Form 48 is effectively applicable from FY 2026–27. Although businesses have one transition year before Form 48 becomes applicable, they should utilise this period to assess their transfer pricing documentation and reporting processes, as the new form requires significantly more detailed disclosures than its predecessor.

Why Was Form 48 Introduced?

The introduction of Form 48 is aimed at strengthening the quality and consistency of transfer pricing reporting.

While Form 3CEB primarily required the Chartered Accountant to certify the particulars of international transactions and specified domestic transactions, Form 48 adopts a more structured reporting approach by requiring taxpayers to disclose additional information supporting the arm’s length nature of such transactions.

The objective is to:

  • improve the quality and consistency of transfer pricing reporting;
  • facilitate automated validation and cross-verification of information across various tax filings;
  • enable risk-based assessment through data analytics; and
  • encourage taxpayers to maintain robust contemporaneous transfer pricing documentation.

The transition therefore reflects the Government’s objective of making transfer pricing reporting more transparent, consistent and evidence-based.

The Income Tax Department has published an official Guidance Note on Form No. 48 detailing the reporting requirements directly.

Form 48 – A More Comprehensive Reporting Framework

The most significant change under Form 48 is not merely the reporting format but the extent of information that taxpayers will be required to maintain and disclose.

Unlike Form 3CEB, Form 48 places greater emphasis on the economic analysis supporting transfer pricing positions. Consequently, taxpayers should ensure that robust transfer pricing documentation is available before the reporting process begins.

Some of the additional information expected to be reported under Form 48 includes:

  • Arm’s length margin determined for the benchmarked transactions.
  • Details of the benchmarking analysis supporting the arm’s length outcome.
  • Selection and justification of the Most Appropriate Method (MAM).
  • Functional, Asset and Risk (FAR) analysis.
  • Comparable company search process and financial analysis.
  • Transaction-wise reporting and reconciliation with statutory filings.
  • Details of parent-company borne costs and intra-group allocations, wherever applicable.

Accordingly, businesses can no longer treat benchmarking as a year-end exercise. The benchmarking study should be completed upfront so that the arm’s length margin and supporting analyses are readily available while preparing Form 48.

Documentation Readiness – Why Businesses Should Start Preparing Now

Although Form 48 is applicable from FY 2026–27, businesses should begin preparing during the current financial year to avoid last-minute compliance challenges.

To ensure a smooth transition, businesses should maintain the following documentation:

  • Updated Transfer Pricing Documentation (Local File).
  • Benchmarking Report supporting the arm’s length nature of international transactions.
  • Arm’s Length Margin computation.
  • Functional, Asset and Risk (FAR) analysis.
  • Comparable company search and benchmarking workings.
  • Intercompany agreements and supporting commercial documentation.
  • Segmental financial information, wherever applicable.
  • Information relating to parent-company borne costs, employee stock option costs and shared service allocations, where relevant.
  • Reconciliation of transfer pricing information with the financial statements, tax audit report and income-tax return.

Preparing these documents in advance will help businesses respond efficiently to the enhanced disclosure requirements under Form 48.

How SBC Can Support Your Transition

The transition from Form 3CEB to Form 48 is more than a change in the reporting format—it requires businesses to revisit their transfer pricing documentation and ensure that all supporting analyses are available before the reporting process commences.

As a dedicated Transfer Pricing Consultant for businesses navigating this transition, SBC brings the following support:

At SBC, our Transfer Pricing professionals assist businesses in preparing for Form 48 by providing:

  • Form 48 readiness assessments;
  • review of existing transfer pricing documentation;
  • benchmarking studies and arm’s length margin analyses;
  • FAR analysis and economic documentation;
  • review of intercompany agreements;
  • gap analysis of documentation against Form 48 reporting requirements; and
  • end-to-end transfer pricing advisory, compliance and litigation support.

Our objective is to help businesses transition smoothly to the new reporting framework while ensuring that their transfer pricing documentation remains technically robust and audit-ready. For the complete regulatory breakdown — documentation requirements, benchmarking methods, and audit support — see our full guide: Transfer Pricing Services in India. Businesses managing GST and income tax compliance alongside transfer pricing can find related guidance through SBC’s GST Advisory Services.

For the complete regulatory breakdown — documentation requirements, benchmarking methods, and audit support — see our full guide: Transfer Pricing Services in India.

Key Takeaways

  • Form 3CEB continues to apply for FY 2025–26.
  • Form 48 effectively applicable from FY 2026–27  under Section 172 read with Rule 85 of the Income-tax Rules, 2026.
  • Form 48 requires significantly more detailed disclosures, including benchmarking outcomes, arm’s length margins, FAR analyses and supporting economic analyses.
  • Businesses should complete their benchmarking studies and maintain robust transfer pricing documentation well before the first Form 48 filing.
  • Information from overseas Associated Enterprises, including parent-company borne costs and shared service allocations, should be obtained in advance to support the enhanced reporting requirements.
  • Although the reporting framework has evolved, the arm’s length principle, recognised transfer pricing methods and documentation requirements continue under the new legislation.

Conclusion

The transition from Form 3CEB to Form 48 represents an important step in the evolution of India’s transfer pricing compliance framework. While Form 3CEB remains applicable for FY 2025–26, businesses should utilise this transition year to strengthen their transfer pricing documentation, complete benchmarking analyses, and establish robust internal processes to meet the enhanced reporting requirements under Form 48.

Early preparation will not only facilitate seamless compliance but also help businesses minimise reporting risks and confidently address future transfer pricing assessments. Businesses managing GST and income tax compliance alongside transfer pricing can find related guidance through SBC’s GST Advisory Services. With the right planning and technical support, organisations can transform this regulatory change into an opportunity to strengthen their overall transfer pricing governance.

Frequently Asked Questions

Q: Does e-invoicing apply to B2C (business-to-consumer) sales?

A: No, the core e-invoicing mandate applies to B2B supplies and exports. B2C invoices follow separate rules, including dynamic QR code requirements for certain businesses, but not IRN generation.

Q: What happens if my turnover drops below INR 5 crore next year?

A: The obligation doesn’t switch off. Once your aggregate turnover has crossed INR 5 crore in any year since 2017-18, e-invoicing remains mandatory going forward, regardless of later fluctuations.

Q: Which Invoice Registration Portal (IRP) should I use?

A: Several government-authorised IRPs are available, including NIC’s portal and other authorised providers. Most businesses use whichever IRP their accounting software or ERP integrates with directly.

Q: Is a 6-digit HSN code mandatory for e-invoices?

A: Businesses above INR 5 crore turnover are required to use a minimum 6-digit HSN code at the item level; businesses at or below that threshold can use 4-digit codes.

Q: Does this affect my GST return filing directly?

A: Yes, indirectly a missing or invalid IRN can create inconsistencies between your e-invoice data and your GSTR-1 filing, which is exactly the kind of mismatch GSTN’s automated systems are now built to catch quickly.

Q: What if I’m not sure whether I’ve crossed the threshold in a past year?

A: This is worth a proper reconciliation rather than a guess, aggregate turnover has to be checked across every GSTIN under your PAN, across every year since 2017-18, which is easy to get wrong without a documented review.

×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesGST SBC

GST E-Invoicing in 2026: Do You Need to Comply at ₹5 Crore Turnover?

India Union Budget 2026-27

Home > Common GST Compliance Mistakes That Trigger Tax Notices in 2026

GST e-invoicing

When GST e-invoicing first rolled out in 2020, it only applied to businesses with turnover above INR 500 crore, a rule so narrow it barely touched anyone outside India’s largest corporates. That’s not the situation anymore. The threshold has been stepped down repeatedly since, and it now sits at INR 5 crore, low enough that a genuinely large share of mid-size Indian businesses are already in scope, whether or not they’ve actually checked.

This matters more than a compliance footnote. An invoice issued without a valid IRN isn’t just non-compliant on your side, it’s legally invalid, which means your buyer can’t claim input tax credit on it. That turns a missed e-invoicing obligation into someone else’s cash flow problem, and in our experience, that’s usually the moment it gets noticed and escalated often via the same kind of automated GST compliance mismatch that triggers a notice. Here’s exactly where the threshold stands right now, how it got here, and how to check whether your business is actually in scope.

What Is GST E-Invoicing?

A GST e-invoice isn’t just a digital copy of a regular invoice, it’s a business-to-business invoice that’s been reported to and validated by a government-authorized Invoice Registration Portal (IRP) before it’s issued to your customer. The IRP checks the invoice data, generates an Invoice Reference Number (IRN), and returns a digitally signed QR code that gets embedded on the final invoice. Only once that IRN exists is the invoice considered valid under GST law.

This is different from simply emailing a PDF invoice or generating one through accounting software, the validation step through the IRP is what makes it an “e-invoice” in the legal sense, not the file format.

The Current Threshold INR 5 Crore, and Here’s What That Actually Means

As things stand for FY 2026-27, e-invoicing is mandatory for any GST-registered business whose aggregate annual turnover (AATO) has exceeded INR 5 crore in any financial year going back to 2017-18. This threshold was set under Notification 10/2023-Central Tax and has been in force since 1 August 2023, it’s held steady since then, even as other GST rules around it have continued to shift.

“Aggregate turnover” here means the total value of sales across all GSTINs registered under the same PAN, including exports and exempt supplies, not just the turnover sitting in one branch or one state registration.

How the Threshold Has Fallen Since 2020
Effective Date Turnover Threshold
October 2020 Above INR 500 crore
January 2021 Above INR 100 crore
April 2021 Above INR 50 crore
April 2022 Above INR 20 crore
October 2022 Above INR 10 crore
August 2023 Above INR 5 crore (Current)

The direction here isn’t subtle. Every step down has pulled a wider band of ordinary mid-size businesses into scope, and CBIC’s own commentary has signaled the trend is toward covering more registered businesses over time, not fewer. If your business has been comfortably below past thresholds, that’s exactly the kind of assumption worth re-checking today rather than next year.

Once You Cross INR 5 Crore, You’re In Permanently

This is the detail that catches businesses off guard most often: the INR 5 crore check isn’t based on your current year’s turnover alone. If your aggregate turnover crossed INR 5 crore in any financial year since 2017-18, even a single year, even years ago, the e-invoicing obligation applies from the relevant notified date onward, and it doesn’t switch off if turnover later drops back below INR 5 crore.

In practice, this means a business that had one unusually large year a while back, followed by several quieter years since, can still be squarely in scope today. Checking only this year’s numbers and concluding you’re exempt is one of the more common and more costly mistakes we see.

The Extra Rule Above ₹10 Crore: The 30-Day IRN Window

Businesses with aggregate turnover of INR 10 crore or more face a tighter compliance layer on top of the base e-invoicing requirement. Since April 2025, invoices, credit notes, and debit notes older than 30 days from their invoice date can no longer be reported to the IRP for IRN generation at all, not delayed, simply blocked.

This is a genuinely easy rule to miss if invoice reporting isn’t built into a business’s regular monthly rhythm, since the consequence isn’t a penalty notice, it’s the invoice quietly becoming unable to be validated at all once the window closes.

Who’s Exempt, Regardless of Turnover

A handful of categories remain outside e-invoicing requirements even above INR 5 crore turnover:

  • Special Economic Zone (SEZ) units
  • Government Departments & Local Authorities
  • Insurance and banking companies
  • Goods Transport Agencies (GTAs)
  • Passenger transportation services
  • Cinema ticket sellers

Worth flagging: SEZ units are exempt, but SEZ developers are not, a distinction that trips up businesses operating within SEZ structures more often than it should.

How to Check If Your Business Is Actually in Scope

A proper check means looking at aggregate turnover across every GSTIN registered under your PAN, across every financial year since 2017-18, not just the most recent one. In practice:

  • Pull turnover figures for each financial year from 2017-18, combined across all your GSTINs
  • Check whether any single year crossed INR 5 crore, even if current turnover is lower
  • If you’re already above INR 10 crore, separately confirm your invoice reporting workflow respects the 30-day IRN window
  • Get this confirmed in writing as part of your GST advisory relationship, not assumed internally since tax notices on this point often surface well over a year after the fact, and a documented review is your clearest defence at that stage

Building this check into your regular filing rhythm is easier alongside our Compliance Calendar, which tracks this alongside your other statutory deadlines rather than as a separate, easy-to-forget task.

What Happens If You Don’t Comply

An invoice issued without a valid IRN when one was required isn’t a minor paperwork gap, it’s treated as not having been issued at all under GST law. That has two consequences that compound quickly: your own return reporting on the GSTN portal can be flagged as inconsistent, and your buyer loses the ability to claim input tax credit on that invoice. In practice, it’s often the buyer who notices first and escalates the issue back to you, since the missing ITC hits their numbers directly and if that escalation turns into an actual notice, our guide on how to respond to a GST notice in India walks through the reply format and timelines.

Where This Is Headed

Based on the pattern of the last five years, it would be reasonable to expect the threshold to be reviewed again rather than left permanently at INR 5 crore but no specific future figure has been officially announced, and speculating on one wouldn’t be useful. What’s more actionable right now is treating the current INR 5 crore line as a moving target worth re-checking periodically, rather than a one-time box to tick.

Key Takeaways
  • The current GST e-invoicing threshold is INR 5 crore aggregate turnover, in force since August 2023
  • Once crossed in any year since 2017-18, the obligation applies permanently, regardless of later turnover
  • Businesses above INR 10 crore face an additional 30-day IRN reporting window
  • Certain categories (SEZ units, insurance, banking, GTAs, passenger transport, cinema) remain exempt
  • An invoice without a valid IRN is treated as not issued at all, which blocks your buyer’s input tax credit

If you haven’t checked your aggregate turnover history against this threshold recently or if you’re already above INR 5 crore and want a second opinion on whether your invoicing workflow is fully compliant, that’s exactly the kind of review worth having before a mismatch surfaces on its own. Our GST Advisory Services in India cover exactly this kind of compliance check, alongside ongoing return filing and reconciliation support.

Frequently Asked Questions

Q: Does e-invoicing apply to B2C (business-to-consumer) sales?

A: No, the core e-invoicing mandate applies to B2B supplies and exports. B2C invoices follow separate rules, including dynamic QR code requirements for certain businesses, but not IRN generation.

Q: What happens if my turnover drops below INR 5 crore next year?

A: The obligation doesn’t switch off. Once your aggregate turnover has crossed INR 5 crore in any year since 2017-18, e-invoicing remains mandatory going forward, regardless of later fluctuations.

Q: Which Invoice Registration Portal (IRP) should I use?

A: Several government-authorised IRPs are available, including NIC’s portal and other authorised providers. Most businesses use whichever IRP their accounting software or ERP integrates with directly.

Q: Is a 6-digit HSN code mandatory for e-invoices?

A: Businesses above INR 5 crore turnover are required to use a minimum 6-digit HSN code at the item level; businesses at or below that threshold can use 4-digit codes.

Q: Does this affect my GST return filing directly?

A: Yes, indirectly a missing or invalid IRN can create inconsistencies between your e-invoice data and your GSTR-1 filing, which is exactly the kind of mismatch GSTN’s automated systems are now built to catch quickly.

Q: What if I’m not sure whether I’ve crossed the threshold in a past year?

A: This is worth a proper reconciliation rather than a guess, aggregate turnover has to be checked across every GSTIN under your PAN, across every year since 2017-18, which is easy to get wrong without a documented review.

×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesGST SBC

Common GST Compliance Mistakes That Trigger Tax Notices in 2026

India Union Budget 2026-27

Home > Common GST Compliance Mistakes That Trigger Tax Notices in 2026

Common GST Compliance Mistakes That Trigger Tax Notices in 2026 (And How the AI-Matching System Catches Them)

GST compliance in India no longer depends on whether a tax officer happens to review your filings. The GSTN portal now crossmatches your GSTR-1, GSTR-3B and GSTR-2B data against e-invoices, banking records and income tax filings in real time. A mistake that might have gone unnoticed for months a few years ago can now trigger a system-generated notice within days, requiring no human intervention. For businesses operating across multiple states or scaling quickly enough that manual reconciliation can’t keep pace, this shift changes what “staying compliant” actually means.

The good news is that most of the mistakes behind these notices are entirely avoidable once you know what to look for. In this guide, we’ll walk through the most common GST compliance errors we see businesses make, explain exactly how the automated matching system catches each one, and show you which notice type each mistake typically leads to so you can fix the gap before it becomes a compliance problem.

Why GST Mistakes Get Caught Faster Than Ever in 2026?

The GST system has moved from periodic manual scrutiny to continuous automated validation. Every return you file is checked against multiple data sources simultaneously: your outward supplies in GSTR-1 against the tax paid in GSTR-3B, your Input Tax Credit claims against your suppliers’ GSTR-2B filings, your e-invoice IRN data against your reported turnover, and increasingly, your GST records against your income tax and banking data.

In practice, this means the GSTN portal doesn’t need an officer to decide to investigate you. The moment a discrepancy crosses a threshold, the system flags it and can issue a notice automatically. This is exactly why understanding the mistakes below and fixing them at the source matters more in 2026 than it ever has before.

Nine (9) Common GST Compliance Mistakes That Trigger Notices

  1. GSTR-1 vs. GSTR-3B mismatches: Reporting different sales figures in your outward supply return (GSTR-1) than the tax you actually pay in GSTR-3B is one of the fastest ways to trigger scrutiny. This often happens innocently, a sales return recorded in your books one month but reflected in GSTR-1 the next but the system doesn’t distinguish intent from timing gaps.

Why it gets caught: the GSTN portal reconciles these two returns automatically every cycle.

Where it leads: this is the classic trigger for an ASMT-10 scrutiny notice, which requires a reply within approximately 15 to 30 days.

  1. Claiming ITC without reconciling GSTR-2B: Many businesses still claim Input Tax Credit based on their own purchase register rather than what appears in GSTR-2B. Following the introduction of the Invoice Management System (IMS) during the year 2024-2025, the acceptance, rejection or pending status of invoices and Credit Notes must be actively managed to streamline and generate your valid GSTR-2B. If your supplier delays uploading an invoice or enters your GSTIN incorrectly, that credit simply won’t reflect on your side, regardless of whether you genuinely paid the tax.

Why it gets caught: ITC claims are validated against supplier-side filings, not your internal records.

Where it leads: an automated demand for credit reversal, often with 18–24% interest depending on how the discrepancy is classified.

  1. Incorrect or outdated HSN/SAC codes: Since the GST 2.0 rate restructuring took effect from September 2025, most goods and services now fall under a simplified three-rate structure of 5%, 18%, or 40%. Businesses still using pre-restructuring codes or rates risk under- or over-charging tax without realizing it.

Why it gets caught: the system performs sectoral rate benchmarking using HSN-level data.

Where it leads: a demand notice for the tax shortfall plus interest, and in repeated cases, closer scrutiny of your entire invoicing pattern.

  1. Missing the e-invoicing threshold: E-invoicing thresholds have been progressively lowered, pulling many more MSMEs into the mandatory net than in previous years. Businesses that assume e-invoicing is only for large corporates often continue issuing traditional invoices without realizing they’ve crossed the applicable turnover limit.

Why it gets caught: non-compliant invoices are structurally rejected by buyers’ ITC systems, which surfaces the gap quickly.

Where it leads: invoices deemed invalid for credit purposes, plus compliance queries about the oversight itself.

  1. Delayed GST registration: Some businesses underestimate how quickly they cross the mandatory registration threshold, particularly when interstate supplies are involved. Assuming only local turnover counts is a common and costly miscalculation.

Why it gets caught: The GSTN now cross-references turnover data with income tax and banking records. Furthermore, with the deployment of the upgraded Aggregate Annual Turnover (AATO) functionality from 1st July 2026, the portal automatically updates AATO as subsequent returns are filed post-amendment window, making delayed registration and turnover mismatches highly visible.

Where it leads: retroactive tax liability and interest calculated from the date registration was due, not the date it was obtained.

  1. Ignoring Reverse Charge Mechanism (RCM) obligations: Certain transactions require the recipient, not the supplier, to pay GST directly. Businesses frequently overlook RCM liability on specific categories of purchases, assuming the supplier has already accounted for it.

Why it gets caught: unpaid RCM liability shows up as a gap between expected and reported tax payments.

Where it leads: interest on the unpaid amount and, in some cases, a formal notice questioning the omission.

  1. Inconsistent details across GST, Income Tax, and banking records: Turnover, address, or bank account details that don’t match across different government portals are a red flag the system is specifically designed to catch.

Why it gets caught: automated cross-referencing between GST, income tax, and banking data is now standard practice, not an exception.

Where it leads: in serious cases, this can be treated as suppression of turnover under Section 122 of the CGST Act, a much more serious position than a simple clerical error.

  1. Rushing or skipping annual return (GSTR-9) reconciliation: The annual return is often treated as a formality rather than a genuine reconciliation exercise. Discrepancies that were manageable at the monthly level can compound into a larger, harder-to-explain gap by year-end.

Why it gets caught: GSTR-9 data is checked against the full year’s monthly filings in aggregate, surfacing patterns that individual months might not reveal.

Where it leads: a notice questioning the full-year figures, which is typically more complex to resolve than a single-month discrepancy.

  1. Ignoring a notice or missing the reply deadline: Even businesses that make relatively minor mistakes can turn them into serious problems simply by not responding on time. GST notices come with strict windows often 7 to 30 days and missing one can trigger GSTIN suspension or a best-judgment assessment where the officer decides your liability without your input.

Why it gets caught: this isn’t a detection issue but an escalation one, the system automatically enforces deadlines. For a full breakdown of notice types, reply to forms, and timelines, see our complete guide to responding to a GST notice.

The 2026 Rule Changes Businesses Often Overlook

A few regulatory shifts from the past year deserve particular attention, since they change what “compliant” looks like:

  • GST 2.0 rate restructuring (effective September 2025): the shift to a simplified 5%/18%/40% slab structure means HSN/SAC accuracy matters more than ever, codes and rates that were correct before the restructuring may no longer be.
  • The three-year filing hard stops: if a return remains unfiled for more than 36 months, the GST portal permanently blocks it. This removes the option of “catching up later” that many businesses previously relied on.
  • Lower e-invoicing thresholds: turnover limits for mandatory e-invoicing have continued to drop, bringing a much wider band of MSMEs into scope, often without those businesses realizing the threshold has changed.

A Simple Monthly Checklist to Stay Ahead of GST Notices

  • Reconcile GSTR-2B before finalizing any ITC claim for the period
  • Cross-check GSTR-1 against GSTR-3B every single filing cycle, not just at year-end
  • Verify HSN/SAC codes and rates against the latest GST Council notifications
  • Confirm whether e-invoicing thresholds apply to you each financial year, not just once
  • Keep PAN, address, and turnover details consistent across the GST portal, income tax records, and banking details
  • Treat every notice as urgent — even a minor one — and respond well within the deadline

Why These Are Rarely Cases of Fraud — And Why That Still Matters

Most of the mistakes above don’t originate from an intent to evade tax. They come from disconnected systems, delayed reconciliation or simply not knowing a rule changed. We worked with a mid-sized manufacturing client who had been flagged for a GSTR-1/3B mismatch stretching back two quarters. On review, the gap traced entirely to a timing difference in how sales returns were being booked, not any attempt to understate liability. Because the discrepancy was caught and explained proactively, with clear reconciliation records, the matter was resolved without escalating into a formal demand.

That distinction—a genuine process gap versus a deliberate misstatement—matters enormously in determining how a case unfolds if it reaches the notice stage. However, the preferable position is to avoid having to make that argument in the first place.

When to Bring in a GST Advisory Team

Businesses with multi-state operations, high transaction volumes, cross-border supply chains, or a history of recurring notices tend to benefit most from a structured compliance review rather than reactive, notice-by-notice firefighting. A periodic health check such as  reconciling returns, verifying ITC eligibility,and confirming HSN and threshold accuracy is almost always less costly than responding to a notice after the fact.

Our GST Advisory and Corporate Compliance teams at Steadfast Business Consulting regularly help businesses build exactly this kind of proactive compliance framework.

Frequently Asked Questions

  • What is the most common reason for a GST notice in India? Mismatches between GSTR-1 and GSTR-3B are among the most frequent triggers, since the GSTN portal reconciles these two returns automatically every filing cycle.
  • Can a small mismatch in GSTR-1 and GSTR-3B lead to a notice? Yes. Even minor timing differences, such as a sales return booked in a different month than it’s reported, can trigger an automated scrutiny notice under the current matching system.
  • What happens if I claim ITC not reflected in GSTR-2B? The credit is likely to be disallowed, and you may face a demand for reversal along with interest, since GSTR-2B is the primary document the system uses to validate eligible ITC.
  • Is e-invoicing mandatory for all businesses in 2026? Not for all businesses, but the applicable turnover threshold has been lowered progressively, so many mid-sized businesses that were previously exempt may now be required to comply.
  • What is the GST three-year filing block introduced in 2026? As of January 2026, any GST return left unfiled for more than 36 months is permanently blocked on the portal, removing the option to file it later.
  • How can I avoid GST notices proactively? Regular reconciliation of GSTR-1, GSTR-3B, and GSTR-2B, accurate HSN/SAC classification, and consistent records across GST, income tax, and banking data are the most effective ways to reduce notice risk.

Key Takeaways: Avoiding GST Notices in 2026

Most GST notices don’t originate from fraud — they come from mismatches, missed thresholds, and reconciliation gaps that the GSTN’s automated system now catches almost immediately. Understanding which mistakes matter most, and fixing them at the source, is far more effective than responding to notices as they arrive.

If your business would benefit from a proactive GST compliance review, our advisory team at Steadfast Business Consulting can help you identify and close these gaps before they turn into a notice.

×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesGST SBC

How to Respond to a GST Notice in India (2026 Guide): Section 74A, Timelines & Reply Format

India Union Budget 2026-27

Home > How to Respond to a GST Notice in India (2026 Guide): Section 74A, Timelines & Reply Format

How to Respond to a GST Notice in India (2026 Guide): Section 74A, Timelines & Reply Format

GST compliance in India has quietly become a data-matching exercise rather than a paperwork one. Between GSTR-1, GSTR-3B, e-way bill records and ICEGATE export data, the GSTN / GST Portal systems now flag mismatches automatically, often before a human officer even looks at the file. For startups and SMEs juggling multiple compliance deadlines, and for larger businesses operating across states or borders, this means a GST notice can land even when nothing was intentionally wrong like a mismatched invoice, a delayed return, or an input tax credit claim that doesn’t quite reconcile is often enough to trigger one.

This is exactly why knowing how to respond to a GST notice has become a core business skill, rather than just a task for the tax team. In this guide, we’ll walk through the different types of GST notices you might receive, the newly consolidated Section 74A framework that now governs all notices from FY 2024-25 onward, the exact reply process on the GST portal, and the mistakes that turn a routine query into a prolonged dispute. By the end, you’ll know exactly what to do the moment a notice lands in your GST portal inbox.

What Is a GST Notice and Why You Received One

A GST notice is a formal communication from the GST Authorities asking a registered taxpayer to explain a discrepancy, provide additional documents or respond to an allegation of non-compliance. It is not, by itself, a finding of guilt it’s the authorities way of giving you a chance to clarify your position before any penalty or demand is finalized.

Notices are typically triggered by:

  • Return mismatches: differences between GSTR-1, GSTR-3B and e-way bill data
  • Input Tax Credit (ITC) discrepancies: claiming more credit than supporting invoices justify
  • Late or non-filing of periodic returns
  • Export data mismatches: shipping bill details not reflected in GSTR-1
  • Registration-related issues: incomplete documentation or address verification during registration or amendment

Understanding why you received a notice is the first step to responding correctly, because each trigger maps to a different notice type and each notice type has its own form, deadline and reply format.

Types of GST Notices and Their Reply Forms

Different notices are issued under different provisions of the CGST Act, and each requires a specific reply form within a specific window. Here’s a quick-reference table:

Notice Received Reason Reply Form Typical Time Limit
REG-03
Additional documents needed during registration
REG-04
7 working days
REG-17
Show cause before registration cancellation
REG-18
7 working days
ASMT-10
Scrutiny discrepancy in returns
ASMT-11
As specified in notice (usually 15 – 30 days)
DRC-01 / DRC-01A
Show cause Notice/ pre-show-cause intimation
DRC-06
As specified in notice
Section 46 reminder
Non-filing of returns
File pending returns
15 days

Getting the reply form right matters as much as getting the content right, a well-drafted response filed on the wrong form can be treated as no response at all.

The Big 2026 Change: Section 74A Explained

If there’s one development every business owner should understand this year, it’s this: notices under the old Sections 73 and 74 can no longer be issued for FY 2024-25 and beyond. Both provisions have been consolidated into a single new provision, Section 74A, which now governs all GST demand notices going forward regardless of whether fraud is alleged or not.

Previously, Section 73 covered genuine short-payment or ITC errors (lower penalty exposure, up to 10%), while Section 74 covered cases involving fraud or wilful misstatement (penalty exposure up to 100%). Under Section 74A, both scenarios are addressed within the same section, but the facts of the case still determine which penalty band applies. This distinction matters enormously a notice alleging fraudulent intent without solid evidence can sometimes be successfully argued down to the lower penalty category, which is why correctly reading the allegation, not just the form, is critical.

The other meaningful change: the window to pay the demanded tax and interest at the reduced penalty rate has been extended from 30 days to 60 days, giving businesses more breathing room to settle straightforward cases before they escalate.

Section 73 vs Section 74 vs Section 74A at a glance:

  • Section 73 (pre-FY 2024-25): tax unpaid, short-paid, erroneously refunded, or ITC wrongly availed/utilised for reasons other than fraud, wilful misstatement, or suppression
  • Section 74 (pre-FY 2024-25): short-payment or wrong ITC availment is by reason of fraud, wilful misstatement, or suppression of facts to evade tax
  • Section 74A (FY 2024-25 onward): single provision, penalty band depends on facts, not the section number.

In practice, we’ve seen businesses receive a notice framed as a serious allegation when the underlying facts were closer to a genuine clerical mismatch. One SME client in the FMCG sector, for instance, received a notice alleging wilful ITC misstatement based purely on a timing gap between two return periods. On review, the discrepancy was traced to a genuine reconciliation lag rather than any intent to misstate, and the matter was resolved without escalation once the correct evidentiary position was presented. Getting an experienced GST advisor to assess which category truly applies before drafting any reply is often the single most consequential decision in the entire process.

Step-by-Step: How to Reply to a GST Notice on the Portal

Once you know what type of notice you’ve received, the actual filing process is fairly consistent:

  1. Log in to the GST portal and go to Services → User Services → View Notices and Orders.
  2. Download the original notice in PDF to confirm the exact section, form, and deadline.
  3. Identify the correct reply form based on the notice type (see the table above).
  4. Draft your reply point by point i.e., address every allegation raised; an unaddressed point can be treated as accepted.
  5. Attach all supporting documents you reference invoices, reconciliation statements, ledgers, or bank records.
  6. Submit using your Digital Signature Certificate (DSC) or Electronic Verification Code (EVC).
  7. Save the acknowledgement reference number — this is your proof of timely filing and should be retained indefinitely.

For notices from enforcement wings such as DGGI or the Anti-Evasion unit, a physical reply to the issuing office may be required in addition to the portal submission, always check the specific instructions on the notice itself.

Need a starting point? Our GST Advisory team can share a ready-reference reply format aligned to your specific notice type — get in touch and we’ll help you structure it correctly the first time.

What to Include in a Strong GST Notice Reply

The difference between a reply that closes a matter and one that invites a follow-up to notice usually comes down to a few habits:

  • Be factual, not emotional. Be factual and detailed. Explain the product or service in question, discuss the relevant Chapter Notes, and quote judicial precedents or HSN references.
  • Address every point raised. Go through the notice line by line; silence on any point can be read as agreement.
  • Attach everything you reference. An incomplete reply is often treated as no reply. Use Calculation Tables for valuation, tax calculations or GSTR-1 vs GSTR-3B / ITC mismatches, summarize discrepancies in a clear table within the reply
  • Use Annexures. Keep the main response uncluttered by placing case laws, HSN schedules, or wide ITC tables in structured annexures
  • Avoid voluntary admissions. Don’t concede liability in your language unless you’ve independently verified the claim and intend to settle.
  • Maintain a reply log. Track every notice, response date, acknowledgement number and outcome, this record becomes invaluable during future assessments or audits.

Common Mistakes Businesses Make When Responding:

Even well-intentioned businesses tend to repeat the same errors:

  • Ignoring smaller notices, assuming they’ll be overlooked, they rarely are.
  • Filing a generic or partial reply instead of addressing each specific allegation.
  • Using the wrong reply form, which can invalidate an otherwise sound response.
  • Treating a Show Cause Notice casually, without recognizing it as a formal legal document with real consequences.
  • Not seeking expert review on Section 74A notices before replying, especially where fraud is alleged but the underlying facts suggest a genuine error.

What Happens If You Miss the Deadline or Ignore the Notice

Non-response doesn’t make a notice go away, it escalates it. Repeated non-compliance or failure to respond to intimations and Notices can lead to:

  • Best-judgment assessment for non-filers under Section 62 or unregistered persons under Section 63, which start with a non-obstante clause overriding Sections 73, 74, and 74A
  • Suspension or cancellation of GST registration
  • Blocking of e-way bill generation, disrupting the ability to move goods
  • Recovery proceedings under Section 79, including attachment of bank accounts
  • Prosecution under Section 132 in cases of wilful evasion

If a deadline is missed for a genuine reason, an application for restoration of proceedings or Adjournment request may be possible for certain notice types but this depends on the officer’s discretion and requires a well-documented justification, making early professional input valuable even after a deadline has slipped.

When You Need Professional Help

Some notices are straightforward enough to handle internally, a simple clarification query during registration, for instance. But once a notice involves a demand under Section 74A or a significant financial exposure, the framing of your reply can materially change the outcome. This is where an experienced GST advisory team adds real value, assessing whether the allegation is legally sound, identifying whether a case has been miscategorized, and ensuring the reply is built on a defensible factual and legal position rather than just procedural compliance.

At Steadfast Business Consulting, our GST Advisory and Legal Services teams regularly assist businesses in reviewing notices, assessing exposure, and drafting responses that hold up to scrutiny particularly where the newer Section 74A provisions are involved.

Key Takeaways: Responding to a GST Notice the Right Way 

A GST notice is manageable when you know what you’re looking at. Identify the notice type correctly, respond within the stipulated timeline, use the right reply form, and keep your response factual and well-documented. The introduction of Section 74A has changed how demand notices are framed and understanding where your case truly falls — a genuine error or a more serious allegation — can significantly affect the outcome.

If your business has received a GST notice, or you’d simply like a compliance health check before one arrives, our GST Advisory team at Steadfast Business Consulting is available to review your position and guide your response.

Frequently Asked Questions

  • What is the time limit to reply to a GST notice? It depends on the notice type. Registration-related notices (REG-03, REG-17) typically require a reply within 7 working days, while scrutiny and demand notices (ASMT-10, DRC-01) usually specify 15–30 days. Always check the exact deadline stated on your notice.
  • What happens if I don’t reply to a GST show cause notice? The authorities can proceed to pass an order based on the allegations in the notice, which may include a tax demand, penalty, registration cancellation, or recovery action, all without your side of the case being considered.
  • What is the difference between Section 73, Section 74 and Section 74A? Section 73 and Section 74 were separate provisions for non-fraud and fraud cases respectively, applicable up to FY 2023-24. From FY 2024-25 onward, both have been merged into Section 74A, with the applicable penalty still depending on whether fraud or wilful misstatement is established.
  • Can I reply to a GST notice after the deadline? In some cases, a delayed reply or a restoration or Adjournment application may be accepted if there’s a valid reason, but this is at the officer’s discretion and is far less reliable than relying on time.
  • Which form is used to reply to a GST demand notice? Demand notices issued under DRC-01 or DRC-01A are typically replied to using Form DRC-06 on the GST portal.
  • Is a notice invalid if it wasn’t served through the GST portal? Not necessarily, the CGST Act recognizes several valid modes of service, including hand delivery, registered post, and in limited cases, public notice methods. The portal is simply the most common and convenient channel.
×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesGST SBC

Year-end GST Checklist Steps to Smooth Transition

Year-end GST Checklist Steps to Smooth Transition

Home > Year-end GST Checklist Steps to Smooth Transition

Year-end GST Checklist Steps to Smooth Transition

As FY 2024-25 ends, ensure a seamless transition to FY 2025-26 with these essential GST tasks.

I. Outward Supplies: Get Your Records in Order

  • Reconcile GSTR 1 with GSTR 3B & GST Returns with Books of accounts and rectify any mismatches between books and filed returns.
  • Reconciliation of “E-Invoice and E-way bills” generated with actual sales
  • Check applicability of E-Invoice
  • From February 2025, reporting 6-digit HSN codes via dropdown is mandatory, as manual entry is disabled. The HSN master description will auto-fill the “Description as per HSN Code” field.
  • Ensure shipping bill details for the export of goods with payment of tax are correctly entered in GSTR-1 and transmitted to the ICEGATE portal for IGST refund claims.
  • Ensure all credit/debit notes are issued and reported in GSTR-1
  • Ensure tax liability against receipt of advances (services) and adjustment thereof to derive at unadjusted advances
  • Ensure correct bifurcation of B2B and B2C transactions in GSTR-1
  • In case of the export of goods/services without payment of tax, make sure to file application for LUT for FY 2025-26 on or before 31st March 2025.
  • Check tax compliance on branch/stock transfers
  • Ensure correct reporting of Taxable, Exempt, Non-GST and Nil-rated supplies
  • Verify if any corrections/amendments in invoices or details are required

II. Input Tax Credit (ITC) & RCM

1.Reconciliation of Input Tax Credit (ITC) as per Books and GSTR 3B:

While filing GSTR-3B as per Circular 170 of CGST Act and claiming ITC recorded in books and matched with GSTR-2B, it is essential to verify any discrepancies at the year end, such as:

  • ITC matched with GSTR 2B but missed to claim in GSTR-3B
  • ITC reversed in Table of Permanent Reversal [4(B)(2)] instead of Temporary Reversal [4(B)(1)] in GSTR 3B
  • RCM ITC wrongly reported in Regular ITC
  • Interchange claims of SGST /CGST as IGST and vice versa, etc

Note: Any such correction/ claim shall be made up to the October month return filed by 30th November of the subsequent Financial Year or filing of annual return, whichever is earlier.

2. Other Important points to check under ITC are:

Other Important points to check under ITC

Note: Rule 37 – Check for ITC reversal required on account of non-payment to vendors within 180 days or reclaim of any ITC in respect of supplies for which payment has been made.

3. Reverse Charge Mechanism (RCM):

• Reconcile expenses attracting RCM with amounts reported in GSTR-3B and books.

• Ensure GST is paid on RCM basis for imports of goods/services.

• Claim eligible ITC in GSTR-3B by November 30th of the following financial year or before filing of the annual return, whichever is earlier.

• Ensure correct reporting, payment and claiming of RCM in GSTR-3B.

III. Rule 96A Compliance (Exports under LUT/Bond)

1. Goods must be exported within 3 months from the invoice date.

2. Payment for export of services must be received in convertible foreign exchange/INR (as per RBI) within 1 year [or the period allowed under FEMA (9 months), including extensions] from the invoice date.

3. Regularly review compliance for each invoice; ensure no defaults before Financial Year ends.

4. Refund Timeline-

• Refund applications must be filed within 2 years from the relevant date as per the act.

• It may be noted that it is a regular activity to ensure that the refund is claimed periodically.

However, we shall check the same at the end of FY to plug any gap and apply for refund without any default.

IV. Other Compliances

  • If the conditions of Rule 86B are met, ensure that at least 1% of the total tax liability is paid in cash.
  • Obtain declarations from vendors exceeding the prescribed aggregate turnover threshold but exempt from e-invoicing under clause (s) of Rule 46.
  • Check for any GST TDS/TCS credit available on our GST Portal and claim the same after checking its authenticity from the books of accounts
  • Ensure registered persons with turnover up to ₹5 Cr opt in/out of the QRMP Scheme on time for seamless tax compliance
  • If opted for the Composition Scheme for FY 2025-26, ensure Form CMP-02 is filed by March 31, 2025.

Note:

1. Check whether the material sent for job work has been returned within the prescribed time limit (i.e. for Inputs – 1 year and for Capital goods – 3 years) and whether the same has been duly reported in ITC 04.

2. Ensure that goods sent on an approval basis are either returned within six months or sold with the issuance of a tax invoice to comply with regulations.

V. Credit Note Declaration Compliance

As per reference vide Circular No.-212/6/2024-GST-

Ensure that if the discount given by the supplier to a recipient through tax credit notes in a Financial Year exceeds ₹5,00,000/-, then the supplier must obtain a CA/CMA certificate from the recipient confirming ITC reversal.

If the discount given by the supplier to a recipient through tax credit notes in a Financial Year is up to ₹5,00,000, a self-declaration from the recipient is sufficient.

Note: To avoid a last-minute rush during assessments, it is advisable to maintain these documents for scrutiny, audit, or investigation.

VI. Input Service Distributor (ISD) Registration Requirement

(Effective from 01 April 2025)

Applicability

  • Any office of a supplier of goods or services or both that receives tax invoices for input services on behalf of distinct persons under Section 25.
  • It also includes invoices subject to reverse charge tax.

Mandatory Registration

  • Entities meeting the above criteria must register as an ISD under GST.
  • The ISD will distribute Input Tax Credit (ITC) in respect of such invoices to the respective recipients.

Action Required

  • Identify such offices/ entities on or before 31st March 2025.
  • Apply for ISD registration to comply with the new mandate.
  • This ensures proper ITC distribution and compliance with GST laws.

VII. The Hotel Industry!

Two major notifications were issued on 16th January 2025, impacting GST compliance for hotels and restaurants from 1st April 2025. Key changes as per notification no. are as follows-

Notification No. 05/2025 – CT (Rate)

Introduction of the “Specified Premises” concept (Hotels with high-value accommodations).

Removal of the “Declared Tariff” concept (Earlier tariff-based taxation is removed).

Mandatory Opt-In/Opt-Out Declaration before 31st March 2025.

Notification No. 08/2025 – CT (Rate)

E-Commerce Operators (like Swiggy, Zomato) will no longer be liable to pay GST on restaurant services provided in “Specified Premises”.

GST liability will now shift to restaurant owners, and they must pay 18% GST with Input Tax Credit (ITC) benefits.

Note-

What are “Specified Premises”?

1. Any hotel or restaurant where room rent exceeded ₹7500 per day in the previous financial year.

2. Any new hotel registering as a Specified Premises must file an Opt-In form (Annexure VII, VIII, IX).

Revised GST Rates from 1st April 2025

  • Standalone Restaurants (Not attached to any hotel) – 5% GST (No ITC)
  • Restaurants in Specified Premises (₹7500+ per day hotel rooms – 18% GST (ITC allowed)
  • Restaurants in hotels with room rent below ₹7500 per day – 5% GST (No ITC)

Important Notes:

  • Hotels falling under “Specified Premises” must file Opt-In Declaration (Annexure VII) before 31st March 2025.
  • New GST registrations must file Annexure VIII within 15 days of ARN generation.
  • For opting out, hotels/restaurants must file Annexure IX
  • Once an option is selected, it cannot be changed for the financial year unless an Opt-Out Declaration is filed.