Parent Guarantee of an Indian Subsidiary: How Transfer Pricing, Withholding and GST Fit Together
By CA Mithilesh Reddy, Founder and CEO, and CA Rajesh Vaishnav, Partner, Steadfast Business Consulting LLP | Direct Tax Advisory
Quick answer
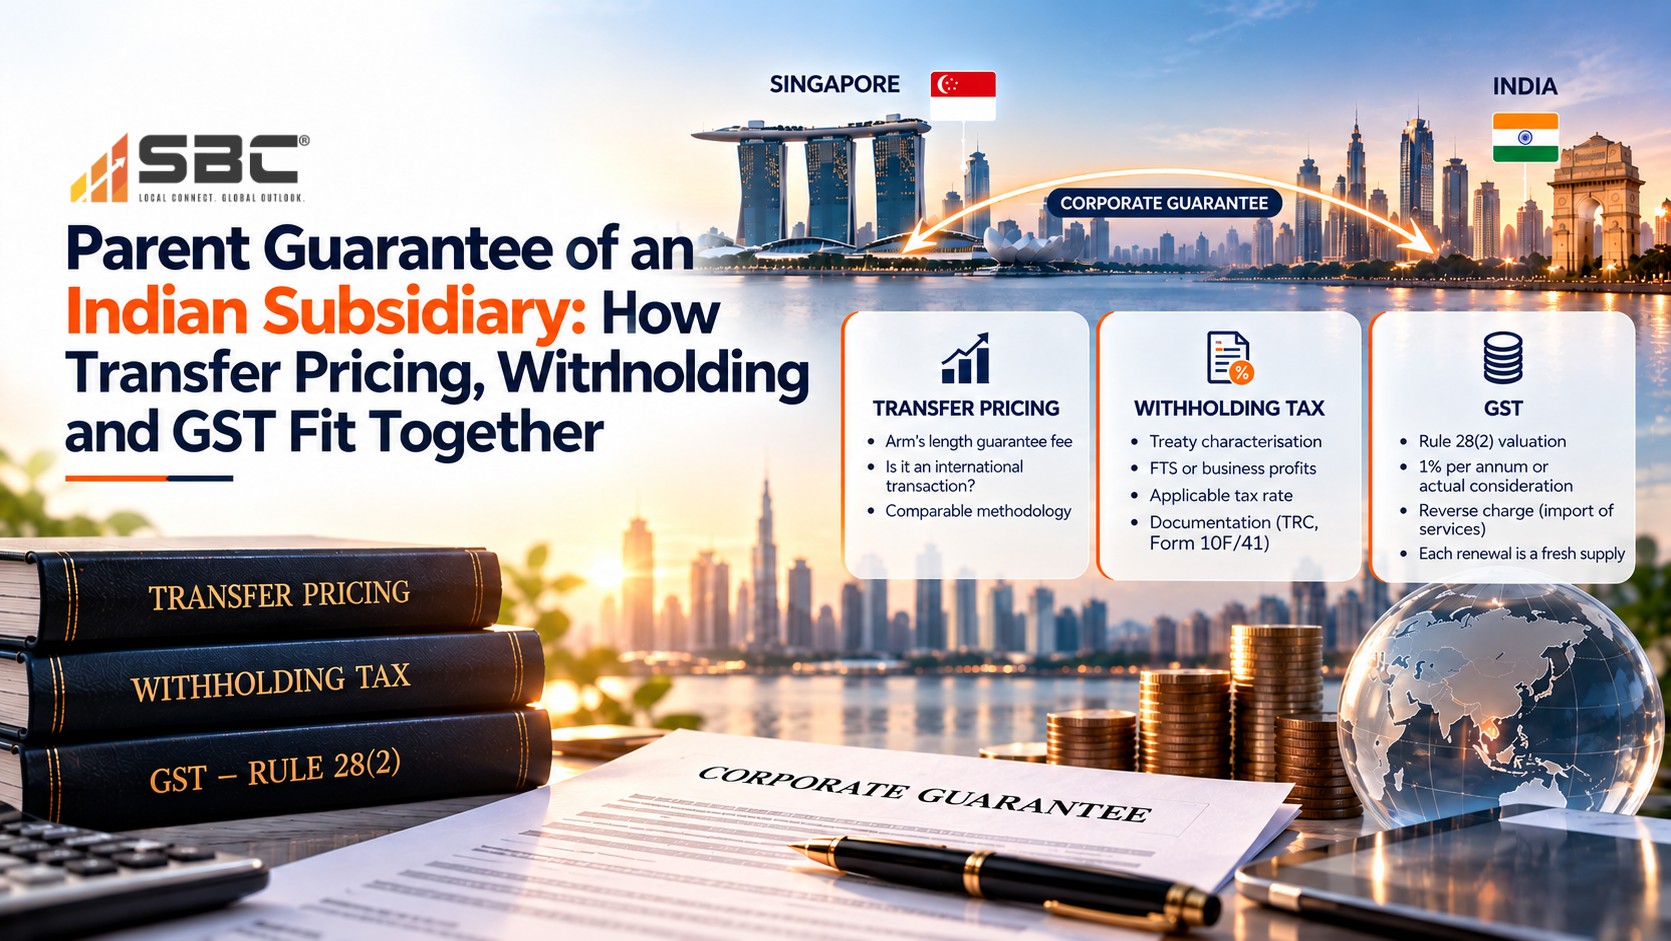
A parent guarantee of an Indian subsidiary’s borrowing engages three Indian regimes at once. Transfer pricing asks what an independent guarantor would charge. Withholding asks how any fee is characterised under the treaty. GST ordinarily values a covered guarantee under Rule 28(2) at one per cent of the amount guaranteed per annum, or actual consideration if higher, subject to the full-input-tax-credit invoice-value proviso.
Key takeaways
- A parent guarantee of an Indian subsidiary’s borrowing engages transfer pricing, treaty withholding on any fee and GST valuation separately; each regime reaches its own number, and the three positions should be reconciled in one note.
- Whether a guarantee is an international transaction is contested: Bharti Airtel (Delhi Tribunal, March 2014) and Micro Ink (Ahmedabad Tribunal) support a no-bearing argument, while Advanta India (Bangalore Tribunal, 30 June 2015) treats a guarantee that costs the assessee as within the provision.
- The one per cent guarantee fee applied by transfer pricing officers is an administrative convention; in Everest Kanto (Bombay High Court, 8 May 2015) the Court dismissed the Revenue’s appeal against deletion of an adjustment built on bank guarantee rates, but did not itself fix an arm’s length rate.
- Under Rule 28(2) of the CGST Rules, a related-party guarantee is valued at one per cent per annum of the amount guaranteed, or the actual consideration if higher, whether or not a fee is charged; each renewal is a fresh supply (Circular No. 225/19/2024-GST dated 11 July 2024).
- Metso Outotec (Kolkata Tribunal) is a treaty characterisation decision under Article 21 of the India-Finland treaty, not an authority on the arm’s length guarantee rate.
Practice illustration: Cross-border parent guarantee
Issue. A related-party guarantee required consideration of transfer pricing, treaty withholding and GST, each of which employs a different statutory test.
Approach. The advisory compared borrowing benefits, guarantee risk and contract terms, and evaluated GST treatment under Rule 28(2), including the full-input-tax-credit proviso where applicable.
Outcome. The engagement provided a documented benchmark and a reconciled compliance framework. It was an advisory result, not advance departmental approval or a judicial determination of the fee.
Practical lesson. A fee benchmark for income-tax purposes is not automatically the GST valuation base.
This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.
Introduction
A parent company that guarantees its subsidiary’s bank borrowing has done something commercially real. The lender’s risk is reduced, the subsidiary borrows on better terms than it could obtain alone, and the parent has assumed a contingent liability it did not previously carry. Indian tax law responds to that in three places at once, and the three do not coordinate with one another. Each asks its own question, each reaches its own number, and each carries its own penalty and interest consequences.
The commercial amounts involved are usually modest, but the exposure is not, because each regime carries its own penalty and interest consequences, and because a position taken in one regime becomes evidence in the others. Different transfer-pricing and GST values can be justified, but the GST computation must also test the full-input-tax-credit proviso to Rule 28(2) and the documentation for the particular guarantee.
This note deals with how the three fit together on a single guarantee. It covers whether the transaction requires arm’s length pricing at all, how a defensible fee is established and why the familiar one per cent figure is not a legal standard, how the fee is characterised for withholding under a treaty, and how the prescribed GST valuation operates on a related party guarantee whether or not anything is charged. It also explains why the transfer pricing conclusion and the GST figure can legitimately differ, which is the point on which files most often become internally inconsistent. For the related question of how intra group service charges are characterised for withholding, see our note on the make available test in shared services arrangements.
1. Is a guarantee an international transaction at all
Section 163 of the Income-tax Act, 2025 (section 92B of the 1961 Act, the meaning of international transaction) defines the transactions to which the arm’s length requirement attaches. The corresponding provision in the 1961 Act was expanded by the Finance Act 2012, with retrospective effect, by an Explanation that lists guarantees among capital financing transactions. The 2025 Act carries the same treatment forward, so a guarantee remains within the categories the provision names, and the argument described below is about whether naming is sufficient rather than about whether the category exists.
Whether that listing is sufficient by itself has been genuinely contested, and a blog that presents the area as settled will mislead.
In Bharti Airtel Ltd. v. ACIT, the Delhi Bench held in March 2014 that a transaction is an international transaction only if it has a bearing on the profits, income, losses or assets of the enterprise, that this requirement applies even to transactions named in the retrospective Explanation, that the impact must be real rather than contingent or hypothetical, and that the onus lies on the Revenue. On that reasoning a guarantee that costs the guarantor nothing falls outside the provision.
The Ahmedabad Bench reached a similar result in Micro Ink Ltd. v. ACIT, ITA No. 2873/Ahd/10, holding that a parent’s guarantee to its subsidiary is a shareholder activity in the nature of quasi capital rather than the provision of a service, and therefore outside the limb of the provision dealing with the provision of services.
The other line is at least as strong. In CIT v. Everest Kanto Cylinder Ltd., ITA No. 1165 of 2013, pronounced on 8 May 2015 by Dharmadhikari and A.K. Menon JJ, the Bombay High Court proceeded on the footing that the guarantee was within the provision and decided the case on benchmarking. In Advanta India Ltd. v. ACIT, IT(TP)A No. 1643/Ban/12, decided on 30 June 2015, the Bangalore Bench held that a guarantee involving a cost to the assessee does fall within the provision and distinguished Bharti Airtel on that basis.
The practical conclusion for an adviser is straightforward. Arguing that no international transaction exists is available on the right facts, particularly where the guarantee was given purely in a shareholder capacity and cost the guarantor nothing. It is not a position to build a compliance strategy on. Most groups should benchmark and document, and keep the threshold argument in reserve.
2. What an arm’s length guarantee fee looks like
Transfer pricing officers have historically applied a one per cent commission as a default. That figure is an administrative convention. It is not in the statute, it is not in the rules, and it has been displaced on evidence.
Everest Kento Cylinders is the authority that matters, and it should be stated precisely because it is often overstated. The Bombay High Court dismissed the Revenue’s appeal for want of a substantial question of law. It held that the transfer pricing officer’s comparison of a holding company’s corporate guarantee with commercial bank guarantee rates was not a comparison between like transactions, and that the commission the assessee had charged could not be called in question in the manner the officer had done. The Court declined to interfere with the deletion of the adjustment. It did not itself fix an arm’s length rate, and it did not hold that 0.5 per cent is the arm’s length rate. What it establishes is that the administrative benchmark can be displaced, and that bank guarantee pricing is the wrong comparable.
The reasoning matters more than any number. A bank issuing a guarantee is selling a product, carries regulatory capital against it and prices for profit. A parent guaranteeing its own subsidiary is protecting an investment it already owns. The two are not in the same market.
Two methodologies are used to displace the default, and they answer slightly different questions.
The benefit approach measures what the borrower gained. It compares the interest rate the subsidiary obtained with the guarantee against the rate it would have obtained on its own standalone credit profile, and treats some share of the saving as the arm’s length fee. Its strength is that it is grounded in an observable commercial benefit. Its weakness is the counterfactual rate, which has to be established rather than assumed, ideally from a bank’s own indicative pricing or from a credit assessment.
The expected loss approach measures what the guarantor assumed. It estimates the probability that the borrower defaults, estimates the proportion of exposure that would be lost on default, and derives the expected loss the guarantor has taken on. Its strength is that it prices the risk actually borne, which is what a guarantor would charge for. Its weakness is that each input requires support, and an unsupported default probability carries no more weight than a bare assertion.
Either approach can be defended. Neither can be defended as a conclusion without the working. The file should contain the credit analysis, the source of each input, the sensitivity of the result to the main assumptions, and the reason the chosen approach fits the transaction.
3. One further point on quantum: guaranteed versus drawn
A guarantee is frequently issued for a facility limit well above what the borrower actually draws. For transfer pricing, the better view is that the guarantor’s exposure is to the amount outstanding from time to time, and pricing on the drawn amount reflects the risk actually assumed. For GST, as set out below, the prescribed value is expressly tied to the amount guaranteed rather than the amount disbursed. The two regimes diverge on this point by design, and a file should say so rather than leave the inconsistency to be discovered.
4. Withholding on the fee
Where a fee is actually paid to the foreign guarantor, the payer must consider section 393(2), Table serial number 17 of the 2025 Act (section 195, withholding on sums payable to non-residents), and the treaty characterisation that determines the rate.
The characterisation question is live and has produced an important decision that is widely miscited. In Metso Outotec OYJ (earlier Outotec Oyj) v. Dy. CIT, (2023) 203 ITD 79 / (2024) 227 TTJ 715 (Kol Trib), the Kolkata Bench held that a corporate guarantee fee arose in India and was taxable as Other Income under Article 21 of the India Finland treaty, on the reasoning that giving the guarantee was a shareholder obligation protecting the subsidiary’s business interests rather than part of the guarantor’s regular business activity.
Two points about that decision. First, it is a treaty characterisation case. It is not a transfer pricing case, it decided nothing about benchmarking, and it laid down no arm’s length rate. It is cited for the latter proposition with some frequency and should not be. Second, its actual holding is adverse and important: where a guarantee fee is characterised as other income rather than business profits, a taxpayer relying on the absence of a permanent establishment to claim nil taxability may find that the article it is relying on does not apply.
The characterisation therefore has to be worked out against the specific treaty, and the analysis should address the residuary article, not stop at business profits. Where a fee is payable, the treaty documentation requirements apply in the usual way: residency certificate, Form 10F and a beneficial ownership declaration.
5. The GST position
Section 15(1) of the CGST Act values a supply at the transaction value where the supplier and recipient are not related and price is the sole consideration. Where they are related, value is determined under the rules.
Rule 28(2) was inserted by Notification No. 52/2023-Central Tax dated 26 October 2023 and retrospectively amended by Notification No. 12/2024-Central Tax dated 10 July 2024 with effect from 26 October 2023. Circular No. 225/19/2024-GST dated 11 July 2024 sets out how it operates. The points that matter commercially are these.
- The value is one per cent of the amount guaranteed per annum, or the actual consideration, whichever is higher. Where a fee is actually charged above that figure, the fee is the value.
- The base is the amount guaranteed, not the amount disbursed. A guarantee of a facility limit is valued on the limit.
- Rule 28(2) applies to guarantees issued or renewed on or after 26 October 2023. Guarantees issued before that date are valued under the pre-existing Rule 28.
- Each renewal is a fresh supply.
- For a multi year guarantee, the one per cent is multiplied by the number of years, tax is paid at issuance, and part years are pro-rated.
- Where the recipient is eligible for full input tax credit, the invoice value is deemed to be the value of supply.
- Co-guarantors: where the aggregate actual consideration exceeds one per cent of the guaranteed amount, that aggregate is the value; otherwise each pays on one per cent of the amount it guarantees.
- A loan takeover alone is not a taxable event unless a fresh guarantee is issued or an existing one renewed.
- Rule 28(2) does not apply where the recipient of the guarantee service is located outside India, so an outbound guarantee is outside it.
Where the guarantor is outside India and the recipient is the Indian subsidiary, the supply is an import of services and the Indian entity discharges tax under reverse charge. Where the Indian entity is eligible for full credit, the cash effect nets out, but the compliance is not optional and the credit depends on correct discharge and documentation.
6. Why the two references to one per cent are not the same figure
This is the point on which files most often become internally inconsistent, so it is worth stating plainly.
The transfer pricing one per cent is an administrative benchmark with no statutory basis, applied by officers in the absence of better evidence, and displaceable on evidence as Everest Kanto shows. The GST valuation mechanism is subject to the full-input-tax-credit proviso and is not displaced merely by demonstrating a lower arm’s-length fee by showing that an independent party would have charged less.
Accordingly, a defensible transfer-pricing fee can differ from the GST value calculated for the same guarantee, once the full-credit proviso and other applicable conditions have been considered. That is not an inconsistency. The transfer pricing file should record why, so that the GST position is not later produced as an admission that the arm’s length fee was one per cent.
7. A worked example
Assume a foreign related entity guarantees a borrowing facility for an Indian group company, with loan drawdowns differing from the face amount guaranteed. This example is hypothetical; the guarantee terms, eligibility for input tax credit and the documentation of any fee must be examined independently.
Transfer pricing. For periods governed by the Income-tax Act, 1961, the relevant accountant’s report is Form 3CEB under section 92E; tax years governed by the Income-tax Act, 2025 use section 172 and Form No. 48 under rule 85 of the 2026 Rules. Benchmark the transaction by reference to borrowing benefits and guarantee risk using independently sourced inputs. Neither a reported judicial percentage nor a GST percentage is a substitute for this exercise.
Withholding. Where a fee is paid, the treaty characterisation is worked out against the applicable agreement, addressing both the business profits article and the residuary article, with Metso Outotec noted as the reason the residuary article cannot be ignored. Treaty documentation is obtained before payment.
GST. For a covered related-party guarantee issued or renewed on or after 26 October 2023, apply Rule 28(2) and Circular No. 225/19/2024-GST, including the proviso deeming the invoice value to be the supply value where the recipient is eligible for full input tax credit. Otherwise, the prescribed base ordinarily depends on the amount guaranteed, not just the amount drawn; the guarantee term, renewal date, any reverse-charge liability and actual credit eligibility must be documented.
Consistency. A single note records all three positions, explains why the transfer pricing rate and the GST deemed value differ, and is retained in the file. It costs an hour and is worth considerably more than that at assessment.
8. Where these arrangements go wrong
First, no fee is charged and nothing is documented. The absence of a fee is a defensible position on the right facts, but it must be a reasoned position recorded at the time, not a gap.
Second, a rate is adopted without working. A file that states a rate of half a per cent and contains nothing behind it is in a worse position than one that adopts the default, because it has invited the question without answering it.
Third, the GST obligation is missed entirely. Rule 28(2) applies whether or not consideration is charged, and groups that charge nothing frequently assume there is nothing to value.
Fourth, renewals are not tracked. Each renewal is a fresh supply, and a guarantee rolled over annually generates an annual liability that is easy to overlook because nothing new appears to have happened.
Fifth, the base is wrong. GST is valued on the amount guaranteed. Computing it on the drawn amount understates the liability, sometimes by a wide margin where the facility limit is far above utilisation.
Sixth, the treaty analysis stops at business profits. Metso Outotec shows that the residuary article can apply, and a withholding position that has not addressed it is incomplete.
Seventh, the three positions are prepared by three teams and never reconciled. This is the most common failure and the easiest to fix.
9. A review checklist
- Identify every guarantee, letter of comfort and similar instrument given or received within the group, with issue date, term, amount guaranteed and amount drawn.
- Determine for each whether Rule 28(2) applies, by reference to the issue or renewal date against 26 October 2023.
- Compute the GST deemed value on the amount guaranteed, pro-rating part years and multiplying for multi year terms, and confirm the reverse charge discharge and credit position.
- Diarise renewals as fresh supplies.
- Benchmark the fee for transfer pricing using a documented benefit or expected loss analysis, with sources for every input.
- Record why the transfer pricing rate differs from the GST deemed value.
- Work out the treaty characterisation of any fee actually paid, addressing the residuary article.
- Obtain treaty documentation before payment.
- Report the transaction in Form 3CEB under section 172 (section 92E).
- Consider whether the shareholder activity argument is available on the facts, and record the position either way.
- Reconcile the transfer pricing, withholding and GST positions in a single note.
- Review the position at each renewal rather than treating the original analysis as permanent.
Practitioner’s perspective
Corporate guarantees are among the smallest transactions a group reports and among the most reliably mishandled, because they fall between three teams and nobody owns them. The tax cost of getting the fee wrong is usually modest. The cost of missing the GST valuation across several years, or of taking inconsistent positions that are then produced against each other, is not.
Two things are worth emphasising. The one per cent transfer pricing benchmark is an administrative convention and Everest Kanto shows it can be displaced on evidence, but only on evidence; an unsupported lower rate is worse than the default. And the prescribed GST valuation is ordinarily based on the guarantee amount rather than the drawn amount, subject to the full-credit proviso, and afresh on every renewal. Those three features between them account for most of the exposure we see.
Where a guarantee is already in place and none of this has been done, the right sequence is to establish the GST position first, because it accrues with time and interest runs, and then to build the transfer pricing file.
Direction of the guarantee: where Everest Kanto fits and where it does not
In Everest Kanto the assessee was an Indian holding company that charged its foreign subsidiary a commission of 0.5 per cent on a guarantee supporting the subsidiary’s bank borrowing, and the transfer pricing officer substituted three per cent by reference to commercial bank guarantee rates. That is an outbound guarantee: the Indian entity was the guarantor and the question was whether it had earned enough.
The facts in this article run the other way. A foreign parent guarantees an Indian subsidiary’s borrowing, so the Indian entity is the beneficiary and the question is whether it should pay a fee at all, and how much. The comparability reasoning transfers, because a holding company protecting an investment is not selling a bank product. The numerical result does not transfer: a 0.5 per cent rate accepted on one set of facts is not a benchmark for another. For an inbound guarantee the analysis should be built on the subsidiary’s own credit position and the borrowing cost it would have faced without the guarantee, which is why the benefit approach needs evidence of the standalone rate.
Frequently asked questions
1. Is a parent guarantee an international transaction requiring arm’s length pricing?
The position is contested. Bharti Airtel and Micro Ink support the view that a guarantee with no bearing on the guarantor’s profits, income, losses or assets falls outside the provision, treating it as a shareholder activity. Everest Kanto and Advanta India proceed on the footing that it is within. Most groups should benchmark and document, and keep the threshold argument in reserve.
2. Is the arm’s length guarantee fee one per cent?
No. One per cent is an administrative benchmark with no statutory basis. In Everest Kanto the Bombay High Court dismissed the Revenue’s appeal, leaving undisturbed the Tribunal’s deletion of an adjustment based on a three per cent rate derived from commercial bank guarantee pricing, which the Court held was not comparable to a holding company guarantee. It did not itself fix 0.5 per cent as the arm’s length rate.
3. What methodologies are used to price a guarantee?
The benefit approach, which measures the interest saving the borrower obtained and allocates a share of it, and the expected loss approach, which estimates the probability of default and the loss given default to price the risk assumed. Either is defensible with supporting work; neither is defensible as a bare conclusion.
4. Is GST payable where no guarantee fee is charged?
Yes. For covered related-party guarantees, Rule 28(2) specifies one per cent of the guaranteed amount per annum or actual consideration, if higher. Where the recipient is eligible for full input tax credit, the proviso deems the invoice value to be the value of the supply; that proviso must be tested separately.
5. Is GST valued on the amount guaranteed or the amount drawn?
On the amount guaranteed. Circular No. 225/19/2024-GST confirms that the value depends on the amount guaranteed, not the amount disbursed.
6. Does each renewal attract GST again?
Yes. Circular No. 225/19/2024-GST treats each renewal as a fresh supply. A guarantee rolled over annually generates an annual liability.
7. What about guarantees issued before 26 October 2023?
Rule 28(2) applies to guarantees issued or renewed on or after 26 October 2023. Those issued earlier are valued under the pre-existing Rule 28, though a renewal after that date brings the renewal within the new rule.
8. How is a guarantee fee characterised for withholding under a treaty?
It depends on the treaty. In Metso Outotec the Kolkata Bench held a guarantee fee taxable as other income under Article 21 of the India Finland treaty, on the basis that giving the guarantee was a shareholder obligation rather than part of the guarantor’s regular business. A withholding analysis that addresses only business profits is incomplete.
9. Does Metso Outotec establish an arm’s length guarantee rate?
No. It is a treaty characterisation case and decided nothing about benchmarking or rates. It is sometimes cited for a transfer pricing proposition it does not contain.
10. Can the transfer pricing rate and the GST value legitimately differ?
Yes. The transfer pricing rate is the arm’s length price established on evidence. The GST figure is a prescribed deemed value that applies regardless of what an independent party would have charged. The file should record why they differ so that the GST figure is not later treated as an admission.
11. Who pays GST on a guarantee given by a foreign parent to its Indian subsidiary?
The Indian subsidiary pays, under reverse charge, because the supply is an import of services from a related person outside India. Where it is eligible for full input tax credit, the invoice value is deemed to be the value of supply under the proviso to Rule 28(2), so the cash effect can net out, but discharge and documentation must still be correct.
12. Which section of the Income-tax Act, 2025 covers corporate guarantees as international transactions?
Section 163 of the Income-tax Act, 2025, titled ‘Meaning of international transaction’, which corresponds to section 92B of the 1961 Act. Its capital financing limb includes any type of long-term or short-term borrowing, lending or guarantee. Arm’s length pricing follows under section 165, documentation under section 171 and the accountant’s report under section 172.
13. Is tax deducted at source on a guarantee commission paid to a foreign parent?
Where a fee is actually paid to a non-resident guarantor, the payer must consider deduction under section 393(2) of the Income-tax Act, 2025 (section 195 of the 1961 Act). The treaty characterisation, including the residuary article, decides whether and how much tax is chargeable. Treaty documents should be obtained before payment.
Talk to SBC’s tax team
If a parent or group guarantee is already in place and the transfer pricing, withholding and GST positions have not been reconciled, SBC’s team can review the file and the sequence in which to address it. Explore our Income Tax services | Contact SBC
Related reading from SBC
- Shared Services from Singapore: Applying the ‘Make Available’ Test to Indian Withholding
- Employee Secondment and GST: Reading Northern Operating Systems with the CBIC Clarifications
- No FTS Article in the India-UAE Treaty: How Offshore Engineering Income Is Taxed in India
- Seconding Staff Between India and the UK: Employer, Permanent Establishment and Payroll Tax Are Different Questions
- More articles on the SBC blog
About the author
CA Mithilesh Reddy, Founder and CEO, Steadfast Business Consulting LLP, led the team that handled this engagement.
CA Rajesh Vaishnav is a Partner at Steadfast Business Consulting LLP. SBC provides direct and indirect tax, international tax and transfer pricing advisory and dispute support.
Disclaimer
This article is for general information and does not constitute professional advice. It reflects the law as understood at the date of publication and does not take account of later developments. Statutory references give the Income-tax Act, 2025 section with the Income-tax Act, 1961 section in brackets; section 536 preserves the 1961 Act for proceedings pending on 31 March 2026 and for earlier tax years. The transfer pricing treatment of guarantees is an area in which tribunal authority is divided, and outcomes turn on the specific facts and documentation. No reader should act on the basis of this article without taking advice on their own circumstances.