CategoriesIndirect Tax

Smart TVs, Digital Advertising and Cross-Border GST: Separate the Hardware from the Platform

Smart TVs, Digital Advertising and Cross-Border GST: Separate the Hardware from the Platform

By CA Mithilesh Reddy, Founder and CEO, and CA Rupesh Reddy, Steadfast Business Consulting LLP | Indirect Tax Advisory

Quick answer

Draw the goods flow, rights flow, services flow and payment flow separately. Hardware imports are examined under customs and applicable import IGST provisions; cross-border software and advertising arrangements require independent classification, place-of-supply and recipient-location analysis. Do not assume that every payment connected to a smart television has the same tax treatment.

Key takeaways

  • A connected TV business has several distinct flows (device import, software and IP rights, advertising inventory, campaign services and settlements), and each has its own supplier, recipient, place of supply and tax consequence.
  • Customs value of imported devices is the transaction value under section 14 of the Customs Act, 1962; royalties and licence fees are added under Rule 10(1)(c) of the Customs Valuation Rules, 2007 only if they relate to the imported goods and are paid as a condition of their sale.
  • Advertising services supplied across the border follow the recipient-location rule in section 13(2) of the IGST Act, and an Indian business buying from a foreign platform generally pays IGST under reverse charge under Notification 10/2017-Integrated Tax (Rate).
  • Since 1 October 2023 the definition of online information and database access or retrieval services no longer requires the service to be essentially automated with minimal human intervention, so bespoke digital services need a fresh look.
  • From 30 March 2026, omission of section 13(8)(b) of the IGST Act means intermediary status no longer moves the place of supply of cross-border services, though it still affects valuation and earlier periods.

Practice illustration: Separate tax treatment of imported devices and digital-platform revenue

Issue. A cross-border technology arrangement combined imported goods, software rights and digital advertising services.

Approach. The advisory mapped ownership, contracts, goods movements and cash flows separately for customs, GST and income-tax purposes.

Outcome. A tax and compliance architecture was implemented. It was advisory work, not a final customs valuation determination or GST assessment approval.

Practical lesson. Mapping the separate flows precedes classifying them.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

A connected television is sold as hardware, but it also sits within a continuing commercial ecosystem. Manufacturers, importers, operating-system owners, advertising platforms, content licensors, measurement providers and distributors may all earn revenue after the device is sold. Tax analysis built solely around the sale of the television misses most of that structure.

The practical problem is that connected-TV businesses do not supply one composite service merely because all revenues depend on the same screen. Import of devices, licensing of software, grant of advertising rights, campaign-management services, data analytics and settlement of revenue shares are capable of having different suppliers, recipients, places of supply and GST consequences.

This article sets out a transaction-first framework for mapping that ecosystem. It concentrates on the drafting and evidence choices required before agreements are executed, when the group can still separate the commercial rights clearly.

1. Begin with four maps, not an organisation chart

An ownership diagram shows which group company holds an entity, but not who supplies hardware, licensed rights or advertising inventory. Prepare four maps: physical movement of devices; ownership and use of operating-system or content IP; performance of advertising and analytics services; and payment and settlement routes.

The maps should identify each legal counterparty, contract, invoice, source of income and responsibility for performance. Tax positions that are correct under one flow can fail if the invoices and agreements implement a different flow.

2. Importation of television hardware

Customs value, applicable classification, import duties and import IGST depend on the goods actually imported and the relevant customs rules. Whether embedded software, licences or associated consideration must be examined for customs valuation is a fact- and instrument-specific question.

Do not add all subsequent platform revenue to imported-goods value, nor presume that no rights payment can ever be relevant. The contractual condition of sale, commercial relationship and valuation rules must be analysed using the import documentation and rights agreements.

3. Who supplies the advertising inventory?

An advertising group may sell ad slots on a connected-TV home screen, provide campaign placement services, supply analytics or merely arrange transactions between a brand and an overseas platform owner. Each structure affects the supplier and recipient determination under GST.

If an Indian company buys and resells advertising inventory on its own account, that differs from arranging an advertisement supplied by a foreign principal. The intermediary versus principal distinction should be established from contract rights, price-setting power and obligation to deliver the advertising. For supplies on or after 30 March 2026 the distinction no longer changes the place of supply of a cross-border service, because section 13(8)(b) of the IGST Act has been omitted by the Finance Act 2026, but it still matters for earlier periods and for the value on which tax is charged.

4. Digital services and OIDAR are not universal labels

Online information and database access or retrieval services are subject to specific definitions and rules. The fact that a service is delivered over the internet does not automatically bring every advertising, development, management or creative service into that category.

Identify whether the service is delivered over the internet or an electronic network and could not be supplied without information technology, who receives it, and whether a specific location or registration provision applies. Since 1 October 2023 the definition no longer requires the service to be essentially automated with minimal human intervention, and any unregistered recipient in India is a non-taxable online recipient. Digital advertising campaigns that include material bespoke work may require a more nuanced classification than standard platform access.

5. Place of supply should follow the actual contract

For cross-border services, section 13 of the IGST Act applies where the supplier or the recipient is outside India: the general rule in section 13(2) places the supply at the recipient’s location, and the exceptions (performance-based services, immovable property, events, online information and database access) sit in the other sub-sections. Where both parties are in India, section 12 applies instead. Depending on the nature of the supply, location of the recipient, physical performance or another statutory factor may be relevant. A foreign invoice address does not, by itself, prove a service is exported.

When a foreign platform charges an Indian entity, determine whether import-of-service conditions and reverse charge obligations are met. Where an Indian supplier bills overseas group companies, independently test all export-of-services conditions, including the recipient’s location and permitted receipt of payment.

6. Software rights and income-tax characterisation should align

GST classification and direct-tax treaty characterisation serve different legal purposes, but the underlying rights must be described consistently. Distinguish access to software or data from transfer of reproduction, adaptation or commercial exploitation rights.

Contracts should define licensed territory, access controls, sublicensing rights, permitted modifications and ownership of user data or advertising analytics. A generic “technology fee” invoice makes it harder to defend the substance in both withholding and indirect-tax reviews.

7. Advertising revenue shares and foreign exchange settlement

Revenue-sharing agreements should identify the original customer transaction, gross consideration, commissions, refunds, taxes, settlement currency and entity entitled to each amount. A revenue share is not necessarily the same as an agency commission or purchase of services.

Where balances are netted among group entities, analyse foreign exchange rules and maintain a reconciliation of settlement. Transfer pricing should also reflect which party controls monetisation, owns valuable platform rights and assumes advertising fill-rate or customer risk.

8. Input tax credit and allocation of common costs

An importer or domestic seller of devices may have credit on import IGST, logistics and other business inputs, subject to GST conditions. Platform-related services may support taxable, zero-rated, exempt or mixed activities. Eligibility and apportionment cannot be decided without examining the actual output supplies.

Maintain cost centres separating hardware, platform licences, domestic advertising, overseas supplies and shared overheads. An ERP mapped exclusively to hardware turnover can distort the input credit allocation for an increasingly service-driven business.

9. Build a contract pack that is tax-complete

Before commercial launch, review the purchase and distribution agreements, OS or IP licences, advertising inventory terms, revenue-share schedules, campaign-management agreements, data-processing clauses and settlement mechanisms as one package.

A practical sign-off matrix should record the supplier, recipient, description, location, GST treatment, import treatment if relevant, direct-tax withholding, TP policy, invoice owner and evidence needed. Changes to rights and funds flows should trigger an update to the matrix instead of a unilateral invoicing workaround.

Customs valuation of imported televisions and embedded software: the tests to run

For imported goods the value for customs duty is the transaction value under section 14(1) of the Customs Act, 1962, determined under the Customs Valuation (Determination of Value of Imported Goods) Rules, 2007. Where buyer and seller are related, Rule 3(3) allows the declared price to be accepted if the relationship did not influence it, or if the price closely approximates a test value, so a group importer should keep its transfer pricing evidence and its customs evidence side by side and make sure they tell the same story.

Payments outside the invoice price are added only on the tests in Rule 10(1). A royalty or licence fee is added under Rule 10(1)(c) if it relates to the goods being valued and the buyer must pay it, directly or indirectly, as a condition of the sale of those goods. Rule 10(1)(e) similarly reaches other payments made as a condition of sale. A fee for the operating system loaded on the device at import may therefore be addable if the importer cannot buy the television without taking the licence. A fee for platform rights used only after import, such as hosting an advertising marketplace in India, is not automatically addable. The Supreme Court’s decision in Commissioner of Customs v Ferodo India, decided under the corresponding 1988 Rules, illustrates the approach: royalties tied to manufacture in India rather than to the imported goods were not added to assessable value.

Where televisions arrive as unassembled or semi-assembled kits, classification follows the General Rules for the Interpretation of the Customs Tariff, under which a heading extends to an incomplete or unassembled article that has the essential character of the complete article. The valuation file should show what software is loaded at import, what is downloaded later, and which agreement governs each.

Advertising services: supplier, recipient and place of supply

Three fact patterns recur. In the first, an overseas platform owner sells advertising inventory to an Indian brand or agency. Under section 13(2) of the IGST Act the place of supply is the recipient’s location in India. A registered Indian recipient pays IGST under reverse charge under Notification 10/2017-Integrated Tax (Rate) and may claim credit subject to section 16 of the CGST Act. If the service is online information and database access or retrieval and the Indian buyer is unregistered, the overseas supplier itself must register and pay tax under section 14.

In the second, an Indian company sells campaign management or advertising space to an overseas group company. The place of supply is the recipient’s location outside India, but zero rating needs every condition in section 2(6): supplier in India, recipient outside India, place of supply outside India, payment in convertible foreign exchange (or in rupees where the Reserve Bank permits), and supplier and recipient not merely establishments of a distinct person. Settlement through netting or a third group entity is where this most often fails.

In the third, an Indian entity arranges transactions between an advertiser and a foreign platform for a commission. For periods before 30 March 2026 the section 2(13) intermediary test, read with Circular 159/15/2021-GST, decided whether the place of supply was the supplier’s location. Section 13(8)(b) has since been omitted by the Finance Act 2026, so the recipient-location rule applies either way, but the characterisation still decides whether the taxable value is the gross price of the advertising or the commission earned.

A launch checklist for a connected-TV group

Before launch, assemble one file that follows each flow from contract to invoice to payment. For the goods flow, keep the supply and distribution agreements, the commercial invoices, the licence agreements for any embedded software and a short note on classification and valuation. For the rights flow, keep the operating system and content licences with the territory, sublicensing and data ownership terms. For the services flow, keep insertion orders, rate cards and campaign reports showing who contracted with the advertiser and who delivered the advertising. For the payment flow, keep the settlement statements, bank advices and any netting reconciliation.

Then add a sign-off matrix recording, for each contract, the supplier, recipient and their locations, the GST and customs treatment, the withholding position and the evidence held. Re-run the matrix whenever rights or funds flows change, and when the law changes, as it did for intermediary services in March 2026 and for online information and database access services in October 2023.

Conclusion

The complexity of a connected-TV business lies less in the technology than in the number of distinct rights and services monetised through the same device. It is a mistake to tax the whole ecosystem as though it were a single television transaction.

A clear transaction map allows customs, GST, income-tax withholding and transfer pricing analyses to follow the same commercial facts, even where their legal consequences differ. That is a more durable foundation than attempting to repair the tax position after the platform is operational.

Frequently asked questions

1. Are all revenue streams from a smart television sales of goods?

No. Rights and services supplied after device sale may be separate transactions.

2. Is all digital advertising automatically OIDAR?

No. The statutory definition and actual service model must be applied.

3. Does an overseas invoicing entity automatically make the supply an export?

No. The statutory export-of-services conditions must all be examined.

4. Can software licence payments affect customs valuation?

They may in particular circumstances. The rights, condition-of-sale terms and valuation law require review.

5. Why should GST and transfer pricing teams coordinate?

They should describe the same functions, rights and risks even though the valuation and tax rules differ.

6. Is GST payable on advertising services bought by an Indian company from an overseas platform?

Yes, usually. The place of supply is the Indian recipient’s location under section 13(2) of the IGST Act, and a registered Indian recipient pays IGST under reverse charge under Notification 10/2017-Integrated Tax (Rate). Credit can be claimed if the advertising is used for business and section 16 of the CGST Act is satisfied.

7. What is the place of supply for advertising services an Indian company provides to an overseas group company?

The IGST Act has no separate rule for advertising, so section 13(2) places the supply at the recipient’s location. If that is outside India, the supply is an export of services only if all conditions in section 2(6) are met, including payment in convertible foreign exchange and the parties not being merely establishments of a distinct person.

8. Is a software licence fee added to the customs value of imported televisions?

Only if it meets Rule 10(1)(c) of the Customs Valuation Rules, 2007: the royalty or licence fee must relate to the imported goods and be payable by the buyer, directly or indirectly, as a condition of their sale. Payments for rights used after import, unconnected with the sale of the goods, are not automatically added.

9. Does the omission of section 13(8)(b) matter for advertising agencies acting as intermediaries?

Yes. Section 157 of the Finance Act 2026 omitted section 13(8)(b) of the IGST Act, so cross-border intermediary services follow the recipient-location rule in section 13(2). Commentary reads this as effective from 30 March 2026. Intermediary status still affects valuation, and earlier periods remain governed by the old rule.

Talk to SBC’s tax team

If you are planning a connected-TV launch or reviewing an existing platform structure, our indirect tax team can help map each flow to its customs, GST and withholding treatment before contracts are finalised. Explore our GST services | Contact SBC

About the author

CA Mithilesh Reddy, Founder and CEO, Steadfast Business Consulting LLP, led the team that handled this engagement.

CA Rupesh Reddy, Steadfast Business Consulting LLP. SBC provides direct and indirect tax, international tax and transfer pricing advisory and dispute support.

About SBC | Meet the SBC team

Disclaimer

This article is general professional commentary and not advice on any particular facts. Treaty eligibility, applicable law, procedural requirements and statutory amendments must be verified for the relevant tax period. It is not a description of an identifiable client engagement.

CategoriesIndirect Tax

Place of Supply for an Event Held Outside India

Place of Supply for an Event Held Outside India

By CA Mithilesh Reddy, Founder and CEO, and CA Rajesh Vaishnav, Partner, Steadfast Business Consulting LLP | Indirect Tax Advisory

Quick answer

Where either party is outside India, section 13(5) of the IGST Act places admission to or organisation of an event, and ancillary services, where the event is actually held, so a summit in Dubai falls outside Indian GST. Where both parties are in India, section 12(7) applies instead. Sponsorship, broadcast and delegate supplies must be tested separately.

Key takeaways

  • Section 12 of the IGST Act applies where supplier and recipient are both in India and section 13 applies where either is outside India, so the same overseas event can produce different place of supply answers for different invoices.
  • Under section 13(5), admission to or organisation of an event, and ancillary services, are placed where the event is actually held; under section 12(7) a registered recipient’s own location decides the supply, whatever the venue.
  • Sponsorship is expressly covered by section 12(7) for supplies within India, but section 13(5) does not mention it, so a cross-border sponsorship starts from the default recipient-location rule in section 13(2).
  • A supply is an export under section 2(6) only if all five conditions are met, and since 1 October 2023 the general zero rating route is supply under bond or letter of undertaking, with refund of unutilised credit under section 54 of the CGST Act.
  • Contract-by-contract analysis, invoices that name the event and service, and venue evidence collected during the event are what make a place of supply position defensible.

Practice illustration: Event-related services supplied across borders

Issue. A business examined the place of supply of services related to an event outside India.

Approach. The advisory treated event organisation, admission, sponsorship, broadcasting and other contracts separately under sections 12 or 13 of the IGST Act as appropriate.

Outcome. The classification and documentation framework was implemented for the event-related services. This does not establish a binding decision that all supplies associated with an overseas event fall outside Indian GST.

Practical lesson. One overseas venue does not produce a single place-of-supply answer for every supply.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

Place of supply determines whether Indian GST applies at all. For services it is governed by two separate provisions, one for supplies where both parties are in India and another for supplies where either is outside it, and the two do not always give the same answer on the same facts. Events have their own rules within each, which is sensible for an activity that happens at an identifiable place, and awkward for an event whose vendors, sponsors, broadcasters and delegates are spread across several countries.

The rule that sources event services to the place the event is held is clear enough in itself. The error is applying it in one stroke to every invoice connected with the event. An international summit involves production and venue services, broadcast and media coverage, sponsorship administration, delegate travel arrangements and sometimes digital services supplied to participants who never travel. Not all of those are services supplied in relation to the event in the sense the provision contemplates, and each has to be tested on its own. The consequence of getting it wrong runs in both directions: tax paid on services outside the charge is an unrecoverable cost, and tax not paid on services within it is a demand with interest.

This note deals with an event held outside India and the supplies that surround it. It covers which of the two provisions applies and why that is decided by the location of the parties rather than the venue, a service by service analysis across production, media, sponsorship and delegate facing supplies, the position of an Indian sponsor, hybrid and digital participation, the export conditions where they apply, and the documentation that has to be assembled during the event rather than afterwards. For the related classification question that decides whether a cross border service is an export at all, see our note on intermediary or principal under section 2(13).

1. Which provision applies

The analysis begins with the location of the parties rather than with the nature of the service.

Section 12 of the IGST Act applies where both the supplier and the recipient are located in India. Section 13 applies where either is outside India. A single event will frequently involve both: an Indian production company engaged by an Indian organiser falls under section 12, while the same production company engaged by an overseas entity falls under section 13. The same physical activity in the same venue produces different place of supply outcomes depending on who contracted with whom.

The two provisions also differ in substance on events, and the difference is easy to miss.

Under section 12, admission to an event under section 12(6) is placed where the event is actually held. Organisation of an event under section 12(7) turns on the status of the recipient. Where the recipient is a registered person, sub-clause (i) places the supply at the location of that person, and the location of the event is irrelevant. Where the recipient is not registered, sub-clause (ii) places the supply where the event is actually held, and it is only within that sub-clause that the further rule appears: if the event is held outside India, the place of supply is the location of the recipient. The overseas event rule therefore applies only to unregistered recipients. Where an event spans more than one state and a consolidated amount is charged, the supply is apportioned.

Under section 13(5), services by way of admission to or organisation of such an event, and services ancillary to such admission or organisation, are placed where the event is actually held, without the distinction between registered and unregistered recipients.

That difference matters directly for an Indian organiser holding an event abroad. Where the Indian organiser engages an Indian supplier, both are in India and section 12(7) applies. The organiser is a registered person, so sub-clause (i) places the supply at its own location in India, and the fact that the event is held abroad makes no difference to that result. Where the Indian organiser engages an overseas supplier, or supplies its own services to an overseas recipient, section 13(5) applies instead and the place of supply is the venue.

2. The service by service analysis

The categories below reflect how a typical international summit resolves. The reasoning matters more than the labels, because the answer depends on what the service actually is rather than on what the invoice calls it.

Event management, production and venue coordination. These are the core organisation services and, where section 13 applies, they are placed where the event is held. Where the event is in Dubai, they are outside the Indian charge. The supporting evidence is the venue contract, the production schedule and the deliverables, all of which locate the activity.

Services ancillary to organisation. Section 13(5) expressly extends to services ancillary to admission or organisation. Staging, audio visual, security, on site logistics and hospitality at the venue fall here on ordinary principles. The ancillary character should be demonstrated by reference to the venue and the event rather than assumed.

Media coverage and broadcasting. This is the category that most often needs separate analysis. Where a broadcaster films the event at the venue, the service is closely connected to the event. Where a service is the transmission of a signal, the provision of satellite bandwidth, or the licensing of footage for later use, the supply is not naturally described as organisation of the event or as ancillary to it, and the default rule in section 13(2), placing the supply at the recipient’s location, may be the better fit. A single media contract frequently contains both, and it should be unbundled before it is characterised.

Sponsorship. Where both parties are in India, section 12(7) expressly covers the assigning of sponsorship to an event and applies the recipient-based rule described above. Section 13(5) does not mention sponsorship, so for a cross-border sponsorship the default rule in section 13(2) is the starting point, and the analysis follows the recipient and the nature of the rights granted. Where an Indian sponsor acquires rights, the supply to it is not automatically outside India merely because the event is abroad. Sponsorship arrangements also frequently include a package of deliverables, such as branding at the venue, digital promotion, hospitality and a speaking slot, and the package should be examined rather than treated as a single undifferentiated right.

Delegate facing services. Registration, accommodation booking and travel arrangements are separate supplies with their own rules, and they are commonly invoiced by the organiser as part of a delegate fee. Where they are, the composite supply analysis under sections 2(30) and 8 has to be applied before the place of supply question is reached.

Digital participation. Where the event is streamed, or where remote participants access content, the supply to those participants is not a supply of admission to an event held at a place. It requires its own analysis, and for an overseas supplier delivering to unregistered Indian recipients the online information and database access provisions may be engaged.

3. Export, where it applies

Where an Indian supplier provides services to an overseas recipient and the place of supply is outside India, the next question is whether the supply qualifies as an export under section 2(6) of the IGST Act. All five conditions must hold: the supplier is in India; the recipient is outside India; the place of supply is outside India; payment is received in convertible foreign exchange, or in Indian rupees wherever permitted by the Reserve Bank; and the supplier and recipient are not merely establishments of a distinct person.

The fourth condition is a frequent point of failure in event work, because settlement is often routed through a group entity or set off against other balances. The fifth catches arrangements where the overseas organiser is a branch or establishment of the same Indian entity, in which case the supply is not an export however it is documented.

Where the supply is an export, zero rating under section 16 applies through the bond or letter of undertaking route, with refund of unutilised credit under section 54 of the CGST Act. Since the substitution of section 16(3) with effect from 1 October 2023 that is the general route, and the alternative of paying tax and claiming refund is available only to a notified class under section 16(4).

4. The documentation that makes the position defensible

A place of supply conclusion is only as good as the evidence that the service was what the analysis says it was. For an overseas event the file should contain the following, assembled during the event rather than afterwards.

  • The venue contract, establishing where the event was held and over what dates.
  • Vendor agreements that describe each service by reference to the event and the venue, rather than in generic terms.
  • Invoices that describe the service specifically and identify the event. An invoice reading “professional services” supports nothing.
  • The event programme and run sheet, which evidences what was actually delivered at the venue.
  • Evidence of performance at the venue: crew lists, equipment manifests, site photographs, delivery notes.
  • For media contracts, an unbundled scope distinguishing on site coverage from transmission and from any licensing of footage.
  • For sponsorship, the rights schedule setting out each deliverable.
  • Where export is claimed, the foreign inward remittance evidence and the letter of undertaking.
  • A dated positions note recording the characterisation of each category and the provision relied on.

5. A worked example

An Indian organiser holds a multi-day international conference at a venue in the Gulf. It engages Indian and overseas vendors, broadcasts parts of the summit, and sells sponsorship packages to Indian and overseas sponsors. Delegate fees cover admission, accommodation and transfers.

Production and venue services supplied by overseas vendors to the Indian organiser. Section 13 applies because the supplier is outside India. Under section 13(5) the place of supply is Dubai, so these are outside the Indian charge and no reverse charge arises on them.

Production services supplied by Indian vendors to the Indian organiser. Both parties are in India, so section 12 applies. The organiser is a registered person, so under section 12(7)(i) the place of supply is its own location in India and these supplies are taxable in India. The location of the event does not enter the analysis. This is the result that surprises organisers most often, and the reason matters: it is the organiser’s registration, not the venue, that fixes the place of supply.

The organiser’s own services to overseas sponsors and participants. Section 13 applies. Organisation and ancillary services are placed at the venue under section 13(5). Where the supply qualifies as an export under section 2(6), zero rating applies subject to the consideration and distinct person conditions.

Broadcast. The media contract is unbundled. On site filming is treated as ancillary to the organisation of the event. Signal transmission and footage licensing are analysed separately, with the default rule in section 13(2) considered for those elements.

Sponsorship. The rights schedule is examined. Branding at the venue is treated differently from a digital promotion campaign delivered to an Indian audience, and the analysis follows the recipient and the rights rather than the location of the summit.

Delegate fees. Where admission, accommodation and transfers are supplied for a single price, the composite supply analysis under sections 2(30) and 8 is applied first to identify the principal supply, and the place of supply follows that characterisation.

6. The Indian sponsor, looked at from the other side

Most analyses of a cross border event are written from the organiser’s side. The sponsor’s position is a separate question and it is frequently left unanswered until an audit raises it.

Where an Indian sponsor pays an Indian organiser for a package of rights at an overseas event, both parties are in India and section 12 governs. Where the sponsor pays an overseas organiser, section 13 governs and the question is whether the package falls within the event rule or within the default rule for the recipient’s location. Where the place of supply is in India and the supplier is outside India, the supply is an import of services on which the Indian sponsor discharges tax under reverse charge, with credit where it is otherwise eligible.

The analysis turns on what the sponsorship package actually contains, which is why the rights schedule matters. Branding displayed at the venue, a speaking slot at the event and hospitality at the venue sit close to the event. A digital campaign delivered to an audience in India, a logo on a website, and rights to use event footage in the sponsor’s own marketing for a year afterwards do not. A package that bundles all of these for a single fee requires the composite supply analysis before the place of supply analysis, and the answer may well be that the package is a mixed supply rather than a composite one.

7. Digital and hybrid participation

Few international events are now entirely physical, and the hybrid element does not follow the physical one.

A delegate who attends in Dubai is admitted to an event held at a place. A delegate who watches a stream from an office in Mumbai is not. The supply to the second delegate is not naturally described as admission to an event held outside India, and it requires its own analysis. Where the supplier is outside India and the recipient is an unregistered person in India, the online information and database access provisions may be engaged, with the compliance obligations that follow for the overseas supplier. Where the recipient is a registered person in India, reverse charge on an import of services is the more likely answer.

The practical step is to separate the fee. An event that offers physical attendance at one price and digital access at another has already done the work. An event that offers a single fee covering both has created a characterisation question it will have to answer later, and the easiest time to avoid it is when the pricing is set.

8. Documentation for a refund claim

Where the organiser is exporting services and accumulating credit, the place of supply analysis is only the first half of the exercise. The refund claim brings its own requirements, and refund officers test them independently of the characterisation.

The claim has to correlate the credit claimed with the export turnover, which means linking input invoices to the event and to the exported supply rather than offering an aggregate figure. It has to be computed in accordance with the prescribed formula, with the turnover of zero rated supply of services computed on the payments basis the formula requires rather than on invoiced value. And the letter of undertaking has to have been in place before the first zero rated supply, not obtained afterwards.

For an event business the correlation exercise is unusually awkward, because costs are incurred in a short window and across many vendors, and because some of those costs relate to supplies that are not zero rated. Building the correlation during the event, as invoices arrive, is materially easier than reconstructing it from a general ledger six months later.

9. Where these positions fail

First, one conclusion is applied to the whole event. This is the most common error, and it produces exposure in both directions.

Second, section 12 and section 13 are conflated. The two provisions give different answers for an event held abroad, and the applicable one depends on where the parties are, not on where the event is.

Third, invoices are generic. A description that does not identify the event or the service leaves nothing to support the characterisation.

Fourth, media contracts are not unbundled, so a single characterisation is applied to filming, transmission and licensing.

Fifth, sponsorship is assumed to follow the event location. It follows the recipient and the rights.

Sixth, the export conditions are not separately verified, particularly the receipt of consideration and the distinct person condition.

Seventh, the file is assembled after the event. The venue contract, run sheet, crew lists and site evidence exist only if someone kept them.

10. A pre event checklist

  1. Map every contract, identifying the supplier, the recipient, the location of each and whether the recipient is registered, before deciding whether section 12 or section 13 applies to it.
  2. Categorise each service as organisation, ancillary to organisation, media, sponsorship, delegate facing or digital.
  3. Apply the correct provision to each category and record the conclusion with reasons.
  4. Unbundle composite media and sponsorship contracts into their components before characterising them.
  5. Specify invoice narration requirements for every vendor, so that invoices identify the event and the service.
  6. Where supplies are composite, apply the composite supply analysis before the place of supply analysis.
  7. For each export claim, verify all five conditions in section 2(6) separately, with evidence.
  8. Confirm the letter of undertaking is in place before the first zero rated supply.
  9. Assign responsibility for collecting venue evidence during the event.
  10. Prepare a dated positions note before the event and update it if the scope changes.
  11. Reconcile the final invoicing against the positions note after the event.
  12. Diarise the refund claim timeline where credit accumulates.

Practitioner’s perspective

Cross border events are a growing part of what Indian media, broadcasting and professional services businesses do, and the indirect tax treatment is more variable than most organisers expect. The single most valuable thing an adviser can do is to insist that the analysis is conducted contract by contract, because the appealing simplicity of a single conclusion is precisely what creates the exposure.

The result that catches organisers repeatedly is worth stating plainly. Where an Indian organiser engages an Indian vendor for an event held abroad, both parties are in India and section 12(7) applies. Because the organiser is registered, sub-clause (i) places the supply at its location in India, and the venue is immaterial. The rule that sources an overseas event to the recipient’s location sits in sub-clause (ii) and is confined to unregistered recipients, which is a distinction worth holding on to, because it is the one most often misread. It is the supplies involving an overseas party that section 13(5) places at the venue.

Beyond that, this is a documentation discipline rather than a legal one. The position is defensible if the invoices say what the services were and the file shows where they were performed. Both are free to arrange before the event and impossible to arrange afterwards.

How sections 13(3), 13(4), 13(5), 13(6) and 13(8) fit together for an event

Section 13 of the IGST Act is a set of exceptions to the default rule in section 13(2), which places a supply at the recipient’s location. Several of those exceptions touch an event. Section 13(5) covers admission to and organisation of the event and ancillary services. Section 13(4) covers services directly related to immovable property, including hotel accommodation and the grant of rights to use immovable property, so a delegate’s hotel stay or the hire of the venue itself is located where the property is. Section 13(3)(b) covers services supplied to an individual that need the individual’s physical presence, such as a workshop delivered to a delegate, and places them where they are performed. Travel is separate again: passenger transportation is placed where the passenger boards the conveyance for a continuous journey under section 13(10).

Two provisions deal with events that do not sit in one place. Under section 13(6), where a service falling within section 13(3), 13(4) or 13(5) is supplied at more than one location, including a location in the taxable territory, the place of supply is the location in the taxable territory. Under section 13(7), where such a service is supplied in more than one State or Union territory, it is treated as supplied in each, with value apportioned on the contract or as prescribed. An event with sessions in India and abroad, or an international programme that ends with a session in an Indian city, should be tested against section 13(6) before the overseas venue conclusion is applied.

Two changes in the law should be kept in view. Section 13(8)(b), which placed intermediary services at the supplier’s location, was omitted by section 157 of the Finance Act 2026. Commentary reads the omission as effective on assent, 30 March 2026, and the definition of intermediary in section 2(13) is unchanged. An agent that sells sponsorship or delegate places on an organiser’s behalf is therefore tested against the default rule in section 13(2) for later periods, while earlier periods stay under the old rule. Separately, section 16(3) of the IGST Act was substituted with effect from 1 October 2023 (Notification 27/2023-Central Tax), making supply under bond or letter of undertaking the general zero rating route, and the Finance (No. 2) Act 2024 added a cross-reference to section 54 of the CGST Act in section 16(4). We found no 2024 amendment to the event rules in sections 12 or 13.

Frequently asked questions

1. Where is the place of supply for services relating to an event held outside India?

Where section 13 applies, because the supplier or the recipient is outside India, section 13(5) places services by way of admission to or organisation of the event, and services ancillary to them, at the place where the event is actually held. For an event in Dubai, that is outside India.

2. Does that mean everything connected with the event is outside Indian GST?

No. The rule applies to admission, organisation and ancillary services where section 13 governs. Other services connected with the event, and services where both parties are in India, are governed by different rules and may well be taxable in India.

3. What happens where an Indian organiser engages an Indian vendor for an overseas event?

Both parties are in India, so section 12 applies. The organiser is a registered person, so under section 12(7)(i) the place of supply is its own location in India and the supply is taxable in India. The venue is immaterial to that result. The rule sourcing an overseas event to the recipient’s location sits in section 12(7)(ii) and applies only where the recipient is not registered.

4. How should broadcast and media services be treated?

By unbundling the contract. On site filming at the venue is readily characterised as ancillary to the organisation of the event. Transmission of a signal, provision of bandwidth and licensing of footage are not naturally organisation services, and the default rule in section 13(2) should be considered for them.

5. Does sponsorship follow the event location?

Not automatically. Sponsorship is a grant of promotional rights, and the analysis follows the recipient and the nature of the rights rather than where the event is held. The rights schedule should be examined component by component.

6. How are delegate fees covering admission, accommodation and transfers treated?

Where they are supplied for a single price, the composite supply analysis under sections 2(30) and 8 applies first, to identify the principal supply. The place of supply then follows that characterisation.

7. What conditions must be met for the supply to be an export?

All five in section 2(6): supplier in India, recipient outside India, place of supply outside India, payment received in convertible foreign exchange or in Indian rupees where permitted by the Reserve Bank, and the supplier and recipient not merely establishments of a distinct person.

8. Which zero rating route is available?

Since the substitution of section 16(3) with effect from 1 October 2023 the general route is supply under bond or letter of undertaking without payment of tax, with refund of unutilised credit under section 54 of the CGST Act. The with payment route is available only to a notified class under section 16(4).

9. What documentation supports the position?

The venue contract, vendor agreements describing each service by reference to the event, invoices with specific narration, the event programme and run sheet, evidence of performance at the venue, unbundled scopes for media and sponsorship, remittance evidence where export is claimed, and a dated positions note.

10. What is the most common error?

Applying a single place of supply conclusion to every invoice connected with the event. The exposure runs in both directions: tax paid on supplies outside the charge is an unrecoverable cost, and tax not paid on supplies within it is a demand with interest.

11. What is the place of supply for sponsorship of an event under GST?

Where supplier and recipient are both in India, section 12(7) of the IGST Act expressly covers assigning of sponsorship to an event: a registered recipient’s location decides, and an unregistered recipient is placed at the venue, or at its own location if the event is abroad. Section 13(5) does not mention sponsorship, so a cross-border sponsorship starts from section 13(2), the recipient’s location.

12. Did the Finance Act 2026 change the place of supply for intermediary services connected with events?

Yes. Section 157 of the Finance Act 2026 omitted section 13(8)(b) of the IGST Act, which had placed intermediary services at the supplier’s location. Commentary reads the change as effective from assent on 30 March 2026. Cross-border intermediary services now follow the recipient-location rule in section 13(2). The definition in section 2(13) is unchanged.

13. Is a conference held partly in India and partly abroad taxed in India?

Section 13(6) of the IGST Act provides that where an event service is supplied at more than one location, including one in the taxable territory, the place of supply is the location in the taxable territory. A programme with any session in India therefore needs to be tested against that sub-section before treating the whole supply as sourced to the overseas venue.

14. Where is the place of supply for hotel accommodation booked for delegates at an overseas event?

Where the supplier or recipient is outside India, section 13(4) of the IGST Act places services directly related to immovable property, including accommodation by hotels, inns and guest houses, where the property is located. Hotel accommodation at an overseas venue therefore has a place of supply outside India, subject to the composite supply analysis if it is bundled into a delegate fee.

Talk to SBC’s tax team

If you are planning an event outside India or reviewing invoices for one that has taken place, our indirect tax team can help map each contract to the correct place of supply provision and the evidence it needs. Explore our GST services | Contact SBC

About the author

CA Mithilesh Reddy, Founder and CEO, Steadfast Business Consulting LLP, led the team that handled this engagement.

CA Rajesh Vaishnav is a Partner at Steadfast Business Consulting LLP. SBC provides direct and indirect tax, international tax and transfer pricing advisory and dispute support.

About SBC | Meet the SBC team

Disclaimer

This article is for general information and does not constitute professional advice. It reflects the law as understood at the date of publication and does not take account of later developments. The place of supply for any service depends on the location of the parties, the nature of the service and the terms of the contract, and the analysis must be conducted supply by supply. No reader should act on the basis of this article without taking advice on their own circumstances.

CategoriesIndirect Tax

Structuring a Joint Development Agreement for GST Before the Project Starts

Structuring a Joint Development Agreement for GST Before the Project Starts

By CA Mithilesh Reddy, Founder and CEO, and CA Rajesh Vaishnav, Partner, Steadfast Business Consulting LLP | Indirect Tax Advisory

Quick answer

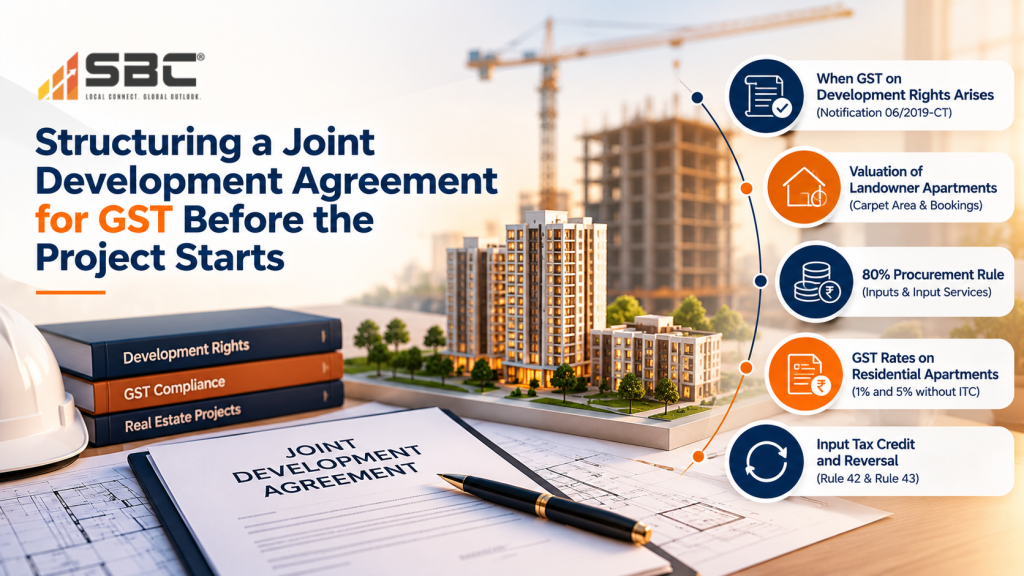
GST on a joint development agreement turns on four questions: when tax on development rights arises, how much is taxable, how landowner apartments are valued, and which credits survive. For rights received from 1 April 2019, Notification 06/2019-Central Tax (Rate) defers liability to the completion certificate or first occupation, whichever is earlier, payable by the promoter under reverse charge.

Key takeaways

  • For development rights, floor space index or long term leases received on or after 1 April 2019, Notification 06/2019-Central Tax (Rate) fixes liability at the earlier of the completion certificate or first occupation, and the promoter pays under reverse charge through entries 5B and 5C of Notification 13/2017-Central Tax (Rate).
  • The exemption for development rights in entry 41A of the exemption notification covers only the share attributable to residential apartments booked before completion; unbooked residential apartments and commercial areas remain taxable in the promoter’s hands.
  • Residential apartments carry headline central tax of 0.75 per cent (affordable) and 3.75 per cent (others), which become effective rates of one and five per cent after a deemed one-third land deduction, without input tax credit.
  • At least 80 per cent of inputs and input services must come from registered suppliers; the shortfall bears 18 per cent under reverse charge, payable by June after the financial year, and cement from unregistered suppliers is taxed separately.
  • Valuation of the landowner’s apartments, carpet area definitions, who bears each tax and the evidence of bookings should be fixed in the agreement, because both the final tax and any credit reversal move with pre-completion sales.

Practice illustration: GST at the structuring stage of a joint development project

Issue. An arrangement exchanging development rights for construction services required an analysis of taxability, timing, value and input tax credit.

Approach. The advisory distinguished the GST supplies, tested the applicable real-estate notifications and recommended appropriate documentation.

Outcome. The reported deliverable was a GST structuring framework; no departmental ruling or exemption approval was claimed.

Practical lesson. Credit and reversal rules must follow the project’s applicable rate and transition regime.

This illustration is deliberately generalised and must not be used to identify a taxpayer or matter.

Introduction

A joint development agreement is not one transaction. The landowner supplies development rights. The developer supplies construction services, often partly for money and partly for constructed apartments handed back. Units are then sold to buyers, some before completion and some after. Each of those legs has its own GST treatment, its own timing and its own valuation, and the legs interact: how much of the first is taxable depends on how many of the last were sold before the project completed.

Settling the treatment of each leg at structuring stage is not a compliance nicety. The timing provision determines whether a developer funds a material tax outflow at the start of a project or at the end of it, and the credit analysis determines the cost base of every unit sold.

This note deals with settling all of that at structuring stage, before the agreement is executed, rather than at the first audit. It covers the 2019 notification framework and the rate structure, when liability on the transfer of development rights crystallises and on whom, how much of that transfer is actually taxable given that the exemption is partial, how the landowner’s constructed units are valued, which input credits survive the residential restrictions, the eighty per cent procurement condition with a worked computation, and the credit reversal attributable to unsold inventory at completion.

1. The framework

Six notifications dated 29 March 2019, effective from 1 April 2019, together make up the regime.

Notification Effect
03/2019-Central Tax (Rate) Amends the principal rate notification to insert the new real estate rate entries, with the annexures governing transitional credit for ongoing projects.
04/2019-Central Tax (Rate) Amends the exemption notification to exempt transfer of development rights, floor space index and long term lease, to the extent attributable to residential apartments booked before completion.
05/2019-Central Tax (Rate) Amends the reverse charge notification to insert entry 5B, covering transfer of development rights or floor space index for construction of a project by a promoter, and entry 5C, covering a long term lease of land of thirty years or more against upfront consideration. Both are payable by the promoter.
06/2019-Central Tax (Rate) Issued under section 148, notifies promoters receiving development rights, floor space index or a long term lease as a class of registered persons and fixes the time of supply.
07/2019-Central Tax (Rate) Notifies the supplies attracting reverse charge where the eighty per cent procurement condition is not met, and the cement mechanism.
08/2019-Central Tax (Rate) Amends the goods rate notification 1/2017 for the real estate sector. The reverse charge on shortfall inputs, cement and capital goods is notified separately in 07/2019.

The rate structure introduced by notification 03/2019 is 0.75 per cent central tax for affordable residential apartments and 3.75 per cent for other residential apartments and for commercial apartments in a residential real estate project, each with the matching state tax. These are headline rates of 1.5 per cent and 7.5 per cent; because land is deemed to be one third of the total amount charged and is excluded from the taxable value, the effective rates are one per cent and five per cent of the total consideration. Both are without input tax credit and payable in cash. Ongoing projects could elect, by 10 May 2019, to continue at the earlier rates with credit.

The eighty per cent condition requires that at least eighty per cent of inputs and input services be procured from registered suppliers, excluding development rights, long term lease of land, floor space index, electricity, high speed diesel, motor spirit and natural gas from the computation. The shortfall is taxed at eighteen per cent under reverse charge in the promoter’s hands, payable by June following the end of the financial year. Cement procured from an unregistered supplier attracts reverse charge at the applicable rate irrespective of the eighty per cent threshold.

2. Question one: when does liability on development rights arise

This is the provision that most affects project cash flow, and it is the reason the framework is workable at all.

Notification No. 06/2019-Central Tax (Rate), issued under section 148, notifies registered promoters who receive development rights or floor space index on or after 1 April 2019 against consideration in the form of construction services or otherwise, and promoters who receive a long term lease of land for residential apartments against upfront premium, as a class of registered persons in whose case the liability to pay tax arises on the date of issuance of the completion certificate by the competent authority, or on first occupation of the project, whichever is earlier.

Three consequences follow for a developer.

For the supplies covered by notification 06/2019, the tax on development rights is not payable when the agreement is executed, nor when construction begins, nor when units are sold. It is payable at the end of the project. The deferral covers consideration paid as construction service and monetary consideration relatable to residential apartments; cash consideration for a commercial component is not deferred in the same way and has to be analysed separately. A developer that provides for it at signing is funding a liability that has not arisen.

The liability sits on the promoter under reverse charge by virtue of entry 5B inserted by notification 05/2019, not on the landowner. For a landowner who is an individual not otherwise registered, that is a material point and should be recorded in the agreement so that neither party later assumes the other is accounting for it.

Because the trigger is the completion certificate or first occupation, the project needs a protocol for identifying and documenting that date. First occupation in particular is a question of fact, and a developer that cannot evidence it is exposed on the timing of its own liability.

3. Question two: how much is taxable

Notification 04/2019 exempts the transfer of development rights, floor space index and long term lease to the extent attributable to residential apartments booked before completion. The exemption is partial and proportionate, and the proportion is not known until the end of the project.

That produces a computation that has to be run at the trigger date. The taxable portion corresponds to the residential apartments that remain unbooked as at the completion certificate or first occupation date, together with the commercial portion, for which the exemption does not apply in the same way.

The practical implication is that the eventual liability on development rights depends on sales performance, and a project that sells well before completion has a materially lower liability than one that does not. For a developer modelling a project, this should be in the cash flow as a range rather than as a fixed number, with the drivers identified. The proviso to entry 41A also caps the tax on the unbooked residential share at 0.5 per cent central tax for affordable apartments and 2.5 per cent for other residential apartments (one and five per cent including state tax) of the value of those apartments, so the range has a ceiling.

4. Question three: valuing the landowner’s constructed units

Where the developer gives the landowner constructed apartments as consideration for the development rights, the developer has supplied construction services and received non monetary consideration. Value is determined under section 15 of the CGST Act and the valuation rules, and for development rights acquired against apartments the 2019 notifications deem the value to be the amount the promoter charged for similar apartments to independent buyers nearest to the date on which the development rights are transferred.

Three points matter in the drafting.

Identify the reference transaction. The agreement should record how the value of the landowner’s share will be determined and against which comparable sales. Leaving it to be worked out years later, from a price list that has changed many times, is how valuation disputes start.

Fix the area allocation precisely. The landowner’s entitlement should be specified in carpet area terms, by unit where possible, with the mechanism for substitution if a unit becomes unavailable. Area definitions should follow the statutory definition rather than a local convention.

Record who bears the tax. The agreement should state expressly which party bears the tax on the development rights and which bears the tax on the construction service provided to the landowner. Silence on this point produces a dispute between the parties in addition to the dispute with the department.

5. Question four: which credits survive

Qualifying residential construction taxed under the post-2019 one per cent or five per cent effective rate generally does not carry input tax credit; transitional projects and other supplies must be reviewed under their own applicable entries and conditions. That is the defining commercial feature of the regime and it shapes procurement, because credit that cannot be taken becomes cost.

Where a project has both residential and commercial components, or where an ongoing project elected to continue under the earlier rates with credit, apportionment becomes necessary. Rules 42 and 43 of the CGST Rules, as amended by Notification No. 16/2019-Central Tax with effect from 1 April 2019, contain the real estate machinery. The ratio is computed per project on a carpet area basis rather than on turnover, and the exempt element includes apartments that remain unbooked as at the completion certificate or first occupation date. A final computation is required, with reversal and interest or re-credit as the case may be.

Rule 43 treatment of capital goods must be assessed in the context of the relevant credit regime and transitional provisions; it must not be applied mechanically to a project under the post-2019 no-ITC residential rate.

The planning point is that the reversal attributable to unsold inventory at completion is a real and often large number, it is driven by sales performance, and it should be modelled from the outset rather than discovered at the end of the project.

6. A worked example

A developer enters into a joint development agreement with landowners for a residential project. The landowners contribute development rights; the developer constructs and markets; the landowners receive a specified number of constructed apartments plus a monetary element.

Development rights. Liability arises under entry 5B on reverse charge in the developer’s hands, at the completion certificate or first occupation, whichever is earlier. The exemption in notification 04/2019 applies to the extent attributable to residential apartments booked before completion, so the taxable base is a function of unsold inventory at that date. The cash flow model carries a range, not a point estimate.

Landowner’s units. The construction service supplied to the landowners is valued by reference to the price charged to independent buyers for similar apartments nearest the date of transfer of the development rights. The agreement records the mechanism and the comparable set.

Procurement. The eighty per cent condition is monitored from the first procurement rather than computed at year end. Cement is tracked separately because it attracts reverse charge from an unregistered supplier regardless of the threshold. A register of registered and unregistered procurement, by value, is maintained monthly.

Credit. Under the one per cent and five per cent regime no credit is taken, and the procurement strategy reflects that credit is cost. Where an eligible or transitional component falls outside the no-credit regime, the relevant Rule 42 or Rule 43 methodology and any special project-level computation must be considered separately.

Documentation. A dated file records each position taken, the provision relied on, and the computation. That file is what answers the audit three years later, and it cannot be reconstructed.

7. The eighty per cent condition, in figures

The shortfall mechanism is widely misunderstood, so a short illustration helps. Suppose a project incurs the following during a financial year, in crore, excluding the items the computation leaves out.

Procurement Amount
From registered suppliers 72
From unregistered suppliers 28
Total inputs and input services in the computation 100

Registered procurement is 72 per cent against a requirement of 80 per cent, so there is a shortfall of 8. That shortfall is taxed at eighteen per cent under reverse charge in the promoter’s hands, giving a liability of 1.44, payable by June following the end of the financial year.

Two points follow. First, the charge is on the shortfall, not on the whole of the unregistered procurement, so a project at 72 per cent pays on 8 rather than on 28. Second, cement sits outside this arithmetic entirely: cement procured from an unregistered supplier attracts reverse charge at the applicable rate whether or not the eighty per cent threshold is met, so cement procurement has to be tracked and taxed separately and is not available to cure a shortfall elsewhere.

The practical consequence is that the condition has to be monitored during the year. A project that discovers in April that it finished at 72 per cent can do nothing about it. A project that sees in October that it is tracking at 74 per cent can change its procurement.

8. Ongoing projects and the transitional computation

The regime distinguishes between projects that commenced on or after 1 April 2019, which are compulsorily within the new structure, and ongoing projects, which could elect by 10 May 2019 to continue at the earlier rates with input tax credit. The election was exercisable separately for each project, and a developer with several projects may therefore be operating under both regimes at once.

For a project that moved to the new structure, Annexures I and II to the principal amending notification govern the transitional credit computation, under which credit attributable to the portion of the project completed before the changeover is determined and the balance is reversed. A developer running both regimes needs to keep the computations and the credit ledgers for each project genuinely separate, because the apportionment machinery operates per project and a consolidated approach cannot be reconciled afterwards.

9. Carpet area, which decides more than it appears to

Carpet area carries three separate consequences and it is frequently computed on an internal convention rather than the statutory definition.

It determines whether an apartment is affordable, and therefore whether the one per cent or the five per cent rate applies, in combination with the value threshold. It is the basis on which the landowner’s entitlement under the agreement is usually expressed, and therefore the basis of the valuation of the construction service supplied to the landowner. And it is the basis of the apportionment ratio in Rules 42 and 43 for a real estate project, where the exempt element is computed on the carpet area of unbooked apartments at completion rather than on turnover.

A single inconsistency in how carpet area is measured therefore propagates into the rate, the valuation and the credit reversal. It is worth settling the definition once, in writing, at the start of the project, and applying it everywhere.

10. Where these projects go wrong

First, the liability on development rights is accrued at signing. The timing provision defers it to completion, and accruing early distorts the project economics and the tax provision.

Second, the completion certificate or first occupation date is not documented. Both are factual, and first occupation in particular needs an evidenced position.

Third, the eighty per cent condition is computed once, at year end, and the shortfall is a surprise. It should be monitored monthly, because by year end nothing can be done about it.

Fourth, cement is treated as part of the eighty per cent computation rather than as a separate reverse charge obligation.

Fifth, the valuation of the landowner’s units is left to be determined later. The comparable prices available at the relevant date are the ones that matter, and they are hard to reconstruct.

Sixth, the agreement is silent on who bears the tax. This produces a commercial dispute on top of the tax question.

Seventh, the credit reversal attributable to unsold inventory is not modelled, so a project that sells slowly produces an unbudgeted charge at completion.

Eighth, carpet area is computed on an internal convention rather than the statutory definition, which affects both the rate entry for affordable apartments and the Rules 42 and 43 ratio.

11. A structuring checklist

  1. Classify the project and each apartment against the affordable and other residential definitions, using the statutory carpet area and value thresholds.
  2. Confirm whether the project is new or ongoing, and for an ongoing project whether the election was made.
  3. Record in the agreement that the liability on development rights is on the promoter under reverse charge and arises at completion or first occupation.
  4. Specify the landowner’s entitlement in carpet area, by unit, with a substitution mechanism.
  5. Record the valuation mechanism for the landowner’s units and the comparable set to be used.
  6. State expressly which party bears each tax.
  7. Set up monthly monitoring of the eighty per cent procurement condition, with cement tracked separately.
  8. Model the development rights liability as a range driven by pre completion bookings.
  9. Model the credit position, including any Rules 42 and 43 apportionment on a carpet area basis and the reversal attributable to unsold inventory.
  10. Establish a protocol for identifying and evidencing the completion certificate and first occupation dates.
  11. Maintain a dated positions file recording each conclusion and the provision relied on.
  12. Review the position at each project milestone rather than treating the structuring note as final.

Practitioner’s perspective

Joint development agreements are among the most technically demanding transactions under GST, and the difficulty is less in the law than in the sequencing. Almost every question that generates a dispute at audit is one that could have been settled, cheaply, in the agreement.

The timing provision in notification 06/2019 is the most commercially significant feature of the regime and the most frequently misapplied. Deferring the liability on development rights to completion or first occupation is a substantial cash flow benefit, and a developer that provides for the tax at signing is giving it up for no reason.

The other point worth emphasising is that the eventual liability and the eventual credit reversal are both functions of how much of the project is sold before completion. That makes them commercial variables, not fixed compliance costs, and they belong in the project model from the first appraisal rather than in a tax computation at the end.

Development rights supplied before 1 April 2019: Notification 4/2018 and the transition

The March 2019 framework applies to development rights, floor space index and long term leases received on or after 1 April 2019. Earlier supplies sit under a different regime. Notification No. 4/2018-Central Tax (Rate), issued on 25 January 2018 under section 148 of the CGST Act, fixed the time of supply for development rights granted against construction service: the liability arises when the developer transfers possession or rights in the constructed property to the person who supplied the development rights, through a conveyance deed or an instrument such as an allotment letter. Notification No. 23/2019-Central Tax (Rate), dated 30 September 2019 and effective from 1 October 2019, added an explanation that Notification 4/2018 does not apply to development rights supplied on or after 1 April 2019, so the two regimes do not overlap.

For a developer with several projects the date on which the development rights were first transferred therefore decides which regime applies, and that date has to be evidenced from the agreement, any registered deed or power of attorney and the related correspondence. The Tax Research Unit’s real estate FAQs of May 2019 also record that the exemption for development rights is available only for rights transferred on or after 1 April 2019. Commentary on the 2019 changes describes earlier transfers as taxable at 18 per cent with input tax credit.

Whether the transfer of development rights under a joint development agreement is a taxable service at all remains contested in the courts. The Telangana High Court upheld the levy in February 2024, and the Patna High Court in May 2025 declined to interfere with a reverse charge demand on construction service supplied against development rights. A Division Bench of the Bombay High Court in 2025 quashed a show cause notice on the footing that entry 5B reaches only a transfer of TDR or FSI as understood under the local development control regulations, not rights obtained under a private development agreement. Related questions are before the Supreme Court, and the GST Council has had the taxation of joint development agreements before a Group of Ministers. A developer should record both the character of the rights and the timing position, and revisit them as the law settles.

What counts as a booked apartment, and why it matters

The share of development rights that escapes tax, and the share of credit that is treated as attributable to exempt supply, both turn on whether an apartment was booked by the completion certificate or first occupation date. The 2019 notifications and Rules 42 and 43 define a booked apartment by three tests that must all be met by that date: at least part of the construction service has a time of supply on or before the date; at least one instalment has been credited to the registered person’s bank account; and an allotment letter, agreement for sale or similar document has been issued. A booking that exists only in a sales register, or one supported by a token paid in cash that never reached the bank, will not count.

Notification 06/2019 also deals with the other leg of an area-sharing arrangement. The construction service the promoter supplies to the landowner against development rights is brought within the same completion certificate or first occupation timing, so both legs of the swap crystallise on the same date and should be valued, documented and reconciled together. Because the value of unbooked apartments is taken at the price of similar apartments sold nearest to the completion certificate or first occupation date, the pricing history of the project becomes evidence in its own right and should be kept in a form that an officer can follow.

Frequently asked questions

1. When does GST on the transfer of development rights become payable?

Notification No. 06/2019-Central Tax (Rate), issued under section 148, provides that for notified promoters the liability arises on the date of issuance of the completion certificate by the competent authority, or on first occupation of the project, whichever is earlier.

2. Who pays the tax on development rights, the landowner or the developer?

The promoter, under reverse charge, by virtue of entry 5B inserted into the reverse charge notification by Notification No. 05/2019-Central Tax (Rate).

3. Is the transfer of development rights exempt?

Partly. Notification No. 04/2019-Central Tax (Rate) exempts it to the extent attributable to residential apartments booked before completion. The taxable portion therefore depends on how much of the project remains unbooked at the trigger date.

4. What rates apply to residential apartments?

Central tax of 0.75 per cent for affordable residential apartments and 3.75 per cent for other residential apartments and commercial apartments in a residential real estate project, with the matching state tax, giving effective rates of one per cent and five per cent. Both are without input tax credit and payable in cash.

5. What is the eighty per cent procurement condition?

At least eighty per cent of inputs and input services must be procured from registered suppliers, excluding development rights, long term lease of land, floor space index, electricity, high speed diesel, motor spirit and natural gas. The shortfall is taxed at eighteen per cent under reverse charge in the promoter’s hands.

6. How is cement treated?

Cement procured from an unregistered supplier attracts reverse charge at the applicable rate irrespective of whether the eighty per cent threshold is met, so it has to be tracked separately from the main computation.

7. How are the landowner’s constructed apartments valued?

As a supply of construction service for non monetary consideration, valued under section 15 and the valuation rules, in practice by reference to the price charged to independent buyers for similar apartments nearest the date of transfer of the development rights.

8. How is credit apportioned where a project has exempt and taxable elements?

Under Rules 42 and 43 as amended by Notification No. 16/2019-Central Tax with effect from 1 April 2019, computed per project on a carpet area basis, with unbooked apartments at the completion certificate or first occupation date forming part of the exempt element.

9. Is there a credit reversal for unsold inventory?

Yes. The apportionment treats apartments unbooked as at the completion certificate or first occupation date as attributable to exempt supply, so slower sales produce a larger reversal. A final computation is required with reversal and interest or re-credit as the case may be.

10. Could an ongoing project continue under the earlier rates with credit?

Yes, by an election exercised separately for each project by 10 May 2019. New projects commencing on or after 1 April 2019 are compulsorily under the new structure.

11. What is a booked apartment for the purpose of GST on development rights?

An apartment is treated as booked at the completion certificate or first occupation date only if three tests are met by that date: part of the construction service has a time of supply, at least one instalment has reached the promoter’s bank account, and an allotment letter or agreement for sale has been issued. Unbooked apartments are the taxable share.

12. How does the one-third land deduction work in the 1% and 5% GST rates for apartments?

Notification 11/2017-Central Tax (Rate) deems land to be one third of the total amount charged. The headline rates (central tax 0.75 and 3.75 per cent, plus equal state tax) apply on the remaining two thirds, which gives effective rates of one per cent for affordable and five per cent for other residential apartments on the full price.

13. Does GST on development rights apply to joint development agreements signed before 1 April 2019?

The 2019 exemption and deferred time of supply apply only to development rights transferred on or after 1 April 2019. Earlier transfers fall under Notification 4/2018-Central Tax (Rate), under which liability arises when possession or rights in the constructed property pass to the landowner. Notification 23/2019 confirms that Notification 4/2018 does not apply to later supplies.

14. When must the shortfall under the 80 per cent procurement rule be paid?

The promoter computes the shortfall in purchases from registered suppliers at the end of the financial year, and the 18 per cent reverse charge on it must be added to output tax liability by June following the year-end. Cement bought from unregistered suppliers is taxed separately, in the month of receipt, regardless of the 80 per cent test.

Talk to SBC’s tax team

If you are structuring a joint development agreement or reviewing an existing project against the 2019 framework, our indirect tax team can walk through the timing, valuation and credit positions with you before the agreement is finalised. Explore our GST services | Contact SBC

About the author

CA Mithilesh Reddy, Founder and CEO, Steadfast Business Consulting LLP, led the team that handled this engagement.

CA Rajesh Vaishnav is a Partner at Steadfast Business Consulting LLP. SBC provides direct and indirect tax, international tax and transfer pricing advisory and dispute support.

About SBC | Meet the SBC team

Disclaimer

This article is for general information and does not constitute professional advice. It reflects the law as understood at the date of publication and does not take account of later developments, including subsequent amendments to the rate and exemption notifications. The GST treatment of a joint development agreement turns on the terms of the particular agreement, the classification of the project and the facts of its execution. No reader should act on the basis of this article without taking advice on their own circumstances.

CategoriesBudget Direct Tax GST Indirect Tax

Indian Union Budget 2024 – SBC Update

Indian Union Budget 2024 - SBC Update

  • Home
  • Indian Union Budget 2024 - SBC Update
INDIA UNION BUDGET 2024-25

1. Roadmap for pursuit of Viksit Bharat
Roadmap for pursuit of Viksit Bharat

Macro Fiscal Cues:
• Inflation – Low and stable, moving towards the 4% target. Core inflation (non-food, non-fuel) at 3.1%.
• Total Receipts – Estimated at ₹32.07 lakh crore(excluding borrowings).
• Total Expenditure – Estimated at ₹48.21 lakh crore.
• Net Tax Receipts – Estimated at ₹25.83 lakh crore.
• Fiscal Deficit – Estimated at 4.9% of GDP, with a goal to reduce it below 4.5% next year.

Future Fiscal Strategy – From 2026-27 onwards, the aim is to ensure the fiscal deficit keeps Central Government debt on a declining path as a percentage of GDP.

2. Direct Tax Proposals


Revamped Act on its way


“I am now announcing a comprehensive review of the Income-tax Act,1961. The purpose is to
• make the Act concise, lucid, easy to read and understand
• reduce the disputes and litigation
• provide certainty to taxpayers”

It will also bring down the demand embroiled in litigation. It is proposed to be completed in six months.”

i. Individuals
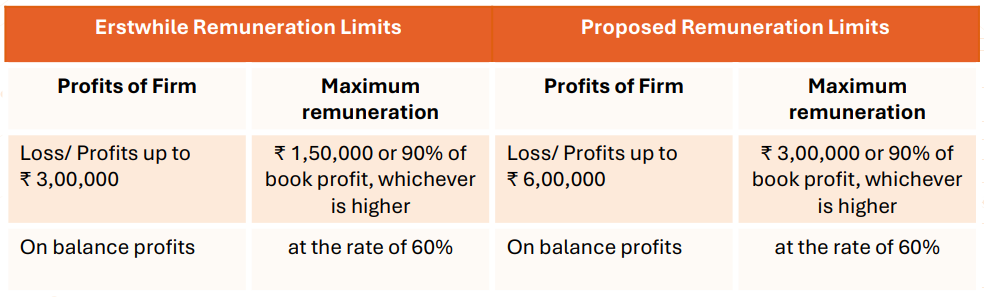
partnership firm

Above change results in savings of ₹17,500 to the individual taxpayers opting for New Regime

Other Key Proposals:

• Standard deduction under Section (u/s) 16 increased from ₹50k to ₹75k under the New Regime (Not eligible for Old Regime)
• Deduction for Employers’ contribution u/s 80CCD towards Pension scheme opting for New Regime increased from 10% to 14% of employee’s basic salary
• TCS paid by employees for the purpose of computing TDS required to be withheld from salary w.e.f. 01-Oct-2024 which was not previously allowed to be set off resulting in a tax refund situation
• W.e.f. 01-Oct-2024 under the Black Money and Imposition of Tax Act, 2015, failure to report/inaccurate reporting of foreign incomes / overseas assets will attract a penalty if the value of foreign assets does not exceed ₹20 lakhs u/s 42 and 43 (Previously the limit was ₹10 lakhs with an exception to the bank account(s) not exceeding ₹5 lakhs)
• TCS credit of the minor shall only be allowed where the income of the minor is being clubbed with the parent as under sub-section (1A) of section 64 of the Act

SBC Comments:

The Finance Bill 2024 proposes amending the slab rates while maintaining a baseline exemption of INR 300,000. It also increases the standard deduction for salaried taxpayers from INR 50,000 to INR 75,000, which provides only minimal tax benefits.

Although these amendments fall short of expectations, they represent a welcome step towards providing much-needed relief for individuals.

ii. Corporates


As per the information provided, 58% of corporate tax in FY 2022-23 was collected under the new corporate tax regime. Thereby, there are no changes proposed for Corporates and the old rates shall continue to apply as per the applicable regime.

Other updates apart from Transaction-related amendments are as follows:

a) Foreign Companies:

• Corporate tax rate for foreign companies reduced from 40% to 35%. ETR of 38.22% (including surcharge and health and education cess)

SBC Comments:

Reduction of corporate tax rate for foreign companies is anticipated to reduce the tax on business income and other income (not addressed by any specific provisions of the IT Act or treaty) of foreign companies, arising from their business connection or permanent establishment in India.

b) Pillar One and Pillar Two:

Withdrawal of the Equalisation Levy (EL) of 2% introduced in 2020.

• Hon’ble Finance Minister explained the rationale behind the withdrawal of EL of 2%. She stated that EL withdrawal is in the interest of moving towards Pillar One and Pillar Two.
• Consideration received or receivable for e-commerce supplies or services on or after this date will not be subject to the EL of 2%.
• However, EL of 6% on Online Advertisement Services shall continue.

SBC Comments:

There were hopes that this Budget might outline a roadmap for implementing the OECD’s Two Pillar framework in India. In this context, the withdrawal of the EL could have been seen as a preparatory step towards adopting the Two Pillar solution. However, the budget documents make no mention of Pillar 2 rules. The stated rationale for withdrawing the EL is not its alignment with the Two Pillar solution but rather concerns about the levy’s scope and compliance burden. It seems India is maintaining a wait-and-see approach regarding the Two Pillar Solution.

c) Submission of a statement by the liaison office of NR in India:

• NRs having a liaison office in India are required to prepare and deliver a statement in respect of its activities in a financial year to AO. New Section 271GC proposed for levy of a penalty of ₹ 1,000 for every day of failure to furnish such statement unless it proves to have reasonable cause.

d) Disallowance u/s 37:

• Expenditure incurred by an Assessee for any purpose which is an offence or which is prohibited by law shall include any expenditure incurred to settle proceedings initiated in relation to a contravention under any law.
• These expenses incurred on settlement in relation to a contravention under any law are to be notified by the Central Government, w.e.f. FY 2024-25.

SBC Comments:

Courts have ruled that settling a dispute is based on commercial expediency and business interests, aimed at ensuring the Assessee can continue its business operations without interruption. Consequently, any amount paid to settle a dispute was previously permitted as a business expense under Section 37(1) of the IT Act. However, with the addition of clause (iv) to Explanation 3 of Section 37(1), no deduction will now be allowed for expenditures incurred to settle such proceedings.

e) Taxation of domestic cruise ship operations by non-residents

• New presumptive taxation regime introduced for domestic cruise ship operations & exemption on lease rental in the hands of immediate NR sister company till FY 2029-30
• 20% of revenue of the NR operator, on account of carriage of passengers to be deemed as business income. Existing presumptive taxation regime for the shipping business of NR will not be applicable for NR’s domestic cruise operators.

SBC Comments:

India’s potential for cruise tourism is enhanced by its extensive coastal and riverine infrastructure. Additionally, the growing tourism in destinations such as Lakshadweep and other islands is anticipated to further boost the cruise tourism sector. Moving forward, foreign cruise shipping companies will have the option to choose a tax rate of 20%.It is important to note that previously, non-residents involved in shipping, including cruise shipping, were eligible for a presumptive tax rate of 7.5% on their total income.

iii. Trusts/Institutions


a) Merger of trusts under the first regime with the second regime:

• W.e.f 01-Oct-2024 applications for approval u/s 10(23C) shall be considered as per the provisions of Sections 11 and 12.

b) Condonation of delay in filing application for registration by trusts or
institutions:

• A trust or institution desirous of seeking registration under section 12AB is required to apply within timelines specified in clause (ac) of sub-section (1) of section 12A.
• It is proposed that the Principal Commissioner/ Commissioner may be enabled to condone the delay in filing applications and treat such applications as filed within time to help the genuine cases of delay.
• Similar provisions provided for Section 80G related application

c) Timeline for disposing of applications u/s 12AB and 80G provided:

• W.e.f. 01-Oct-2024, the timeline shall be six months from the end of the quarter in which the application was received

d) Donations to the National Sports Development Fund

• Any sums paid by the Assessee in the previous year as donations to the National Sports Development Fund set up by the Central Government shall be eligible for deduction for other taxpayers u/s 80G.
• Thus, such a fund can claim the benefit of donations accordingly as per Section 11 and 12 as well.

SBC Comments:

The alignment of both regimes and the proposed gradual transition to the second regime reflect a push towards procedural simplification and reduced administrative burden, ensuring a smoother and more efficient framework.

Care must be taken to ensure that the transition does not disrupt operations and claim of exemption/benefits. This requires clear guidance and support to the Trusts/such institutions for its tax matters.

iv. Partnership Firms


a) Increase in limit of remuneration to working partners of a firm allowed as deduction:

partnership firm

b) Other updates:

• Section 194T has been introduced to provide 10% TDS by the firm on payment salary, remuneration, commission, bonus or interest to a partner.
• Limit of ₹ 20,000 applicable for TDS chargeability u/s 194T in an FY.
• TDS to be deducted on payment/ accrual or transfer to partner’s capital account. Withholding obligations continue even on interest/ salary payments above specified limits
• No changes in the tax rates for the partnership firms as was expected in line with new regimes introduced for individuals, companies, co-operative society etc.,

Amendment applicable ideally from FY 2024-25

SBC Comments:

The proposed amendment to increase the deduction limit for working partners’ remuneration is a positive development, offering greater flexibility by allowing up to Rs 3,00,000 or 90% of the book profit on the first Rs 6,00,000 of profit or in the case of a loss. This change could enhance tax benefits for partnership firms and improve financial flexibility.

v. Capital Gains

a) Revised period of holding and rates for all Listed Securities:
capital gains

b) Revised period of holding and rates for Unlisted Assets:
capital gains

Currently, STCG is taxed @ 15% or the applicable slab rate and LTCG are taxed at 10% or 20%, depending on the residential status of the taxpayer and category of asset. However, w.e.f. 23-Jul-2024, STCG has been raised from 15% to 20% on specified assets. Other STCG shall continue to be taxed at the applicable slab rate and LTCG will be 12.5%

SBC Comments:

The proposed overhaul of long-term capital gains tax rates suggests a unified rate of 12.5% across all asset categories. Previously, the rate was 10% for STT-paid listed equity shares, units of equity-oriented funds, and business trusts under Section 112A, and 20% for other assets with indexation benefits under Section 112 of the IT Act.

This change equalizes tax rates for listed and unlisted shares, potentially impacting the private equity sector, where companies previously sought IPOs to benefit from the lower 10% tax rate. For promoters, this adjustment may reduce the incentive to use externalization structures for tax planning.

The present rate of tax of 15% for STCG was considered to be very low and largely benefitted the High-net-worth individuals. Increased tax on capital gains could reduce ROI and diminish some appeal of the booming Indian stock market. However, it does rationalize long-term capital gains taxation, addressing the previous disparity where residents faced higher rates compared to non-residents.

c) Key LTCG and Securities Transaction Tax takeaways:

• No indexation benefit in the case of any long-term capital assets.
• Increase in rates of STT on sale of an option in securities from 0.0625% to 0.1% of the option premium and on sale of a futures in securities from 0.0125% to 0.02% of the price at which such “futures” are traded.

SBC Comments:

The tax rate on other long-term assets has been lowered from 20% to 12.5%. While this change appears advantageous initially, the elimination of the indexation benefit could significantly impact taxpayers.

Indexation adjusts the asset’s purchase price for inflation, reducing the taxable capital gain. Without this adjustment, the entire gain is taxable, which could be a heavy burden, particularly when the return on investment vis-à-vis inflation there is disparity.

Further, on increase in STT, for the Futures and Options segment STT has nearly doubled, and the tax advantage of buybacks over dividends has been eliminated. While this may cause some short-term disruption in the stock market, history shows that such changes are often temporary, and the markets are likely to adapt and continue their growth.

d) Shares acquired as part of Offer for sale:

• Taxpayers in some cases are not paying capital gains tax on the transfer of shares acquired through the Offer for Sale (OFS) route citing the absence of an express provision for the determination of the FMV.
• The contention taken by taxpayers was that since they were still unlisted on the date of transfer even though STT has been paid on transfer and thus, the Cost of Acquisition is indeterminable, and Capital Gains is not chargeable.
• Section 55 amended to provide Mechanism to determine the cost of acquisition of equity shares acquired before February 1, 2018, and transferred as part of the Offer for Sale

Fair Market Value = Original cost of acquisition * (Cost Inflation Index for the financial year 2017-18)/(Cost Inflation Index for the 1st year in which the asset was held by the Assessee or for the year beginning on the 1st day of April 2001, whichever is later)

SBC Comments:

Previously, taxpayers used various methods to compute the cost of acquisition for shares offered under an OFS, including original cost, indexed cost, FMV based on valuers’ reports, or even arguing that the transaction wasn’t taxable due to computation issues. The proposed amendment aims to clarify this issue definitively. As it is a retrospective change, those who adopted aggressive positions will need to reassess and potentially revise their returns.

e) Gains from unlisted bonds and debentures:

• Gains from unlisted bonds and debentures transferred, redeemed or maturing on or after 23 July 2024 will be treated as STCG irrespective of the holding period.

SBC Comments:

Unlisted debentures and bonds are set to be taxed according to the rates specified under Section 50AA of the IT Act. Consequently, these instruments will not benefit from the reduced long-term capital gains tax rate.

vi. TDS/TCS Rates


a) Rationalisation of TDS/TCS rates:
Rationalisation of TDS/TCS rates:

SBC Comments:

The proposed amendments seek to rationalize TDS rates by lowering them on various provisions, which is expected to ease cash flow impacts. This change aims to enhance business efficiency and improve compliance.

The current rationalization is the first baby step which the Government has already taken towards simplification of the direct tax laws in India aiming to provide ease of business and certainty to the taxpayers and making India more attractive destination for FDI/Investments.

Apart from the above, it is to be noted that TCS has introduced on luxury expenses. The proposed expansion of this section to include any notified luxury goods will enhance the tracking of related expenses. Effective from January 1, 2025, this amendment is likely to improve transparency and ensure better compliance with expenditure regulations.

b) Scope of 194C to exclude payments u/s 194J:

• It is proposed to explicitly state that sum paid and liable u/s 194J does not constitute “work” for the purposes of TDS under section 194C. This is to provide certainty on the treatment of payments u/s 194C vis-à-vis 194J.

SBC Comments:

The proposed amendment clarifies that Section 194C does not apply to (i) transactions where TDS is deductible under Section 194J, or (ii) manufacturing or processing based on customer specifications when the material for manufacturing
or processing is not supplied by the customer or their associates.

c) Time limit for revision of TDS/TCS returns:

• Correction statements can be filed on TRACES/offline only within 6 years from the end of FY in which such TDS/TCS statements were filed.

SBC Comments:

Such statements could be revised repeatedly and indefinitely, potentially leading to misuse of these provisions and causing difficulties for deductees and collectees. Thus, this has been introduced to provide certainty and to avoid unwarranted litigation.

d) TCS suffered by employees to be considered for TDS deduction:

• Employers may now consider TCS suffered by employees when calculating TDS on employee salary payments w.e.f 01-Oct-2024.

e) Processing of statements other than those filed by the deductor:

• Scheme for processing of statements shall be made for filing by persons other than deductor viz., Form No. 26QF which is filed by an Exchange wherein the deductee is filing details of the tax

f) Lower TDS/TCS certificate for 194Q and 206C(1H):

• Lower TDS/TCS applications can now be filed for payments liable
– for TDS u/s 194Q for purchase of goods
– for TCS u/s 206C(1H) on sales of goods

g) Penalty for failure to furnish TDS/TCS statements:

• Time limit for not levying penalty u/s 271H reduced from 1 year to 1 month from the due date to ensure better compliance.

h) Time limit to pass order for failure to deduct/ collect or pay TDS/ TCS:

• The existing provision of Section 201(3) in the IT Act provided a time limit of 7 years for deeming a person to be an ‘Assessee in default’ for failure to deduct tax from a resident, whereas no time limit was prescribed in case of failure to deduct from a non-resident.
• Further there are no limits specified for passing an order under section 206C of the IT Act.
• It is proposed to amend section 201(3) to amend the time limit to 6 years for issuance of order deeming a person to be an ‘Assessee in default’, for failure to deduct part or whole of tax from any person, i.e., a resident and a nonresident.
• Further, it has been proposed to insert Section 206C(7A) providing that no order shall be made by deeming a person as an ‘Assessee in default’ in case of failure to collect tax after expiry of six years from the end of the financial year in which tax was collectible or two years from the end of the financial year in which the correction statement is delivered under sub-section (3B), whichever is later

SBC Comments:

All lacunae and shortfalls in the provisions are being addressed, which will enhance the operations of both taxpayers and tax authorities

vii. Transfer Pricing
 

transfer pricing

Other key points to be noted from the Finance Minister’s Speech:

a) With a view to reduce litigation and provide certainty in international taxation, CBDT will

• expand the scope of safe harbour rules and make them more attractive.
• streamline the Transfer Pricing (TP) assessment procedure.

It is exciting to see that the TP amendments have begun towards the extended vision of making the direct tax structure more certain. It would make India an attractive hub for more investments and further its growth story.

b) Vivad Se Vishwas Scheme, 2024 mechanism will ideally apply for TP adjustments and thereby enable expeditious disposal of pending disputes/litigations for TP litigations.

c) Interest limitation rules u/s 94B not to apply to financial companies operating in IFSC while other tax exemption framework proposed for Retail schemes and ETFs set up in IFSC

SBC Comments:

The amendment provides the authority to the TPO to determine ALP even if SDT are not reported in Form 3CEB.

viii. Transaction tax


a) Abolition of Angel Taxation i.e., fair value in excess of share premium abolished

• Issue of shares by closely held companies above FMV was liable to Angel Tax for the company issuing the shares. These provisions are proposed to be omitted from FY 2024-25 (AY 2025-26).
• Thus, the excess premium received by a company on the issue of shares shall no longer be taxable in the hands of the company as ‘Income from Other Sources’.

SBC Comments:

The proposed abolition of the Angel Tax represents a major milestone for domestic companies that have grappled with legal and practical issues under these contentious provisions. Historically, the Angel Tax led to disputes over valuation methodologies, treatment of estimated figures, scrutiny of funding sources, and taxation of equity conversions. Initially designed to curb black money, it ended up being used to tax shares issued above fair market value, resulting in extensive litigation and complications, especially for non-resident investors dealing with conflicting regulations (Exchange Control Regulations vs. IT Act) from FY 2023-24.

The Finance Minister’s decision to eliminate the Angel Tax (Section 56(2)(viib) of the IT Act) for all shareholder classes is a significant move towards increasing tax certainty, reducing litigation, and supporting the startup ecosystem. This change is expected to lessen burdens on investors, simplify deal negotiations, and streamline documentation processes. It also highlights the government’s commitment to fostering growth and innovation, enhancing the resilience and productivity of key sectors in the evolving economic landscape.

b) Corporate gifting of shares etc., to be taxable:

• It is now proposed to allow only gifts out of natural love and affection u/s 47 as not transfer and thus, not liable to tax.
• Tax positions of non-chargeability for corporate gifting can no longer be used.

SBC Comments:

The availability of benefits under Section 47 of the IT Act for transactions involving gifts from unnatural persons (e.g., transfer of shares by corporates at no consideration) has historically led to contention and litigation.

The proposed amendment to Section 47(iii) of the IT Act will apply prospectively. It will be important to assess the impact on transactions involving gifts by unnatural persons conducted before the new provisions take effect, especially in light of previous judgments on the matter.

c) Slump sale to be taxed as per the reduced period:

• Period of holding reduced to 24 months from 36 months to qualify for lower of tax on LTCG as a result of slump sale.

SBC Comments:

Slump sale may be structured for the reduced period enhancing the possibility of claim of LTCG on account of the reduced period.

d) Reduction of tax on foreign companies from 40% to 35% to benefit sale of unlisted shares

• Unlisted shares held for a period of less than 24 months shall be taxed at reduced rate of 35%

SBC Comments:

Reduction of corporate tax rate for foreign companies is anticipated to reduce the tax on business income and other income (not addressed by any specific provisions of the IT Act or treaty) of foreign companies, arising from their business connection or permanent establishment in India.

e) Taxation of Buy-back of securities:

• Any sum received by shareholders on buyback of shares shall be treated as dividend income in the hands of shareholders and shall be taxable at applicable rates.
• No deduction for expenses shall be available against such dividend income.
• Further, the cost of acquisition of shares bought back will be treated as a capital loss and shall be available for set-off / carry forward against other capital gains income as applicable.
• The amendment shall be applicable w.e.f. 01-Oct-2024

SBC Comments:

In the case of buy back, it remains unclear and has created ambiguity for many scenarios wherein the genuine cost of acquisition is not available for claim or set off against the amount received on buy-back.

Buy-back is a case of extinguishment of right in asset and the current provisions are void of this understanding while impacting the cash repatriation strategies through buy-back of shares.

viii. Litigation


a) Vivad se Vishwas Scheme, 2024:

• Keeping in view the success of the previous Vivad Se Vishwas Act, 2020 and the mounting pendency of appeals at the CIT(A) level, the introduction of a Direct Tax Vivad se Vishwas Scheme, 2024 is proposed which is yet to be notified. The objective is to provide a mechanism for the settlement of disputed issues, thereby reducing litigation without much cost to the exchequer.
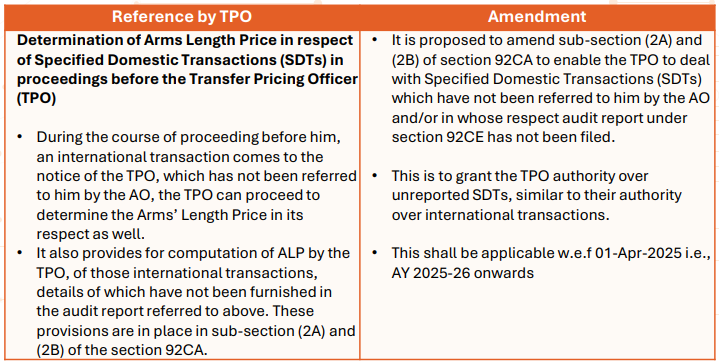
litigation

Where the tax department is in appeal or the disputed issue has already been decided by in favour of the declarant by a higher appellate forum, namely ITAT, High Court or the Supreme Court and is not overturned, the amount payable by the declarant shall be one-half of the amounts specified in column (4) and (5) of the above table (as applicable). The method of computation in such cases will be prescribed by the Government.

a) Vivad se Vishwas Scheme, 2024 (continued):

• The Scheme is applicable to an ‘appellant’, which would include the following person in whose case an appeal or a writ petition or special leave petition has been filed either by him or by the income-tax authority or by both; or objection before DRP or revision application u/s 264 has been filed by the person. Further such respective appeal or petition or DRP direction or application u/s 264 is pending or DRP direction has been issued and pending for give effect order by AO as on 22nd July 2024.

• Other conditions are similar to earlier scheme of 2020: a) Declaration has to be filed before designated authority b) Appeals are to be withdrawn and other remedies/claim are to be waived by the Appellant c) Neither the authorities nor the declarant can contend that the declarantappellant or the authorities, as the case may be, has acquiesced in the decision on the disputed issue by settling the dispute.

• Timelines under the above proposed Scheme:

Designated authority to determine the amount payable by the declarant within 15 days of filing the declaration. Thereafter, the declarant is to make payment and furnish proof thereof within 15 days thereafter.
• Exclusions from VSV Scheme where tax arrears relate to:
• Search cases
• AY for which prosecution is instituted before filing declaration
• Undisclosed foreign income and assets.
• Where assessment has been made on the basis of information from foreign countries
• Prosecution cases filed by the Department for offences punishable under the Bharatiya Nyaya Sanhita, 2023 or for the purpose of enforcement of any civil liability under any law for the time being in force, on or before the filing of the declaration or such person has been convicted of any such offence consequent to the prosecution initiated by an Income
tax authority.
• Prosecution has been initiated under Narcotic Drugs and Psychotropic Substances Act, Special Courts Act, the Unlawful Activities (Prevention) Act 1967, the Prevention of Corruption Act, the Conservation of Foreign Exchange and Prevention of Smuggling Activities Act 1974, the Prevention of Money Laundering Act 2002, the Prohibition of Benami Property Transactions Act, 2016 on or before filing of the declaration or such person has been convicted of any such offence punishable under any of those Acts.

SBC Comments:

The rising backlog of litigation, with appeals increasing faster than disposals, highlights the need for effective dispute resolution.

Building on the success of the Vivad Se Vishwas Act, 2020, the proposed Direct Tax Vivad Se Vishwas Scheme, 2024 aims to address this issue by offering a streamlined mechanism for settling disputes. This initiative is expected to reduce litigation costs and clear the backlog efficiently, benefiting both taxpayers and the tax administration.

A thorough analysis must be undertaken by the Taxpayers wherein they fall within the definition of the Appellant for the scheme and avail to save efforts and costs invested on litigating the matters.

b) Monetary limits for filing appeals increased for the department:

• The monetary limits for filing appeals related to direct taxes, excise and service tax in the Tax Tribunals, High Courts and Supreme Court have been increased to ₹ 60 lakh, ₹ 2 crore and ₹ 5 crore respectively.

c) Reporting of income from letting out of house property under ‘Income from House Property’

• Overriding the Supreme Court Decision in the case of Chennai Investments it is proposed to amend the section 28 of the Act.
• Thus, any income from letting out of a residential house or a part of the house by the owner shall not be chargeable under the head “Profits and gains of business or profession” and shall be chargeable under the head “Income from house property”.

SBC Comments:

The Supreme Court’s rulings in Chennai Properties & Investments Ltd. and Rayala Corporation (P.) Ltd. established that rental income should be classified based on the primary business intent, either as “business income” or “Income from House Property.”

Recent decisions by high courts have varied based on specifics, but the Finance Bill, 2024 clarifies that income from renting out a residential house will now be taxed as “Income from House Property.” This change specifically targets residential properties and requires developers and landlords to classify rental income accordingly. . In case the let-out unit is classified as a “residential house”, any income from such let out property should be taxed as “Income from
house property”.

d) Monetary limits for filing appeals increased for the department:

• The monetary limits for filing appeals related to direct taxes, excise and service tax in the Tax Tribunals, High Courts and Supreme Court have been increased to ₹ 60 lakh, ₹ 2 crore and ₹ 5 crore respectively.

e) Introduction of block assessment provisions in cases of search:

• ‘Block period’ shall consist of previous years relevant to six AYs preceding the previous year in which the search was initiated.
• Regular assessments for the block period shall abate. There will be one consolidated assessment for the block period. No other regular proceedings shall be done.
• Tax shall be charged at 60% for the block period on the undisclosed income
• No interest under the provisions of section 234A, 234B or 234C or penalty under the provisions of section 270A shall be levied or imposed.
• No access to the DRP during Block Assessments.
• No adjustments allowed for losses, depreciation, or partner payouts
• Penalty at 50% on tax payable for the undisclosed income.
• Time limit for completion of the block assessment 12 months from end of the month in which the authorisations /requisitions were made. Exclusion of 6 months for handing over seized material.

SBC Comments:

The proposed amendment revises the process for handling assessments related to search and seizure proceedings. Under the current scheme, such assessments are conducted under Sections 147 to 151A of the Income Tax Act, which primarily governs reassessments based on new or additional information.

The amendment introduces a distinct procedure specifically for block assessments in cases involving search and seizure operations.

This special procedure aims to streamline the process by separating it from the general reassessment framework.

f) Reopening of assessment/reassessments:

• Opportunity of being heard and principle of natural justice further strengthened.
• Information from survey u/s 133A can be used for reassessment. Revised time limits for reopening of assessment shall be as follows:
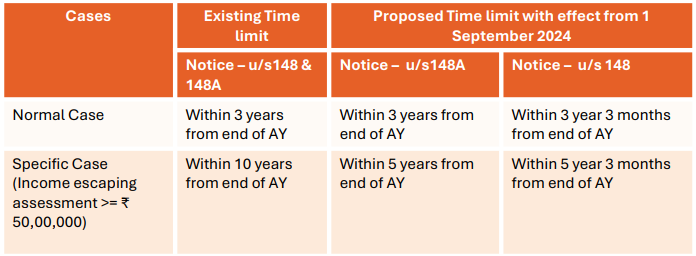
Reopening of assessment/reassessments

SBC Comments:

Currently, the time limit applies only to the issuance of notices under Section 148, often resulting in notices under Section 148A being issued close to the deadline for Section 148 notices, leaving insufficient time for adjudication.

The proposed amendment aims to address this by allowing authorities at least three months between issuing a show cause notice and a reassessment notice.

Additionally, the proposed changes will exclude search and seizure proceedings under Section 132 or requisitions under Section 132A from the revised reassessment scheme (Sections 147 to 151A). Instead, a separate block assessment scheme will be introduced for these cases.

g) Advance Rulings withdrawal facilitated:

• Section 245Q proposed to be amended to allow application for withdrawal by the 31-Oct24 for the transferred applications before Board for Advance Rulings (from AAR) in cases where order u/s 245R has not been passed.

h) Set aside and refer back to AO by CIT(A) in case of Best Judgement Assessment:

• For orders as best judgement case u/s 144 of the Act, CIT(A) shall be empowered to set aside the assessment and refer the case back to the AO for making a fresh assessment.

i) Time limit for completion of assessment, reassessment and recomputation:

• Where ROI is filed as per Condonation order u/s 119(2)(b) – Assessment u/s 143 or 144 can be done within twelve months from the end of the FY in which such return is furnished.
• Time limit introduced for set aside matters by CIT(A) u/s 250.
• The monetary limits for filing appeals related to direct taxes, excise and service tax in the Tax Tribunals, High Courts and Supreme Court have been increased to ₹ 60 lakh, ₹ 2 crore and ₹ 5 crore respectively.

j) Remaining services to be digitized:

All remaining services of Income Tax including rectification and order giving effect to appellate orders shall be digitalized and made paper-less over the next two years.

k) TDS Prosecution

In terms of Section 276B of the IT Act, any person who fails to pay TDS, is punishable with rigorous imprisonment of 3 months to 7 years along with fine.

A proviso is proposed to be inserted whereby, if the payment of such TDS has been made before or at the time of filing of the statement of TDS as required under Section 200 of the IT Act, then the said punishment would not be applicable. This amendment is proposed to come into effect from 01-Oct-2024.

SBC Comments:

This amendment aims to differentiate between a mere failure to report and non-payment of TDS within the prescribed period, and it seeks to decriminalize the former.

TDS Prosecution are most prevalent litigations currently. Thus, introduction of steps to curb the unwarranted litigation for TDS non deposit and prosecution therefrom where there can be genuine reasons for committing such defaults.

3. Indirect Tax Proposals

 
“To multiply the benefits of GST, we will strive to further simplify and rationalise the tax structure and endeavour to expand it to the remaining sectors.

My proposals for customs duties intend to support domestic manufacturing, deepen local value addition, promote export competitiveness, and simplify taxation, while keeping the interest of the general public and consumers surmount”

– Hon’ble Finance Minister during Budget Speech

i. Customs


a) Relaxation in Basic Customs Duty (BCD) Rates for certain items:
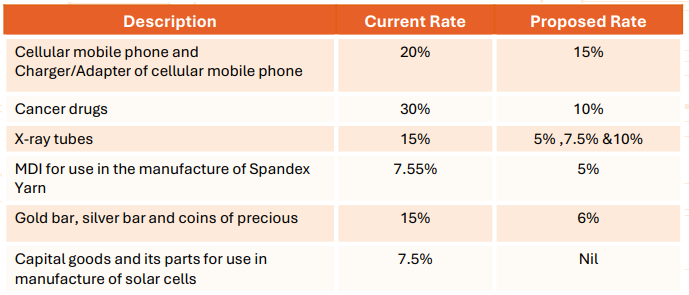
customs

b) Minerals such as lithium, copper, cobalt and rare earth elements are critical for sectors like nuclear energy, renewable energy, space, defence, telecommunications, and high-tech electronics. Proposal to exempt customs duties on 25 critical minerals.
c) Exemption of Social Welfare Surcharge (SWS) and reduction in Agriculture Infrastructure and Development Cess (AIDC) has been provided for certain goods

SBC Comments:

The Government has undertaken a comprehensive review in respect of 188 conditional exemptions/concessional rates (150 entries in Notification No. 50/2017-Customs dated June 30, 2017 and 38 exemptions/concessional rates in standalone Notifications).
– 30 exemptions/concessional rates are being extended up to 31-Mar-2029
– 126 exemptions/concessional rates are being continued up to 31-Mar-2026
– 28 exemptions/concessional rates are being lapsed on their end dates of 30-Sep-2024 While continuing the exemptions/concessional rates, some entries have been pruned or modified.

d) Ease of compliance:

• Currently, foreign-origin articles can be imported into India for repairs, provided they are re-exported within six months, which can be extended to one year. For aircraft and vessels imported for maintenance, repair, and overhauling, the re-export period has been increased from six months to one year, with a further extension available for an additional year.
• The duty-free re-import period for goods (excluding those under export promotion schemes) exported from India under warranty has been extended from three years to five years, with a possible extension of an additional two years.
• Section 28 DA has been amended to allow for the acceptance of various types of proof of origin as provided in trade agreements, aligning the section with new trade agreements that permit self-certification.

SBC Comments:

The proposed amendments to Section 28DA, which outlines the procedure for claiming a preferential duty rate, aim to expand the types of acceptable proof of origin beyond the traditional certificate of origin. This change aligns with new trade agreements entered into by the Government of India, which include self-certification or declaration by exporters as valid evidence of origin.

A proviso is being inserted to Section 65 (1), providing for manufacturing process or other operations in a warehouse licensed under the MOOWR Scheme. Vide this proviso, the Central Government is empowered to specify certain manufacturing and other operations in relation to a class of goods that shall not be permitted in a warehouse.

ii. GST


a) Amendments for Input Tax Credit:

• The time limit for availing input tax credit for an invoice or debit note pertaining to FY 2017-18 to FY 2020-21 has been extended, allowing it to be claimed in the GST return filed by November 30, 2021.
• The restriction on input tax credit for tax paid under sections 129 and 130, as well as tax paid under section 74 for demands, has been removed for FY 2024-25 onwards. This is in lines with the substitution of section 74 by section 74A.

b) Exclusions or new exemptions:

• Extra Neutral Alcohol (ENA) used in the production of alcoholic beverages for human consumption has been excluded from the scope of GST. This will provide respite to the liquor industry as ENA is a primary ingredient in manufacture of alcohol for human consumption.
• The activity of apportioning co-insurance premiums by the lead insurer to the co-insurer shall be considered neither a supply of goods nor a supply of services, provided the lead insurer pays GST on the entire premium amount.
• The deduction of ceding commission or reinsurance commission from the reinsurance premium paid by the insurer to the reinsurer shall be shall be inserted in schedule III and considered neither a supply of goods nor a supply of services, provided the reinsurer pays the GST liability on the gross reinsurance premium.
• A new Section 11A has been introduced to empower the government to regularize any non-levy or short levy of central tax resulting from prevalent general trade practices. This is a welcome move and shall aid in reducing litigation.

c) GST Refund:

• The refund benefit for unutilized input tax credit or integrated tax has been restricted for zero-rated supplies of goods that are subject to export duty.

d) Other key amendments:

• The time of supply for services where the invoice must be issued by the recipient in reverse charge situations has been amended to insert a new sub-clause – the date of issue of selfinvoices as prescribed under section 31(3)(f)
• A registered person required to deduct tax at source must file a return each month, regardless of whether any deduction has been made during that month.
• Sub-section (7) of section 140 of the CGST Act is being amended to allow for the utilization of transitional credit pertaining to eligible CENVAT credit on input services received by an Input Services Distributor before the appointed day, provided that invoices for these services were also received before the appointed date. This amendment comes into effect from 01-Jul-2017.
• A sunset clause has been prescribed for the Anti-profiteering Authority as of 31-Mar-2025. Any pending cases will be transferred to the Principal Bench of GSTAT.

iii.GST Litigation


a) Conditional waiver of interest and penalty:

• Section 128A is inserted to provide a conditional waiver of interest and penalty for demand notices issued under Section 73 of the Act for the Financial Years 2017-18, 2018-19, and 2019-20 (excluding demand notices for erroneous refunds).

b) Authorized Representative can appear for summons:

Provisions have been inserted to allow an authorized representative to appear on behalf of the summoned person before the proper officer.

c) Reduction in the amount of pre-deposit for filing appeal:
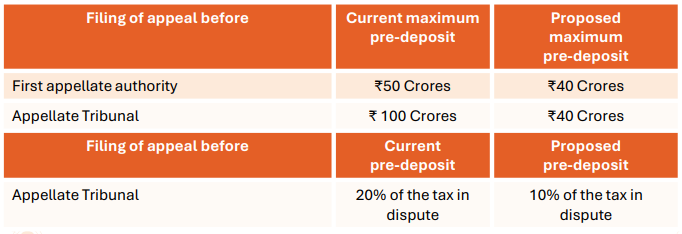
GST Litigation

d) Exclusive hearing before the Principal bench of Appellate Tribunal

Section 109 of the CGST Act is being amended to authorize the Government to designate specific types of cases that will be exclusively heard by the Principal Bench of the Appellate Tribunal.

e) E- Commerce Operators:

Sub-section (1B) of section 122 of the CGST Act is being amended to limit its application to electronic commerce operators obligated to collect tax at source under section 52 of the Act. This amendment will be effective from October 1, 2023, the date when the sub-section originally came into force.

SBC Comments:

The proposed amendments are designed to streamline the GST Appellate Tribunal’s operations and clarify the appeal process. They include provisions for the Government, based on the GST Council’s recommendations, to designate certain cases or categories of cases to be heard exclusively by the Principal Bench.

This is a positive development, as it ensures that industry-wide issues are addressed by the Principal Bench, following the Council’s recommendations and Government notifications.

Currently, appeals to the Appellate Tribunal must be filed within three months from the date the order is communicated. The Removal of Difficulty Order No. 09/2019-Central Tax dated December 3, 2019, clarified that the three-month period starts from the later of either the date of communication of the order or the date the President or State President of the Appellate Tribunal assumes office.

All other amendments are in line with the recommendations of the 53rd GST Council Meeting.

• The proposed amendment for ISD will provide huge relief to several taxpayers who have transitioned closing balance of erstwhile ISD directly to the GST registration which remained blocked till now.

• E-commerce operators who are required to collect tax at source under Section 52 of the CGST Act are obligated to comply with the provisions prescribed under the CGST Act.

Accordingly, the penalty provision under Section 122(1B) of the CGST Act is being amended to restrict its applicability to only to such registered E-commerce operators who are required to collect tax at source under Section 52 of CGST Act, and not in the case of other registered E-commerce operators.

• Other provisions provide the much needed certainty to the everchanging GST Laws

f) Harmonize the limitation period for the issuance of notices and orders for both fraud and non-fraud cases:
Harmonize the limitation period for the issuance of notices and orders for both fraud and non-fraud cases

SBC Comments:

Section 74A is being introduced in the CGST Act to address tax liabilities related to the FY 2024-25 onwards – For tax not paid, short paid, erroneously refunded, or input tax credit wrongly availed or utilized for any reason.

Limitation period as prescribed applies irrespective of whether charges of fraud, wilful misstatement, or suppression of facts are invoked. Additionally, higher penalties are stipulated for cases involving fraud, wilful misstatement