CategoriesTransfer Pricing

Transfer Pricing for Pharmaceutical Companies: Who Earns What?

Written by Jayasri P · Last updated 26 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: Transfer pricing in an Indian pharmaceutical group pays each entity for what it actually does. A contract research unit earns a cost-based margin, a contract or loan-licence manufacturer a routine manufacturing return, and a distributor a distribution margin. The residual profit follows the entity that owns and controls the product intangible under Section 165 of the Income-tax Act 2025.

Transfer pricing for pharmaceutical companies is unusually contested because the same molecule passes through three or four related parties before it reaches a patient, with research sitting in one entity, active ingredient and formulation manufacturing in another, and promotion to prescribers in a third. Each step generates a claim on profit, and Indian transfer pricing decides how much of that claim each entity may keep.

Transfer pricing advisory services in India: what does a pharmaceutical group need?

A pharmaceutical group needs three things from a transfer pricing adviser: a defensible characterisation of every Indian entity, a benchmarking file supporting the margin each one reports, and a documented position on who owns the product intangible. Method selection matters far less than characterisation, because comparable data cannot rescue a file that has assigned the wrong role to the entity it is testing.

Steadfast Business Consulting (SBC), recognised as a Notable Transfer Pricing Firm 2024 by ITR World Tax and founded by Big 4 alumni, lists contract manufacturing arrangements, royalty structures and research and development cost allocation among the pharmaceutical matters covered by its transfer pricing services in India, alongside documentation, benchmarking and safe harbour work.

How does the pharmaceutical value chain split into transfer pricing entities?

The chain splits into four recognisable roles, each carrying its own return, and those roles matter far more than entity names because a single Indian company frequently performs two of them and must report a separate margin for each.

Value chain role What the entity does Usual characterisation Where its return comes from Principal exposure
Contract research Runs studies and development batches on the principal’s instructions Routine service provider, insignificant risk Mark-up on operating expense Whether it in fact carries development risk
Contract or loan-licence manufacturing Produces active ingredients or formulations to a specified process Routine manufacturer Mark-up on cost, or a resale-based return Whether it owns the process or the registration
Marketing and distribution Sells finished goods in India and carries the field force Limited-risk or full-fledged distributor Distribution margin on sales Promotional spending treated as a separate transaction
Principal or intangible owner Holds the registration, funds development, bears market risk Entrepreneur Residual profit after routine returns Whether it controls the functions it is paid for

Why does a single Indian company often occupy more than one role?

Because Indian pharmaceutical operations grew organically rather than by design. A company that began as an export manufacturer typically added a development centre and then a domestic sales division, without ever separating those transactions in its transfer pricing file. Rule 84(1)(f) of the Income-tax Rules 2026 requires a record of financial estimates prepared for the business as a whole and for each division or product separately, so the obligation to look through the entity to its activities already sits in the documentation rule.

Segmental accounts are the answer, built from the cost accounting system rather than reconstructed at year end. A single profit and loss account covering research, manufacturing and distribution invites the Transfer Pricing Officer to pick the segment with the highest margin.

Who owns the product intangible in a pharmaceutical group?

The entity that funds, directs and controls the development of a product owns the return on it, not necessarily the entity named on the certificate. Pharmaceutical files fail here more than anywhere else. Ownership in this sector is spread across several instruments at once, and a file naming only one of them has not answered the question it was written to answer.

Is the dossier separate from the patent?

Yes, and treating them as one thing is a common drafting error. A pharmaceutical product carries a patent or process know-how, a regulatory dossier, the marketing authorisation granted on that dossier, and a brand, and because those four can sit in four different entities each generates a return that has to be identified separately.

For a generic group the dossier is often the most valuable, embodying years of bioequivalence and stability work.

What happens when the Indian entity funds development but the parent holds the registration?

The funding entity is entitled to more than a service fee, and how much more depends on whether it also controlled the work. Legal title alone does not carry the residual profit, and the analysis establishing economic entitlement is set out in our note on who owns the return on group intangibles.

Where a licence settles the arrangement instead, the rate becomes the pressure point, and a rate copied from a database without a comparability adjustment rarely survives. Building one is addressed in what royalty rate is defensible under Indian transfer pricing.

How are contract research and development arrangements priced?

Contract research is priced on a mark-up over operating expense, applied through the transactional net margin method in most Indian files. The arm’s length price is determined under Section 165 of the Income-tax Act 2025, with the prescribed methods set out in Rule 79 of the Income-tax Rules 2026 and the selection criteria in Rule 80.

The cost base is where the argument starts. Pass-through costs such as clinical trial site payments and third-party laboratory charges are routinely excluded from the base carrying the mark-up, and that exclusion must be justified rather than simply applied.

What is the safe harbour margin for contract research on generic pharmaceutical drugs?

An operating profit margin of not less than 24% on operating expense, where the aggregate operating revenue from the transaction does not exceed ₹300 crore in the tax year. This sits in the table at Rule 89(2) of the Income-tax Rules 2026, made under the power in Section 167 of the Income-tax Act 2025.

Three conditions carry it: Rule 87(1)(d) treats a person providing contract research and development services wholly or partly relating to generic pharmaceutical drugs, with insignificant risk, to a foreign principal as an eligible assessee, Rule 88(d) makes that provision an eligible international transaction, and Rule 90 governs the exercise of the option.

Note what the threshold excludes. An arrangement generating more than ₹300 crore falls outside the safe harbour entirely and returns to full benchmarking, a real cliff for a group approaching that level. The wider framework is set out in our overview of safe harbour rules under Indian transfer pricing regulations.

What disqualifies a research unit from insignificant-risk treatment?

Conduct, not contract. Rule 87(3) directs that the foreign principal must perform the economically significant functions in the research cycle, including conceptualisation, product design and strategic direction, and must supply the funds and the intangibles the work requires.

The rule then closes the obvious escape route, providing that where a contract obliges the foreign principal to control risk but the conduct shows the Indian entity doing so, the contractual terms are not the final determinant. The Indian entity must also hold no ownership right, legal or economic, over the outcome of the research.

How is contract or loan-licence manufacturing remunerated?

A contract manufacturer earns a routine return, because it converts inputs to a specified process without owning the process, the registration or the market. The mark-up is normally tested on total cost. Comparables come from independent formulation or active ingredient manufacturers rather than from integrated pharmaceutical companies, whose margins reflect intangibles a contract manufacturer does not hold.

Does a loan-licence arrangement change the characterisation?

It changes the facts to be documented, not the principle. Where one company manufactures using the licence and premises of another, the party holding the product registration and bearing market risk takes the residual, while the party contributing capacity earns only a routine return for the capacity it supplies.

Which of the two the Indian entity actually is, is the question. An Indian company manufacturing on its own licence but to a related party’s specification, formula and quality release sits closer to a contract manufacturer than the licence position alone suggests.

Which method applies to a manufacturing arrangement?

Cost plus or the transactional net margin method in most Indian manufacturing files, with the resale price method reserved for cases where the Indian entity resells without substantial transformation. The choice is governed by Rule 80, and the two cost-based routes are compared in which transfer pricing method applies to your transaction.

Once the method generates multiple prices, Rule 81 states that a margin which is outside the range generated will not be reset to the closest edge of that range.

Why does marketing spend in pharmaceutical distribution attract adjustment?

Because pharmaceutical promotion is large, prescriber-directed and long-lived, which makes it look like brand building rather than selling. An Indian distributor typically funds a field force of medical representatives, prescriber engagement, medical education and launch programmes, at a share of sales well above ordinary consumer distribution.

The department’s position is that spending beyond what an independent distributor would incur enhances a brand the foreign affiliate owns, and so requires compensation. The taxpayer’s position is narrower. That spending buys current-period sales, inside the Indian entity’s own margin.

What is the threshold question before any adjustment?

Whether an international transaction exists at all. An adjustment presupposes a transaction between associated enterprises within Section 163 of the Income-tax Act 2025, with associated enterprise defined in Section 162, and that transaction must be established on evidence rather than inferred from a comparison of spending levels.

There the file does its work. A group able to show that the Indian entity set its own promotional plan, kept the commercial benefit in its own margin, and was neither directed nor selectively reimbursed by the brand owner has answered the question before it is asked, and the documents proving that point cannot be created after a notice arrives.

What documentation does a pharmaceutical group have to keep?

The information and documents listed in Rule 84 of the Income-tax Rules 2026, prescribed under Section 171 of the Income-tax Act 2025. The obligation applies where the aggregate value of international transactions recorded in the books exceeds ₹1 crore in the tax year, under Rule 84(2).

Rule 84(1)(e) carries most of the weight, requiring a description of the functions performed, risks assumed and assets employed by the Indian entity and by each associated enterprise, which is where a chain spanning research, manufacturing and marketing is either explained or exposed.

The accountant’s report under Section 172 is furnished separately, in Form 48, which replaced Form 3CEB, and an accountant prepares that report while the Transfer Pricing Officer examines the file it accompanies on a reference made under Section 166.

Where should a pharmaceutical group start?

With characterisation, before benchmarking. Map each Indian entity to one of the four roles above, confirm its accounts can produce a segmental margin for every role it performs, and only then select comparables. If your group has added a development centre, changed its manufacturing model or launched a domestic portfolio since the last documentation cycle, put the arrangement in front of the SBC transfer pricing team before the current year closes.

Frequently Asked Questions

Does the safe harbour cover contract manufacturing in pharmaceuticals?

No. The safe harbour provisions under Rule 89(2) of the Income-tax Rules 2026 provide for contract research and development services relating to generic pharmaceutical drugs, not for manufacture of pharmaceutical products. Manufacturing contracts are compared in the general manner under Rule 80, with no specific margin to be applied to determine the arm’s length price.

What margin does a contract research unit have to report?

Not less than 24% of operating expense to use the safe harbour, and only where the transaction’s aggregate operating revenue stays within ₹300 crore for the tax year. Outside the safe harbour there is no fixed margin, and the reported result must fall inside the arm’s length range determined under Rule 81.

Who owns the regulatory dossier for transfer pricing purposes?

The entity that funded and controlled the development work, which is not always the entity holding the marketing authorisation. Legal title is a starting point rather than the answer. Where an Indian entity built the dossier, its entitlement has to be quantified and documented instead of being absorbed into a service fee.

Is promotional spending automatically a transfer pricing adjustment?

No. An adjustment requires an international transaction between associated enterprises to be established first, on evidence. A comparison showing that the Indian entity spends more on promotion than selected comparables does not by itself create that transaction, although such comparisons continue to appear in show-cause notices.

Do these rules apply to a purely domestic pharmaceutical group?

Only where the transactions are specified domestic transactions within Section 164 of the Income-tax Act 2025, and then only where their aggregate value exceeds ₹20 crore in the tax year. Groups below that threshold fall outside the regime, though international transactions remain covered.
CategoriesTransfer Pricing

Which Manufacturing Entity Characterisation Fits Your Subsidiary?

Written by Jayasri P · Last updated 26 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: An Indian manufacturing subsidiary is characterised by the risks it actually bears, not by the label in its agreement. A contract manufacturer earns a routine mark-up on cost, a limited-risk distributor a routine margin on sales, and a full-risk entity the residual profit and the losses. Section 165 of the Income-tax Act 2025 then decides the method.

Most disputes over an Indian manufacturing subsidiary begin with a label. The agreement names the Indian company a contract manufacturer, while the accounts show inventory write-downs, a domestic sales force and warranty provisions carried on the Indian balance sheet.

Those are the marks of an entity bearing risk, and an officer reading the accounts will price it as one whatever the agreement says.

Manufacturing entity characterisation is a finding of fact about who decides, who funds and who absorbs the downside. The return follows from the finding, and the method follows from the return.

What does entity characterisation decide for a manufacturing subsidiary?

It decides three things: which side is tested, which method applies, and how much of the group’s profit India expects the Indian company to keep.

The determination sits in Section 165 of the Income-tax Act 2025, headed “Determination of arm’s length price”. It answers to Section 92C of the Income-tax Act 1961 for earlier tax years. Characterisation is how the facts that section works on are organised.

What are the four manufacturing entity characterisations?

Indian practice recognises four positions along a single axis of risk: contract manufacturer, licensed manufacturer, limited-risk distributor and full-risk entity. The axis runs from an entity paid for its costs to an entity that runs a business and keeps what is left.

Characterisation What the entity does Risks it bears Intangibles Return it earns
Contract manufacturer Manufactures to the principal’s specification and order volumes Operational and capacity risk only None owned Routine mark-up on its own cost base
Licensed manufacturer Manufactures under licensed technology and sells in the local market Some market and inventory risk Licensed in, royalty paid out Routine return, uplifted for the risks genuinely taken
Limited-risk distributor Buys finished goods from the group and resells with little transformation Limited inventory and credit risk None owned Routine margin on sales
Full-risk entity Decides what to make, funds it and sells it on its own account Market, inventory, credit, warranty and product risk Owns or has developed its own The residual, positive or negative

What is a contract manufacturer?

A contract manufacturer converts inputs into finished goods on terms the principal sets, and it does not decide what is produced, in what quantity or for which market, while title to raw materials may or may not pass to it depending on how the arrangement is drawn. A toll manufacturer is the thinnest version of the same position. Title never passes at all.

The test is not the presence of a factory but the absence of discretion. Where the principal fixes volumes, absorbs unsold stock and carries the consequences of a product failing in the market, the Indian entity is paid to run a plant rather than a business.

What is a licensed manufacturer?

A licensed manufacturer uses group technology under licence, pays a royalty for it and sells into the local market on its own account. It sits between the contract manufacturer and the full-risk entity, and it is argued about most often.

The royalty is what makes it contentious. Paying for licensed technology while also bearing local market risk is a coherent position, but the file has to show that the royalty is priced for what was licensed and that the Indian entity is separately compensated for the risks it absorbs.

What is a limited-risk distributor?

A limited-risk distributor buys finished goods from a related party and resells them with little or no transformation. Its contract keeps inventory, credit and market risk with the principal. Many Indian groups run one alongside a plant, so a single legal entity carries both transactions.

That matters because characterisation is applied transaction by transaction, not entity by entity. Our note on FAR analysis and the routine or entrepreneurial classification sets out how the functional analysis reaches that split.

What is a full-risk entity?

A full-risk entity decides its own product range, funds its own working capital, sets its own prices and keeps whatever the business earns. It is an entrepreneur, and it is not a candidate for benchmarking.

An entity of this kind should not be the tested party, because independent companies performing the same entrepreneurial role in the same market rarely exist in usable numbers, and a search stretched far enough to find them produces a comparable set an officer can dismantle line by line. The routine side is tested instead, and the residual falls where the risk sits.

What return does each characterisation earn?

The return is set by the profit level indicator the characterisation supports, and each one is measured against a different base.

Characterisation Profit level indicator usually applied Base it is measured on
Contract manufacturer Net cost plus mark-up Total operating cost
Licensed manufacturer Operating margin on sales Net sales
Limited-risk distributor Operating margin on sales, or berry ratio where value added is slight Net sales, or gross profit over operating expense
Full-risk entity Not tested; retains the residual Not applicable

Why does the profit level indicator follow the characterisation?

Because the indicator must be measured on what the entity actually controls. A contract manufacturer controls its cost base and nothing else, so testing it on sales would reward or punish it for demand it never influenced.

A distributor is the reverse. It influences the volume it moves and the price at which it clears stock, so sales are the honest denominator. Our comparison of the resale price method and the cost plus method sets out which side each one examines.

How do you evidence the characterisation?

You evidence it with the agreement and the conduct together. The second carries more weight than the first, because an inter-company agreement describing a contract manufacturer proves very little where the Indian entity is writing off obsolete stock every year, funding its own advertising and settling warranty claims out of its own accounts.

What must the inter-company agreement record?

It must record the allocation of each risk, the party that funds it and the mechanism by which the principal absorbs it. A clause stating that the principal bears inventory risk needs a matching commercial term, such as a take-or-pay commitment or a stated buy-back, or it is a statement of intent rather than an allocation.

Rule 84 of the Income-tax Rules 2026 lists the information and documents to be kept and maintained under Section 171(1), and it carries forward the substance of Rule 10D of the Income-tax Rules 1962. The functional analysis and the agreements sit inside that record, which is why characterisation is a documentation obligation and not a preliminary step.

What conduct evidence does a Transfer Pricing Officer look for?

The officer looks for the accounting consequences of risk: inventory provisions, warranty provisions, bad debt written off, advertising and market development spending, and the location of the people who decide product specification and pricing are all read as evidence of who is actually running the business.

Where the file cannot explain why a stated contract manufacturer carries those items, the matter may be referred to a Transfer Pricing Officer under Section 166 of the Income-tax Act 2025, the successor to Section 92CA, and recharacterisation at that stage is expensive because an officer who reopens the question usually restates several years at once.

Which method follows from each characterisation?

Rule 79 of the Income-tax Rules 2026 sets out the methods for the purposes of Section 165(2). Rule 80 requires the most appropriate one to be selected on the facts. Neither rule ranks the methods, so the characterisation is what makes one of them defensible.

A contract manufacturer is normally tested on its cost base, a limited-risk distributor on its resale margin, and a licensed manufacturer on its operating margin, because gross-level comparability across an accepted comparable set can rarely be established from Indian published financial statements prepared on differing accounting policies. Rule 81 then governs the arm’s length range where the chosen method produces more than one price, carrying forward Rule 10CA of the Income-tax Rules 1962.

Does safe harbour cover a manufacturing entity?

Only in one narrow case. The safe harbour route under Section 167 of the Income-tax Act 2025 reaches manufacturing through a single category, and general contract manufacturing is not in it.

What margins does Rule 89 set for auto components?

Rule 89(2) of the Income-tax Rules 2026 accepts the declared price where the operating profit margin in relation to operating expense meets a stated floor.

Eligible international transaction Operating profit margin on operating expense
Manufacture and export of core auto components Not less than 12%
Manufacture and export of non-core auto components Not less than 8.5%

Core auto components are defined in Rule 86 and cover engine and engine parts, transmission and steering parts, suspension and braking parts, and lithium-ion batteries for electric or hybrid electric vehicles, while non-core auto components are everything else falling within the category.

The eligibility condition is strict, because Rule 87(1)(e) admits an assessee engaged in the manufacture and export of core or non-core auto components only where 90% or more of total turnover during the tax year is original equipment manufacturer sales.

When does safe harbour become unavailable?

Rule 92 removes the whole safe harbour framework for international transactions where the associated enterprise is located in a country or territory notified under Section 176, or in a no tax or low tax country or territory.

Accepting safe harbour also closes a route, because Rule 93 provides that once the declared transfer price is accepted under Section 167 the assessee cannot invoke the mutual agreement procedure under the relevant tax treaty, so the certainty is bought at the cost of the bilateral remedy.

What happens when the characterisation changes?

A change in characterisation is a restructuring, and it is priced as one. Moving a full-risk entity to a contract manufacturing model transfers profit potential out of India, and the Indian entity is expected to be compensated for what it surrenders, whether that is a customer base it built, a workforce it trained or an intangible it funded over several years, which is why the change belongs in the file before the year in which it takes effect.

Our note on when a business restructuring triggers an exit charge covers how the compensation is analysed, and Section 170 of the Income-tax Act 2025 governs the secondary adjustment that follows a primary adjustment left unrepatriated.

Which are the best transfer pricing firms for a mid size company?

No firm is best in the abstract, and a mid-size manufacturing group should select on depth in the specific question it faces rather than on network size. For a characterisation question the relevant depth is functional analysis and assessment experience, not headcount.

Three checks separate firms usefully: whether the adviser interviews the plant and commercial teams rather than working from the agreement alone, whether it documents why each risk was allocated as it was, and whether it has carried a characterisation position through assessment and appeal.

Global networks such as Deloitte, EY, PwC, BDO, Grant Thornton and RSM bring multi-country coverage where the group has entities in several jurisdictions. Independent Indian practices bring partner-level attention on a single jurisdiction, which is often what a mid-size group with one Indian plant actually needs. Neither category is better in the abstract.

Steadfast Business Consulting (SBC) prepares the functional analysis, benchmarking and documentation that support a manufacturing characterisation through its transfer pricing practice. SBC was named a Notable Transfer Pricing Firm 2024 by ITR World Tax, was founded by former Big 4 professionals with combined experience exceeding 150 years, and works from offices in Hyderabad, Mumbai, Pune and Dubai.

If your Indian entity has taken on functions or risks it did not carry three years ago, ask the SBC team to review the characterisation before the earlier position is repeated in the current file.

Frequently Asked Questions

Does the inter-company agreement decide the characterisation?

No. The agreement is the starting point, and conduct decides the outcome. Where the Indian entity bears inventory, credit or market risk in practice, a contract manufacturing label will not hold. Rule 84 of the Income-tax Rules 2026 requires the functional analysis and the agreements to sit in one documentation record.

Can one company be a contract manufacturer and a distributor at once?

Yes. Characterisation is applied transaction by transaction, so an Indian company may manufacture on contract for a group principal and separately distribute goods bought from another group entity. Each transaction needs its own functional analysis, its own tested-party conclusion and its own method.

Which entity should be the tested party?

The less complex one. A contract manufacturer or a limited-risk distributor performs routine functions, owns no unique intangibles and can be benchmarked against independent companies. A full-risk entity holding its own intangibles has few genuine comparables, so testing it produces a range that will not survive examination.

Is a contract manufacturer eligible for safe harbour?

Only in the auto components category. Rule 88 of the Income-tax Rules 2026 lists manufacture and export of core and non-core auto components as eligible international transactions, and general contract manufacturing does not appear. Rule 87(1)(e) also requires 90% or more of turnover to be original equipment manufacturer sales.

Does characterisation apply to domestic manufacturing arrangements?

It can. Section 164 of the Income-tax Act 2025 brings specified domestic transactions into the regime where the aggregate value of such transactions exceeds ₹20 crore in the tax year. The functional analysis works the same way, and the same evidence of risk allocation is required.

How often should a manufacturing characterisation be reviewed?

Review it whenever functions, assets or risks move, and before each documentation cycle. Characterisation drifts quietly as an entity adds a sales team, takes on warranty obligations or begins funding its own development work, and an analysis rolled forward without testing will state a position the accounts contradict.

CategoriesTransfer Pricing

Transfer Pricing for IT and Software Services in India

Written by Jayasri P · Last updated 26 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: Indian information technology and software companies attract heavy transfer pricing scrutiny because most of them bill a related party abroad for development work. The Union Budget 2026-27 announced a fast-tracked unilateral advance pricing agreement for information technology services, targeted for conclusion within two years, together with a higher safe harbour threshold and automated approval.

Why do software companies face more transfer pricing scrutiny than most sectors?

Because the typical Indian software company sells almost everything it produces to a single related party abroad, and transfer pricing applies to precisely that transaction. A domestic manufacturer selling to third parties has an observable market price. An offshore development centre billing its own parent has none.

Three features compound the exposure. The transaction is a service rather than a product, so no price can be observed anywhere in the market; the value sits in people and in code rather than in tangible assets, which makes the functional analysis genuinely contestable; and the amounts are both large and recurring, so an adjustment sustained for one year usually implies the same adjustment for every year that follows.

Determination of the arm’s length price is governed by Section 165 of the Income-tax Act 2025, which replaced Section 92C of the Income-tax Act 1961 with effect from 1 April 2026. Rule 79 of the Income-tax Rules 2026 carries the prescribed methods, and Rule 80 governs the selection of the most appropriate one.

Documentation sits at Section 171 and Rule 84, while the accountant’s report, now Form 48 rather than Form 3CEB, is furnished under Section 172 and Rule 85.

What changed for information technology services in 2026?

Three things, each aimed at the same complaint: that a software company could not obtain certainty on its margin inside a commercially useful period.

The Union Budget 2026-27 announced a fast-tracked unilateral advance pricing agreement process for information technology services and raised the safe harbour threshold for the sector from ₹300 crore to ₹2,000 crore, and safe harbour for information technology services is now to be approved through an automated, rule-driven process rather than examined case by case.

No other sector has been given such a package in the same budget. This indicates where the Government thinks the actual level of transfer pricing disputes lies.

How fast is a fast-tracked unilateral advance pricing agreement meant to be?

Two years, extendable by a further six months on the request of the taxpayer.

The two-year figure is a stated endeavour rather than a statutory deadline, and it reaches the unilateral route only, since a bilateral agreement depends on a foreign competent authority and cannot be compressed by India acting alone. Advance pricing agreements continue to be governed by Section 168 of the Income-tax Act 2025.

What matters commercially is the horizon rather than the speed in itself. An agreement concluded inside two years covers years that are still open, which is a materially different proposition from one arriving after the assessment has been framed and appealed. SBC has set out the application process and Form 51 separately.

What did the safe harbour change do for a software company?

It moved the election from a niche option into a mainstream one.

Under the Income-tax Rules 2026 the several technology service categories were consolidated into a single information technology services category taking one margin of 15.5 per cent, and the value ceiling rose to ₹2,000 crore of aggregate operating revenue, which brings a materially larger company inside the election than the earlier rules ever allowed. Those margins and conditions are covered in the guide to transfer pricing for a global capability centre or captive unit.

Safe harbour remains an election rather than a right. Accepting it means accepting a prescribed return which may sit above the return a properly benchmarked analysis would support, in exchange for removing the enquiry altogether.

Why is an offshore development centre’s margin contested?

Because the declared margin rests on a characterisation the taxpayer asserts and the Transfer Pricing Officer is entitled to test. A routine contract developer earns a modest cost-based return, and an entity carrying real entrepreneurial risk does not.

Most Indian offshore development centres are documented as low-risk contract service providers, remunerated on a cost-plus basis and benchmarked under the transactional net margin method with a cost-based profit level indicator. That characterisation is usually correct, and it also carries the lowest return, which is why it attracts examination.

What pushes a development centre above a routine return?

Functions the contract does not describe, and risks the entity bears in practice rather than on paper.

Product roadmap ownership is the clearest example. Where the Indian entity decides what gets built rather than building what it is told to build, the routine label becomes difficult to defend, and customer-facing delivery responsibility, independent hiring of senior technical leadership and the freedom to decline unprofitable work all point in the same direction.

Ownership of intangibles is the second driver, and it produces the largest adjustments. Where development, enhancement, maintenance, protection and exploitation of software intangibles happen substantially in India, a cost-plus return on the development team may not compensate the value created.

How does a Transfer Pricing Officer test the declared margin?

By reconstructing the comparable set and recomputing the margin on the department’s own terms.

Rejecting the taxpayer’s comparables is the typical first step. The filters change, the companies with high volumes of related party transactions are eliminated from the sample, and large diversified technology companies enter the sample that has been originally constructed for a captive developer, resulting in the significant changes in the margin before the functions argument even commenced. SBC has published a practical guide to economic adjustments that addresses this matter.

The second move is the cost base, and it is the one software companies are least prepared for.

What belongs in the cost base of an offshore development centre?

Every operating cost incurred in providing the service, and nothing else. The boundary is disputed on four recurring items, each of which moves the declared margin directly.

Where the profit level indicator is operating profit over operating cost, the cost base is the denominator. A cost wrongly included depresses the margin, a cost wrongly excluded inflates it and invites an adjustment, and neither error is visible from the audited financial statements alone.

Cost item Common taxpayer position Where the dispute arises
Pass-through costs recharged without value addition Excluded from the mark-up base Whether the Indian entity performed any function or assumed any risk
Travel, visa and deputation recoveries for onsite work Recovered at cost as reimbursement Whether this is reimbursement or part of the service consideration
Share-based payment charged by the overseas parent Treated as an operating cost of employment Whether a non-cash parent-level charge belongs in a cost-plus base
Foreign exchange gain or loss on trade receivables Treated as operating, and applied to comparables alike Whether it arises from the trading transaction or from treasury activity

Which costs are operating costs and which are not?

Costs incurred in providing the service are operating, and costs unconnected to it, or financing in character, are not.

A cost is a genuine pass-through only where the Indian entity procures it on behalf of the associated enterprise, adds nothing to it and bears no risk in respect of it, which is why third-party licence fees bought at the parent’s direction usually qualify while sub-contracted development work usually does not.

Whatever position is taken must be applied consistently to the tested party and to every comparable. A margin computed on one definition and compared against comparables computed on another is not a comparison at all.

Does the onsite and offshore mix distort the margin?

Yes, and it is the most common structural defect in a software company’s file.

Onsite work carries a higher personnel cost per unit of revenue than offshore work, so a company with a substantial onsite component reports a lower blended margin than an offshore-only comparable would, and benchmarking that blend against offshore-only comparables understates the arm’s length result in a way the department is entitled to challenge.

The correction is segmentation. Onsite and offshore revenue, cost and margin are computed separately, each is benchmarked against a set matched to it, and the segmental statements reconcile to the audited financial statements and to the accountant’s report in Form 48.

How are share-based payments treated?

They are the most frequently disputed single line in the sector, and no rule settles the question.

Where an overseas parent grants equity to employees of the Indian entity and recharges the cost, the taxpayer generally treats that charge as employment cost forming part of the operating cost base, while the department position runs the other way on the argument that a non-cash parent-level benefit should not be marked up by an Indian service provider.

Two practical points follow. The recharge agreement must exist and must predate the grant, and the treatment adopted must match what the comparables do.

Why do information technology services attract the most advance pricing agreement activity?

Because the sector combines a recurring transaction, a contested margin and a long planning horizon, which is exactly the profile an advance agreement was built for. The Central Board of Direct Taxes signed 219 advance pricing agreements in the financial year 2025-26, and the fast-track now announced for information technology services acknowledges where that demand concentrates.

A software group is not arguing about a one-off transaction. It is arguing about the same intercompany service, priced the same way, in every year of a decade, so settling the method once removes the argument prospectively and, through rollback, for earlier years as well. Steadfast Business Consulting (SBC) has published a comparison of the unilateral, bilateral and rollback routes.

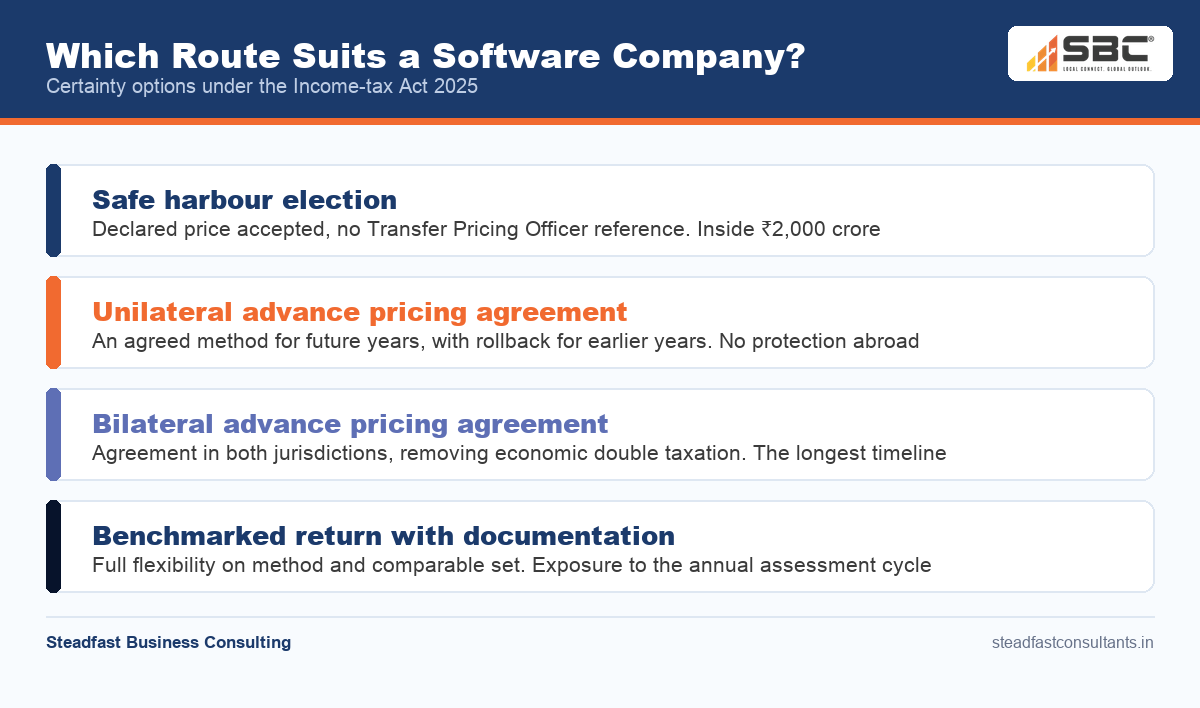
Which route suits a software company: safe harbour, an agreement or a benchmarked return?

The answer turns on size, on how settled the functional profile is, and on how much variance in the outcome the group can tolerate.

Route What it delivers What it costs Where it fits
Safe harbour election Acceptance of the declared price, with no Transfer Pricing Officer reference A prescribed margin that may exceed the benchmarked return, and a binding multi-year election Stable routine developers inside ₹2,000 crore
Unilateral advance pricing agreement An agreed method for future years, with rollback for earlier years Negotiation and annual compliance reporting, with no protection abroad Companies above the threshold, or a profile the prescribed margin does not fit
Bilateral advance pricing agreement Agreement in both jurisdictions, removing economic double taxation The longest timeline, since a foreign competent authority is involved Groups where the counterparty country has adjusted
Benchmarked return with documentation Full flexibility on method and comparable set Exposure to the annual assessment cycle and to appeal Companies whose functional profile is changing year on year
Four-route transfer pricing certainty comparison for Indian software companies

These are not mutually exclusive across time, and a company may reasonably elect safe harbour while its profile is stable and move to an agreement when it is not.

Who provides transfer pricing services in India for a software company?

Firms that combine Indian transfer pricing practice with genuine experience of technology delivery models, since the disputes in this sector turn on facts that a generalist adviser rarely thinks to test. No firm is correct in the abstract, so the useful question is which capabilities the file itself needs.

Four criteria matter for a software company specifically. Can the adviser segment onsite and offshore delivery and defend the segmentals? Has the adviser argued a cost base composition point before a Transfer Pricing Officer? Has the adviser taken an advance pricing agreement through to signature rather than only to application, and does the same team stay with the file from documentation into assessment and appeal?

SBC was named a Notable Transfer Pricing Firm 2024 by ITR World Tax and was founded by Big 4 alumni. It works with global capability centres and multinational subsidiaries from offices in Hyderabad, Mumbai, Pune and Dubai, and the full scope of its transfer pricing services covers documentation, benchmarking, advance pricing agreements and representation.

If your development centre is approaching the safe harbour threshold, or facing its first substantive margin challenge, ask the transfer pricing practice to review the file before the next filing cycle closes.

Software and information technology enabled services groups in that corridor are addressed in transfer pricing services in Hyderabad, Telangana and Andhra Pradesh.

Frequently Asked Questions

Does transfer pricing apply to a software company with only one foreign customer?

Yes, where that customer is an associated enterprise, because the test is the relationship between the parties rather than the number of customers. A development centre billing its own parent must maintain documentation under Section 171 and furnish the accountant’s report in Form 48.

Is the 15.5 per cent safe harbour margin compulsory?

No. Safe harbour is an election the taxpayer exercises, not a prescribed price, and a company may instead benchmark its actual margin under the transactional net margin method or seek an advance pricing agreement. The election binds for a multi-year period once validly made.

Can reimbursements be excluded from the cost base?

Only where the Indian entity adds no value and assumes no risk in respect of the cost, and where the arrangement is documented before the cost is incurred. Sub-contracted development work rarely qualifies, because the Indian entity has selected and supervised the sub-contractor.

How long does a fast-tracked unilateral advance pricing agreement take?

The Union Budget 2026-27 announcement set an endeavour of two years for information technology services, extendable by six months on the request of the taxpayer. That is a stated target rather than a statutory deadline, and it applies to the unilateral route only.

Does an advance pricing agreement remove the documentation obligation?

No. Documentation under Section 171 and Rule 84 continues and the accountant’s report under Section 172 remains due, because an agreement fixes the method and the critical assumptions rather than suspending the compliance calendar. An annual compliance report is also required.

Should onsite and offshore delivery be benchmarked separately?

If the onsite component is significant, then yes. The cost structures are quite distinct for onsite work; thus, a blended margin with respect to offshore-only comparables understates the arm’s length conclusion. The revenue, cost, and margin by segment must agree with the audited financial statements.

CategoriesTransfer Pricing

How Does Transfer Pricing Work for a US Parent With an Indian Subsidiary?

Written by Jayasri P · Last updated 26 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: Transfer pricing puts the filing obligation on the Indian subsidiary, not on the US parent. It must price every transaction with its US parent at arm’s length under Section 165, maintain documentation under Section 171, and furnish the accountant’s report on Form 48. The US parent documents the same transactions separately for its own return.

The India and United States corridor is the largest inbound relationship in Indian transfer pricing practice, and almost every group operating along it under-estimates the same thing, which is that one set of intercompany invoices is examined twice, in two countries, by two administrations applying similar principles from opposite ends of the same transaction and with opposite incentives about where the profit should land.

An Indian subsidiary of a US parent is rarely a standalone business. It is a captive development centre, a shared services unit, a contract manufacturer or a distributor, and in each case the price it charges the parent decides how much of the group’s worldwide profit India may tax. That is why the Indian file attracts scrutiny out of proportion to the size of the entity.

Looking for a transfer pricing consultant for an overseas parent company?

An overseas parent needs an adviser who can defend the Indian position in front of an Indian officer and explain it in terms the parent’s own tax function can use. Those are two different deliverables, and a firm that produces only the first leaves the group to reconcile them.

Ask three things before engaging anyone. Whether the firm appears before the Transfer Pricing Officer itself, whether it has already benchmarked the transaction type in question, and whether it will speak directly to the parent’s US tax team.

Steadfast Business Consulting (SBC) provides transfer pricing documentation, benchmarking and representation to subsidiaries of multinational corporations and Global Capability Centres from its premises in Hyderabad, Mumbai, Pune, and Dubai.

What must the Indian subsidiary file?

The Indian subsidiary is required to maintain contemporaneous transfer pricing documentation and to provide a report from an accountant on Form 48. Both of these obligations belong to the Indian entity and neither is satisfied by any documentation that is submitted in the United States.

Which provisions govern the Indian position?

A transaction between an Indian company and its US parent is an international transaction between associated enterprises, defined at Section 163, and its price must be determined at arm’s length under Section 165 of the Income-tax Act 2025.

The mechanics sit in the Income-tax Rules 2026. Rule 79 describes the prescribed methods and Rule 80 clarifies the criteria for selecting the most appropriate method. In addition, Rule 81 lays out the range and tolerance band applicable when the analysis produces more than one price.

The documentation must be maintained in accordance with Section 171, with the relevant contents being prescribed at Rule 84. The report of the accountant is furnished according to Section 172 in the format as laid down in Rule 85.

Obligation Provision Rule 2026 Instrument
Arm’s length price Section 165 Rules 79, 80, 81 Income-tax Act 2025
Documentation to be maintained Section 171 Rule 84 Income-tax Act 2025
Accountant’s report Section 172 Rule 85 Form 48
Master File Section 171 Rule 123 Income-tax Rules 2026
Country-by-Country report Section 511 Rule 124 Income-tax Rules 2026

What is the accountant’s report, and who signs it?

Form 48 is the report an accountant furnishes under Section 172, and it replaces the erstwhile Form 3CEB that Indian transfer pricing practice cited for two decades.

It is the accountant who signs it, and not the Transfer Pricing Officer, who is the officer that later examines the file. This distinction is meaningful because Form 48 is an affirmative statement on the transactions entered into, and the signatory takes responsibility for those particulars.

The renumbering is not cosmetic. Every section, rule and form number in Indian transfer pricing moved when the Income-tax Act 2025 replaced the 1961 Act, so a memorandum written three years ago cites provisions that no longer resolve.

How do the Indian and US documentation requirements interact?

The two requirements do not interact formally at all, which is precisely what makes this situation risky. In fact, India and the United States both have substantial documentation requirements imposed on their own taxpayers, and neither government accepts the documentation provided by the other country in lieu of complying with its own requirements.

What does the US side require of the parent?

Under section 482 of the Internal Revenue Code, the United States permits the Internal Revenue Service to allocate income and deductions among entities under common control, which is similar to the arm’s length principle in India.

To support the reasonable cause and good faith exception to the transfer pricing penalty under section 6662(e), contemporaneous documentation must exist when the return is filed and must be produced within thirty days of a request from the Internal Revenue Service. Whether any particular group meets a penalty threshold is a question for its US tax advisers. The practical consequence is that two studies describing one arrangement get written in two countries, often by two firms that never speak to each other.

Where do the two files most often diverge?

They diverge on characterisation, which is the description of what the Indian entity actually does and what risks it actually bears.

In Indian files, the subsidiary has often been described as a routine service provider that earns a modest cost-plus mark-up, as such characterisation allows for a defensible Indian margin. In comparison, in US files, this subsidiary for the same year is often portrayed as taking on significant development risk, as such characterisation retains the residual profit in the United States.

Both descriptions cannot be correct. Whichever administration asks first will be answered with a document that undermines the other filing, and the group then spends the assessment explaining an inconsistency instead of defending a price.

A single functional analysis, which has been designed once and employed as the basis for both jurisdictions, removes the problem, since the differences between the two countries refer only to the format, the deadline and the form, but never the business description itself.

Why is the Indian subsidiary usually the tested party?

The Indian subsidiary is usually the tested party because it is the less complex of the two entities, and the transactional net margin method is applied to whichever party performs the more routine functions and owns fewer intangibles.

That follows from how the method works, not from any preference of the Indian administration. Reliable comparable companies can be found for an Indian captive development centre or a shared services unit, whereas no meaningful set of comparables exists for a US parent that owns the group’s technology, funds its research programme, holds the customer relationships, sets the pricing strategy and absorbs the market risk when a product fails.

So the Indian margin becomes the number under examination, and a US parent that thinks of India as a small cost centre frequently discovers that the entire Indian assessment turns on whether a mark-up of a few percentage points was correctly determined on a cost base it has never examined.

When is the Indian entity not the right tested party?

The Indian entity is not the right tested party where it has stopped being routine.

Indian operations mature. A centre that began as a headcount-based delivery unit acquires product ownership and eventually contributes to intangibles the group monetises worldwide, and the transfer pricing file frequently does not follow.

Testing the Indian entity as a routine service provider can be a risky move where the functional profile has evolved, as the Transfer Pricing Officer might argue that the documented characterisation does not align with the business. SBC begins such engagements with the re-testing of the characterisation, and our note on transfer pricing documentation indicates how the functional analysis is refreshed.

What happens during an Indian transfer pricing assessment?

The case is referred by the Assessing Officer to the Transfer Pricing Officer under Section 166 of the Income-tax Act 2025, and the Transfer Pricing Officer then determines the arm’s length price of the international transactions referred.

The process develops on the basis of documents throughout. The relevant information is called for, the taxpayer responds in writing, and a proposed adjustment is put before it is confirmed, as indicated in our guide to the transfer pricing assessment procedure.

An adjustment carries two consequences a US parent should understand in advance. A primary adjustment increases the Indian taxable income, and a secondary adjustment under Section 170 can then treat the excess money retained by the parent as a deemed advance, with repatriation and interest consequences.

Failure to maintain the prescribed documentation attracts a penalty under Section 442, computed at two per cent of the value of each international transaction, and a separate penalty arises under Section 457 where information called for under Section 171 is not furnished. Late furnishing of the accountant’s report now attracts a fee under Section 428, of ₹50,000 for a delay up to one month and ₹1,00,000 thereafter.

What should a US parent with an Indian subsidiary know before an Indian assessment?

Four things, and all four are settled long before a notice arrives.

The first is that the Indian entity answers, not the parent. Proceedings are conducted with the Indian taxpayer, and a group that routes every decision through a US tax director loses time it does not have inside a statutory timeline.

The second is that intercompany agreements are read. An Indian file describing a cost-plus service arrangement while the signed agreement allocates risk differently is a file that argues against itself.

The third point is that the accounting consequence lands in the United States before the Indian tax does. The uncertain Indian position has to be recognised and measured in the US GAAP reporting of the parent company, and that angle is the subject of our note on when an Indian subsidiary needs a FIN 48 opinion.

The fourth is that prevention is available. An advance pricing agreement under Section 168 fixes the methodology prospectively, and a bilateral agreement engages both competent authorities so the two countries do not reach different answers.

How does the India and United States treaty resolve double taxation?

Through the mutual agreement procedure. The comprehensive agreement between India and the United States contains an Associated Enterprises article at Article 9, which is the treaty basis on which either country may adjust the profits of a related enterprise. Article 27 provides for the Mutual Agreement Procedure, under which the two competent authorities seek to resolve taxation that is not in accordance with the treaty.

The relevance is straightforward. Where India adjusts the Indian margin upward and the United States makes no matching reduction, the same profit has been taxed twice, and the procedure exists to unwind that.

It is also slow, and it provides a remedy rather than a plan. The same arithmetic can be applied to the group’s other corridors, as shown in our analysis of the India and UAE corridor for a different jurisdiction pair.

What should a US-parented group do now?

Compare the Indian file and the US file alongside each other, marking every difference in the description of the Indian entity.

Then test that description against the business as it operates today. A characterisation that was accurate when the Indian entity had forty people may be indefensible now that it has four hundred and owns a product.

Where a divergence is found, correct it first. A voluntary correction shows a group that monitors its own positions; an explanation offered under examination shows only a group that responds when asked.

Groups with a US parent and an Indian subsidiary may speak with our cross-border tax specialists about how their two positions align.

Where the parent already retains a global firm, the appointment question is examined separately in whether an Indian subsidiary should use the parent’s global transfer pricing adviser.

Frequently Asked Questions

Does the US parent file anything in India?

No. The Indian subsidiary carries the Indian obligations, maintaining documentation under Section 171 and furnishing the accountant’s report on Form 48 under Section 172. The parent supplies the group information the Indian file depends on, and does not file in its own name.

Does a US transfer pricing study satisfy the Indian requirement?

No. India prescribes its own documentation contents at Rule 84 of the Income-tax Rules 2026 and its own methods at Rules 79 and 80. A US study is useful supporting material, not a substitute for the Indian file.

Has Form 3CEB been replaced?

Yes. The accountant’s report is now Form 48, furnished under Section 172 of the Income-tax Act 2025. Form 3CEB remains the reference point for earlier tax years, so the correct form depends on the year reported.

What penalty applies if documentation is not maintained?

Section 442 of the Income-tax Act 2025 imposes a penalty of two per cent of the value of each international transaction where the required documentation is not kept. Under Section 457, a separate penalty applies in case the information required is not provided.

Can an advance pricing agreement cover the India and US relationship?

Yes. An agreement under Section 168 fixes the methodology prospectively, and a bilateral agreement engages both competent authorities so that India and the United States reach the same answer on the covered transactions.

CategoriesSBC Transfer Pricing

How Do You Defend a Management Fee in an Indian Transfer Pricing Audit?

India Union Budget 2026-27

Home > How Do You Defend a Management Fee in an Indian Transfer Pricing Audit?

How do you actually test what kind of GCC you’re running

Written by Sudheer Polana, Chartered Accountant · August 2026 · Statutory references current to the Income-tax Rules 2026.

A service agreement and an invoice are not evidence that a service was rendered. To survive a challenge, you need to establish three separate things: a real service existed, an independent enterprise would have rationally paid for it or performed it itself, and the amount charged was computed on an arm’s-length basis. A Transfer Pricing Officer cannot price the fee at nil merely because profit didn’t visibly rise  –  but a generic agreement and a year-end invoice bundle won’t survive scrutiny either.

Management fees remain among the most frequently challenged cross-border payments in Indian transfer pricing, and the dispute usually follows the same pattern. The taxpayer produces a service agreement, invoices and a broad description of support received. The Transfer Pricing Officer asks for proof of actual rendition, questions the benefit, flags possible duplication or shareholder activity, and determines the arm’s-length price at nil. Both sides can overreach in this exchange, and the way through it is to keep three separate legal questions from collapsing into one.

What exactly do you need to prove to defend a management fee?

Three distinct things, not one blended argument: that the service existed, that an independent enterprise would rationally have paid for it or performed it itself, and that the amount charged was arm’s length. Evidence is not a procedural afterthought here  –  it defines the transaction that actually gets benchmarked, so a vaguely described service cannot be evaluated for an arm’s-length charge no matter how strong the pricing analysis behind it is.

Can a TPO price a management fee at nil just because there was no visible profit increase?

No. In CIT v. EKL Appliances Ltd., the Delhi High Court held that tax authorities should ordinarily examine the transaction as actually undertaken and should not substitute their own view of how the business ought to have been run. Losses, the absence of immediate profit, or the availability of internal employees cannot, by themselves, establish that the arm’s-length price is nil.

Does that mean an agreement and an invoice are always enough?

No  –  that’s the opposite failure mode. CIT v. Cushman & Wakefield India Pvt. Ltd. draws the line the other way: the TPO determines the arm’s-length price under the prescribed transfer pricing methods, while whether an expenditure is deductible for business purposes is a separate question for the assessing authority. Method selection, proof of receipt and deductibility should not collapse into a single subjective “benefit test”  –  but the taxpayer still carries the practical burden of putting credible material on record.

What does a defensible evidence file actually contain?

Five layers, each establishing something different.

Evidence layer What it should establish
Service architecture
Agreement, service catalogue, responsible teams, request process, deliverables, pricing clause and termination rights
Actual rendition
Dated emails, tickets, reports, presentations, meeting records, system logs, advice notes and identifiable work products
Indian benefit
The local decision, process, risk or capability supported; why the activity was useful when performed, not merely its eventual outcome
Cost integrity
Provider cost centres, employee roles, cost-pool bridge, exclusions, allocation keys, recipient universe and reconciliation to books
Arm’s-length price
Method selection, internal or external comparables, treatment of pass-through costs, mark-up support and tested-party logic

What’s the strongest kind of evidence to rely on?

Whatever was created in the ordinary course of business, not assembled after a notice arrives. A monthly cyber-risk report used by the Indian IT head, a tax position discussed with the local finance team, an ERP ticket resolved for the Indian entity, or a recruitment framework adopted locally is stronger than a generic slide deck put together after the fact. Volume doesn’t substitute for quality either  –  hundreds of emails that merely copy the Indian team prove little. Each service category needs a short evidence narrative: what was requested or provided, by whom, when, what local function it supported, and how the charge reached India. A representative sample can be adequate, but only when it’s linked to a complete service register with an explained selection basis.

Is every head-office cost chargeable to the Indian subsidiary?

No. Costs incurred solely because the parent owns an investment  –  parent-company shareholder meetings, consolidation done only for the parent’s own reporting, investor relations, or acquisition of the parent’s own interest  –  should ordinarily stay with the shareholder rather than being charged down to India.

Does having a local finance, HR or IT team automatically mean group support duplicates it?

No. The enquiry is functional, not structural: does the overseas team perform the same activity for the same purpose, or does it provide specialist capability, global coordination, systems access or surge capacity that the Indian team doesn’t have? The file needs to explain that distinction rather than simply assert that no duplication exists.

Is “belonging to a reputable group” itself a chargeable benefit?

No. Incidental benefit  –  an Indian subsidiary benefiting from group reputation or from a policy designed for the group as a whole  –  is not a chargeable service. A charge becomes defensible when a specific activity is performed for the Indian recipient and its business position is expected to improve, or a relevant risk or cost is addressed.

Where do most management fee cases actually fail?

In the cost pool, even after rendition is established. The provider needs to identify the personnel and third-party costs included, exclude shareholder and duplicate activities, and separate pass-through items. Allocation keys have to reflect the actual benefit driver  –  headcount for HR support, user count for software, transaction volume for processing, revenue for certain commercial support  –  and a single revenue key applied across every service category is easy to administer but hard to defend. The mark-up should also attach only to value-adding costs: third-party licences or agency-type expenses may need cost-to-cost treatment if the service provider performs no meaningful function or takes no risk in relation to them, and a routine 5% mark-up is not automatically arm’s length for every management service.

Is there a safe harbour for low-value management services?

Yes, but it’s tightly conditioned. The Income-tax Rules, 2026 provide a specific safe harbour for an Indian taxpayer receiving low value-adding intra-group services, where the aggregate amount  –  including a mark-up not exceeding 5%  –  does not exceed ₹10 crore. An accountant must certify the cost-pooling method, exclusion of shareholder and duplicate costs, and the reasonableness of the allocation keys used.

The definition is deliberately narrow: the services must be supportive, sit outside the group’s core and economically significant activities, must not use or create unique and valuable intangibles, and must not involve significant risk. R&D, manufacturing, software development, KPO, BPO and other specified activities are excluded  –  calling a charge “management fee” or “low value” does not by itself secure eligibility. The certification requirement effectively converts the cost pool and allocation keys from supporting schedules into the centrepiece of the safe-harbour file.

How do you build a year-round control framework instead of a year-end scramble?

Seven habits, maintained continuously rather than reconstructed at audit time:

  • Maintain a service catalogue with local owners and expected deliverables for each service stream.
  • Create a quarterly evidence pack while records and business context are still fresh.
  • Map provider personnel and cost centres to services; remove shareholder, duplicate and non-beneficial activities before allocation.
  • Use service-specific allocation keys and document why each key approximates expected benefit.
  • Separate pass-through costs and benchmark the mark-up only on the value-adding service element.
  • Reconcile the allocation schedule to the provider’s accounts, the Indian ledger, invoices, withholding tax records and the transfer pricing report.
  • Evaluate the ₹10 crore low-value services safe harbour before filing, but don’t force excluded or high-value services into it.

Who should review your management fee structure?

Someone who can build the evidence narrative before a notice arrives, not after. Management-fee litigation is rarely won by citing a single judgment or presenting a longer agreement  –  it’s won by telling a coherent, evidenced story that connects the service provider’s work to an Indian business need, and connects the charge to a reliable cost and pricing mechanism. Ask the transfer pricing team to pressure-test your current evidence file against these five layers before the next audit cycle.

Frequently Asked Questions

Can a TPO price a management fee at nil just because the Indian entity had local staff doing similar work? Not automatically. The test is functional, not structural  –  whether the overseas activity performs the same function for the same purpose, or supplies specialist capability, global coordination or capacity the local team doesn’t have. The presence of a local team is a starting point for the enquiry, not a conclusion.

Does the low-value services safe harbour cover R&D or software development fees? No. The definition specifically excludes R&D, manufacturing, software development, KPO, BPO and other specified activities, regardless of how the charge is labelled. Only genuinely supportive services outside the group’s core and economically significant activities qualify.

What happens if the cost pool includes shareholder activities? Shareholder costs  –  parent-company shareholder meetings, consolidation for the parent’s own reporting, investor relations and similar items  –  should be excluded from the chargeable cost pool. Including them weakens both the arm’s-length pricing analysis and, where relevant, eligibility for the low-value services safe harbour.

Is a 5% mark-up always considered arm’s length for management services? No. A routine 5% mark-up is not automatically arm’s length for every management service outside the specific low-value services safe harbour. The nature of the activity, available comparables and the method selected still matter.

Can pass-through costs like third-party licences carry a mark-up? Generally not where the service provider performs no meaningful function or assumes no risk in relation to those costs  –  they may require cost-to-cost treatment instead. The mark-up should attach only to the value-adding element of the service.

What’s the difference between proving a service existed and proving its price was arm’s length? They’re separate questions decided on separate evidence. Rendition and benefit are established through service architecture and actual-rendition records; arm’s-length pricing is established separately through method selection, comparables and cost-pool integrity. A strong case on one doesn’t substitute for the other.

Sources and legal references

×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesSBC Transfer Pricing

Should Your Company Elect India’s New 15.5% IT Services Safe Harbour?

India Union Budget 2026-27

Home > Should Your Company Elect India’s New 15.5% IT Services Safe Harbour?

Why does “captive service provider” stop being a safe description for many GCCs

Written by Sudheer Polana, Chartered Accountant · August 2026 · Statutory references current to the Income-tax Rules 2026.

Safe harbour is a price for certainty, not an automatic default. For tax year 2026-27 onward, software development, IT-enabled services, KPO and software-related contract R&D are grouped into a single “information technology services” category, with a prescribed return of 15.5% on operating costs where eligible revenue does not exceed ₹2,000 crore. The election runs five consecutive tax years, is filed on Form No. 49, and once accepted removes MAP protection for that transaction.

Safe harbour is usually described to finance teams as a compliance shortcut, a way to skip the annual benchmarking exercise. That description understates what changed under the Income-tax Rules, 2026. The regime is broader and simpler than before, but it is also a five-year strategic election, and a taxpayer should opt into it only when the value of certainty is worth more than the additional Indian profit, cash tax and lost treaty relief the election may carry.

What does the 2026 IT services safe harbour actually cover?

A single margin, a single revenue ceiling and a five-year lock-in, replacing the old category-by-category structure.

Feature Position for eligible IT services
Covered services
Software development, IT-enabled services, KPO and contract R&D relating wholly or partly to software development
Prescribed return
Operating profit / operating expense of not less than 15.5%
Revenue ceiling
Aggregate operating revenue from the eligible transaction(s) must not exceed ₹2,000 crore
Duration
A valid election continues for five consecutive tax years
Filing
Form No. 49 for the first year, on or before the return-filing due date; prescribed statements follow for the next four years
Treaty consequence
MAP cannot be invoked for the transaction once the safe-harbour transfer price is accepted

Which services fall under “information technology services”?

Four categories, now taxed as one. Software development services, IT-enabled services, knowledge process outsourcing services, and contract research and development services relating to software development are all grouped under the single IT services head. The earlier regime forced many taxpayers to argue over whether their work was routine IT-enabled support, KPO or software R&D; the common margin removes most of that classification friction, though it does not make functional characterisation irrelevant.

Is there a cap on how much revenue can qualify?

Yes. The ₹2,000 crore ceiling is tested against the aggregate operating revenue from the eligible transactions, and that test is applied for the first year of the five-year period. A centre growing quickly should model where it will sit against that ceiling before electing, not only where it sits today.

Can I withdraw from the election once I’ve made it?

Only within a narrow window, and only once. A declaration of withdrawal must be furnished within six months from the end of the first tax year of the cycle. Once withdrawn, the taxpayer cannot re-enter safe harbour for the remainder of that five-year period. This is not an election to make casually at the filing stage.

Does electing safe harbour switch off the rest of the transfer pricing framework?

No. Three obligations survive the election. The maintenance of prescribed information and the accountant’s report continue to apply regardless of safe-harbour status. A comparability adjustment is not available to reduce the safe-harbour price. And transactions with associated enterprises located in notified jurisdictions, or in no-tax or low-tax territories, fall outside the regime entirely.

Is 15.5% also the arm’s-length benchmark if I don’t elect safe harbour?

No, and this is the distinction that gets missed most often. A safe-harbour rate is the return at which the tax administration agrees to accept the declared transfer price, subject to eligibility  –  it is not a legislative finding that every Indian IT or GCC service provider should earn 15.5% on cost under ordinary transfer pricing analysis. A taxpayer that does not elect remains entitled to determine the arm’s-length price through the most appropriate method, and that range may sit below or above 15.5% depending on functions, assets, risks, working-capital profile and service mix. A Transfer Pricing Officer should not treat the safe-harbour margin as an automatic CUP or as a floor outside the statutory election.

Does paying 15.5% cure an inaccurate characterisation?

No. Eligibility as an insignificant-risk service provider still turns on substance, not on the margin paid. The rules test five things: who performs the economically significant functions, who supplies the capital and intangibles, who actually supervises the work, who controls the economically significant risks, and who owns the outcome. Where conduct contradicts the contract, the rules expressly allow conduct to override the contractual language.

When does electing safe harbour make commercial sense?

When the Indian entity is genuinely routine and the numbers already point the same way. The regime is most compelling where:

  • The cost base is stable and can be forecast with reasonable accuracy over five years.
  • The Indian entity does not control product strategy, funding, market risk, IP exploitation or other economically significant risks.
  • The group values closing recurring audits more than the possible tax saving from a lower benchmarked margin.
  • The overseas jurisdiction is comfortable with the charge and MAP protection is unlikely to be needed.
  • The group can maintain transaction-wise segmentation and reconcile operating revenue, operating costs and Form No. 49 to the statutory accounts.

When can the election become expensive?

In three situations, and each compounds over the five-year term.

The margin transfers more profit to India than an ordinary benchmark would. If a TNMM analysis would otherwise support a 10% to 12% mark-up, electing 15.5% moves additional profit to India every year, affecting Indian cash tax, overseas deductibility, withholding positions and Pillar Two calculations. Over five years, the cumulative gap can be substantial.

The business evolves and the election doesn’t. Many Indian centres are moving from execution into product ownership, architecture, AI model development, cybersecurity leadership and global decision-making. A centre that is routine in year one may control significant risk or create valuable intangibles by year three, and safe harbour only gives pricing certainty for as long as the factual eligibility holds.

Mixed activities contaminate the segment. A company providing qualifying IT services alongside sales support, implementation, licensing, onsite services or non-software R&D can compromise eligibility and margin computation if everything is aggregated. The eligible stream needs to be separately identifiable in contracts, invoices, cost-centre records and management accounts.

What should you check before filing Form No. 49?

Six things, in this order:

  • Model the five-year tax cost under safe harbour against the expected arm’s-length range, not just against the current-year margin.
  • Test eligibility service by service, mapping the actual conduct of senior personnel, not only the intercompany agreement.
  • Get written confirmation on deductibility and controversy exposure in the associated enterprise’s jurisdiction.
  • Stress-test changes in headcount, utilisation, subcontracting, foreign exchange, ESOP cost and service mix.
  • Document an exit position before the withdrawal window closes, including the consequence of being unable to re-elect during the remaining cycle.
  • Align invoicing, year-end true-ups, segmental accounts and tax provisioning with the elected 15.5% OP/OC outcome.

Who should review your safe harbour election?

Someone who models the five-year outcome before Form No. 49 is filed, not after. The right question isn’t whether 15.5% looks reasonable in isolation  –  it’s whether 15.5%, applied to the correct cost base for five years, produces a sustainable outcome in India and abroad for the business model that will actually exist, not merely the one described today. Ask the transfer pricing team to model both the safe-harbour and ordinary-benchmarking outcomes before you elect.

Frequently Asked Questions

Does the 15.5% margin apply automatically to all Indian IT companies? No. It applies only to eligible entities that affirmatively elect safe harbour by filing Form No. 49, whose eligible revenue does not exceed ₹2,000 crore, and whose transactions are not with associated enterprises in notified, no-tax or low-tax jurisdictions. Companies that don’t elect continue to determine their arm’s-length price under ordinary transfer pricing rules.

What happens if my IT centre’s revenue crosses ₹2,000 crore mid-cycle? The ceiling is tested for the first year of the five-year period. Revenue growth during the cycle does not by itself remove eligibility, but a centre approaching the threshold should model the position carefully before electing, since eligibility for a fresh election in a later cycle depends on the revenue at that time.

Can I elect safe harbour for only part of my business? Yes, in principle, provided the eligible IT services stream can be segmented and identified separately in contracts, invoices, cost-centre records and management accounts. Aggregating eligible and ineligible activities into one segment is one of the most common ways eligibility gets compromised.

Does safe harbour protect me from double taxation abroad? Not automatically. Once the safe-harbour transfer price is accepted, the Mutual Agreement Procedure cannot be invoked for that transaction, so the overseas jurisdiction’s willingness to allow a corresponding deduction should be confirmed in writing before electing, not assumed.

What if my GCC’s role changes during the five-year period? Safe harbour gives pricing certainty only for as long as the factual eligibility continues to hold. A centre that takes on product ownership, strategic risk or valuable intangibles after electing has not lost the election automatically, but the underlying characterisation risk has changed, and that shift should trigger a fresh review rather than be left until the next filing.

Is Form No. 49 the same as the earlier safe harbour form? No. Form No. 49 is the prescribed form under the Income-tax Rules, 2026, and the election, ceiling and margin structure it supports differ from the pre-2026 safe harbour regime. Filings made under the earlier rules should not be assumed to carry forward automatically.

Sources and legal references

×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesSBC Transfer Pricing

Is Your GCC’s Transfer Pricing Policy Still Defensible?

India Union Budget 2026-27

Home > Is Your GCC’s Transfer Pricing Policy Still Defensible?

Transfer Pricing Policy Still Defensible_

Written by Sudheer Polana, Chartered Accountant · August 2026 · Statutory references current to the Income-tax Rules 2026.

A GCC’s transfer pricing outcome should follow where economically significant decisions are actually made and where risk is actually controlled – not the words “captive,” “limited-risk” or “cost-plus” written into the intercompany agreement. India hosted more than 1,700 GCCs and over 19 lakh GCC professionals as of FY 2023-24, and many have moved from execution work into product ownership, engineering and global leadership without their pricing policy changing to match.

India’s Global Capability Centre landscape has changed faster than many intercompany pricing policies. Centres once set up for transaction processing and application support increasingly run engineering, product development, analytics, cybersecurity, finance transformation and global business operations. The legal agreement may still describe the Indian company as a captive service provider remunerated at cost plus a routine mark-up, while its senior personnel actually select technologies, approve product roadmaps, control delivery and cyber risk, manage global budgets, or direct teams outside India. When conduct moves and the policy doesn’t, controversy follows.

Why does “captive service provider” stop being a safe description for many GCCs?

Because the label describes the contract, not the conduct – and a Transfer Pricing Officer tests conduct. As GCCs take on product ownership, analytics, engineering leadership and cross-border decision authority, the gap between what the intercompany agreement says and what senior Indian personnel actually do becomes the single largest source of transfer pricing exposure in this sector.

How do you actually test what kind of GCC you’re running?

By mapping the operating model against five profiles, not by relying on the label in the service agreement.

GCC profile Transfer pricing question
Execution centre
Does the foreign principal define scope, control risk and own all economically significant assets while India performs assigned work?
Specialised service hub
Do advanced analytics, engineering or finance capabilities remain support services, or do they influence strategic outcomes and control risk?
Contract R&D centre
Who conceptualises, funds, supervises and can stop or redirect the research? Who owns and exploits the outcome?
Product / innovation hub
Does India perform DEMPE-related functions, control key development risks or create platform value requiring more than a routine return?
Regional or global leadership hub
Are India-based leaders making decisions for overseas entities, and are services, stewardship and potential management or PE issues properly separated?

What does a rigorous risk analysis actually map?

The people who make decisions, not the entity that signs the contract. For each economically significant risk -product failure, technology, delivery, market, capacity, people, cyber, regulatory and IP risk -the group needs to identify who has the capability and authority to decide whether to take the risk, how to respond to it, and whether that person actually performs the control function in practice.

Does the 2026 safe-harbour rules’ insignificant – risk test change this?

It reinforces it. The rules look at whether the foreign principal performs the critical functions and provides strategic direction, supplies capital and economically significant assets including intangibles, actually supervises the activity, controls economically significant risks, and owns the resulting intangible or research outcome. The rules state plainly that contractual allocation is not final where conduct shows the Indian entity actually controls the risk.

Does the unified 15.5% safe harbour solve the characterisation question?

No. The 2026 rules combine software development, IT-enabled services, KPO and software-related contract R&D into a single information technology services category with a common safe-harbour return of 15.5% on operating costs, subject to a ₹2,000 crore revenue ceiling. That removes much of the old margin differential between technology-service labels -but it does not mean every GCC activity is eligible, and it doesn’t mean 15.5% is the correct return outside safe harbour either. A centre controlling valuable product or technology risk may not be an insignificant-risk provider at all, and the safe-harbour percentage should not be used as a substitute benchmark under ordinary TNMM. The first question is always the accurate delineation of the transaction; method and margin follow from that, not the other way round.

What are the five pressure points that most often break a GCC’s pricing policy?

1. Senior talent and decision-making

A vice-president based in India may carry a global title while remaining an employee of the Indian company. If that individual approves roadmaps, allocates capital, controls risk or leads overseas personnel, the analysis has to determine in which capacity those decisions are made and which entity actually receives the service. Global reporting lines alone don’t settle the question.

2. Intangibles and reusable know-how

Routine development can still produce code, processes and know-how worth real value. The key question is whether India merely executes a controlled specification, or makes significant decisions relating to development, enhancement, maintenance, protection and exploitation. Patent registration and contractual ownership are relevant, but the location of DEMPE functions and risk control can still shift the allocation of returns.

3. The cost base

Cost-plus outcomes are only as reliable as the cost base underneath them. GCCs commonly dispute employee stock compensation, subcontractors, cloud and software licences, pass-through expenditure, recruitment cost, idle capacity, foreign exchange items, travel and central allocations. Each item needs a principled operating/non-operating and value-adding/pass-through analysis – selectively excluding cost merely because it depresses the margin is difficult to defend.

4. Segmentation and mixed activities

A single GCC can house routine application support, high-end analytics, contract R&D and strategic leadership all at once. Entity-level TNMM can obscure materially different functions and risk profiles. Segmental accounts should follow operational cost centres and service streams, supported by allocation keys that reconcile to the general ledger -segmentation built for the first time during an audit rarely carries the same credibility as segmentation maintained throughout the year.

5. Business transformation

When work, decision rights, personnel or IP migrate to India, the group needs to consider whether there has been a transfer of functions, assets, risks or valuable rights. A higher prospective mark-up doesn’t necessarily price a one-time restructuring, but not every increase in capability creates an intangible either. The answer depends on what changed, who controlled it, and what independent parties would have agreed.

How do you build a GCC pricing policy that survives the next phase of growth?

Seven practices, kept current rather than revisited only at filing time:

  • Prepare a decision-rights matrix for key risks and update it whenever senior roles or mandates change.
  • Interview business and product leaders directly; don’t let the transfer pricing narrative be written only from contracts and organisation charts.
  • Separate routine services, specialised services, R&D, leadership support and any IP-related activity in the accounting system.
  • Define the cost base in the agreement and policy, including ESOPs, pass-through costs, idle capacity, subcontracting and year-end true-ups.
  • Test internal comparables before defaulting to external database searches, and use adjustments only where they’re reliable and evidence-based.
  • Create a transformation trigger: acquisitions, new global roles, product ownership, patents, budget authority or major risk-control changes should prompt an immediate TP review.
  • Evaluate safe harbour, APA and ordinary benchmarking as alternative certainty routes, and choose only after modelling both Indian and overseas consequences.

Who should review your GCC’s transfer pricing position?

Someone who talks to your business leaders, not just your contracts. The most defensible GCC policy isn’t the one with the longest benchmarking report -it’s the one that can point to the people, decisions, budgets, systems and records that prove the characterisation throughout the year. In the GCC environment, operational governance is transfer pricing evidence. Ask the transfer pricing team to run a decision-rights review before your next transformation trigger, not after.

Frequently Asked Questions

Does a global job title for an India-based leader change the transfer pricing analysis? Not by itself. What matters is which entity the decisions are actually made for and in what capacity -a global title on an employee of the Indian company doesn’t automatically shift value or risk to India, but it does require the analysis to establish which entity the work is really being performed for.

Can routine development work still create a valuable intangible? 

Yes. The dividing line isn’t sophistication of the work but control: whether India merely executes a controlled specification or makes significant decisions relating to development, enhancement, maintenance, protection and exploitation. Reusable code and know-how can carry value even from a nominally “routine” team.

Does the 15.5% IT services safe harbour apply to a GCC doing product development? 

Only if the centre is genuinely eligible for safe harbour in the first place -the margin doesn’t establish eligibility on its own. A centre controlling significant product or technology risk may not qualify as an insignificant-risk service provider at all, regardless of what margin it earns.

What triggers a fresh transfer pricing review for a GCC? 

Any material change in decision rights or risk control: acquisitions, new global roles, product ownership, patents, expanded budget authority or major changes to who controls key risks. Waiting for the next annual filing to notice these changes is usually too late.

Should GCC segments be priced separately or as one entity-level TNMM? 

Separately, where the centre houses materially different functions -routine support, specialised services, R&D and leadership work shouldn’t be blended into a single entity-level margin, since that blending can obscure the actual risk and function profile of each stream.

Can moving decision rights to India without changing the pricing policy create risk? Yes, and it’s one of the most common exposure points in the sector. When work, personnel, IP or decision authority migrate to India but the intercompany pricing policy stays the same, the gap between conduct and contract is exactly what a Transfer Pricing Officer is trained to test.

Sources and legal references

×

Verify Email

Verify your email address below to download the PDF

Please wait while we verify your email.

CONTACT US

Name
=

RELATED POSTS

CategoriesTransfer Pricing

Which Groups Must File a Master File in India?

Written by Jayasri P · Last updated 20 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: A Master File is required where the international group’s consolidated revenue exceeds ₹500 crore. The Indian entity’s international transactions must also exceed ₹50 crore, or ₹10 crore where intangible property is involved. It is furnished under section 171(4) of the Income-tax Act 2025 read with Rule 123 of the Income-tax Rules 2026.

Most finance teams meet this obligation late. Neither Indian turnover nor the size of the Indian balance sheet is the trigger. A subsidiary with modest local revenue can carry a filing duty arising out of income earned by entities it has never dealt with.

What is the Master File, and where does it sit under BEPS Action 13?

The group-level tier of the three-part documentation framework that BEPS Action 13 introduced. Action 13 of the OECD Base Erosion and Profit Shifting project replaced a patchwork of national documentation habits with a standardised set of three documents. A Master File describes the group as a whole, a Local File documents the Indian entity’s dealings, and a Country-by-Country report allocates revenue and tax across jurisdictions.

India legislated all three tiers. The Master File now sits in section 171(4) of the Income-tax Act 2025 read with Rule 123 of the Income-tax Rules 2026, which replaced section 92D(4) and Rule 10DA. Both expressions, constituent entity and international group, carry the meanings given in section 511 of the Income-tax Act 2025. That section also governs Country-by-Country reporting, and SBC’s transfer pricing services in India cover both filings.

Which constituent entities must file?

Every resident constituent entity files something, and what differs between them is how much of the Master File each one has to complete. An entity below the thresholds files only the identifying particulars, whereas an entity above them files the entire group narrative.

What does Part A require from every constituent entity?

Identifying particulars, irrespective of value. Rule 123(3) requires a constituent entity to furnish Part A of the prescribed Master File form even where the value conditions in Rule 123(1) are not satisfied, which catches a large population of Indian subsidiaries.

Part A asks for the name, permanent account number and address of the constituent entity, and the accounting year adopted. It is a short filing, and it is also the one most often missed. A team that has correctly concluded it falls below the value thresholds frequently concludes that nothing at all is due.

Which entities must complete the full Master File?

Those that clear both tests together: the consolidated revenue test must be met first, and then either of the two transaction tests will do. The Central Board of Direct Taxes guidance on the Master File sets the consolidated group revenue test at more than ₹500 crore for the accounting year, read alongside a second test measured at the level of the Indian entity.

Test Threshold Measured at
Consolidated group revenue, per the consolidated accounts exceeds ₹500 crore the international group
International transactions, per the books of account exceeds ₹50 crore the Indian entity
International transactions involving intangible property exceeds ₹10 crore the Indian entity
Three-test Master File filing threshold gate for international groups chart

There is a revenue test, and one of the two transaction tests must also be satisfied, so a group with ₹4,000 crore of revenue whose Indian subsidiary pays ₹12 crore in royalties meets the intangibles limb even though its international transactions fall well below ₹50 crore, and that combination is the single most common misunderstanding among finance teams.

What information must the Master File contain?

Five heads, all of them group-level, none of them answered entity by entity the way a Local File would be, because the filing describes how an international group creates and locates value, and an entity-level analysis of the Indian company’s margins does not answer that question.

Information head What has to be furnished
Group structure Legal and ownership structure, with the location of every constituent entity
Business description Profit drivers, service arrangements, principal markets, restructurings in the year
Intangibles Intangibles strategy, material intangibles and their legal owners, research and development arrangements
Intra-group financing How the group is financed, the central financing entities, the policy on loans
Financial and tax positions Consolidated financial statements, unilateral advance pricing agreements, and rulings on income allocation

What must the group structure section show?

Ownership and geography, in a form that reconciles to the accounts. A chart illustrating the legal ownership of the international group and the geographical location of its operating entities is expected, and where the group has restructured during the year the position both before and after the restructuring has to be visible.

How much detail is required on intangibles?

More than most groups expect, because the filing reaches well beyond the summary a parent ordinarily prepares for its own board. Expect the filing to ask for the group’s overall strategy for the development, ownership and exploitation of intangibles, together with a list of the material intangibles, their legal owners, and the important agreements relating to intangible property.

This is the head that most often exposes a gap, because legal ownership of a trademark or a patent frequently sits in one jurisdiction while the development functions that created it sit in another, and a filing that records the first without ever explaining the second invites precisely the enquiry that a group would most prefer to avoid.

What has to be disclosed about intra-group financing?

Financing architecture, rather than the terms of any single loan. What the filing asks is how the international group is financed, including arrangements with unrelated lenders, and it requires the entities performing a central financing function to be named.

Groups that operate a treasury company find this head straightforward, and groups that do not usually find it revealing, since the general policy on intra-group financing has to be stated in terms consistent with the inter-company agreements already executed, and a contradiction between the two is not a small problem.

Which financial and tax positions must be reported?

The consolidated accounts and the rulings the group holds. Consolidated financial statements for the year are required, with a description of existing unilateral advance pricing agreements. Those rulings record positions already taken on the allocation of income, and the narrative is expected to match them.

When is the Master File due?

On the due date for furnishing the return of income. The departmental guidance on the forms notified under the Income-tax Rules 2026 places the Master File filing on the same date as the return of income specified under section 263(1)(c) for the relevant tax year.

That distinction matters, because the accountant’s report falls due at least one month before the return of income, whereas the Master File itself is submitted with the return, as Steadfast Business Consulting (SBC) sets out in a separate note on the move from Form 3CEB to Form 48.

Filing Timing
Intimation designating one constituent entity at least thirty days before the Master File due date
Part A, where the entity is below the thresholds due date for the return under section 263(1)(c)
Part A and Part B, where the entity is above them due date for the return under section 263(1)(c)

How does a group designate one entity to file?

By intimation, filed first, so that the department knows which entity carries the obligation before the Master File itself arrives. Where an international group has more than one constituent entity resident in India, Rule 123(4) permits the group to designate a single entity to furnish the filing for all of them, and that designation is communicated through a separate intimation.

That intimation has to be furnished at least thirty days before the Master File due date, which means the decision cannot wait until the return is finalised. Groups with several Indian entities routinely lose that window.

Why does a copy-paste Master File fail scrutiny?

Because it is read against everything else the group has already said. The Master File is not assessed in isolation, and a narrative lifted unchanged from a foreign parent’s pack will describe functions and risks in terms drafted for another jurisdiction.

What does an assessing officer compare it against?

Every other document describing the same arrangement. The accountant’s report, the Local File documentation maintained under section 171 read with Rule 84, the inter-company agreements and the Country-by-Country report each describe the same arrangements from a different angle. An officer reading them together will notice where the group’s account of itself changes between documents.

By itself, each of the repeated failures is unremarkable, but their combination creates damage. An entity described as a limited-risk distributor in the Local File, while the Master File credits that same entity with market development, is the recurring example. So is a material intangible attributed to one owner in the group narrative and to another in the contract.

What does a default cost?

Enough to make the filing worth doing properly. Failure to keep and maintain the prescribed information and documents attracts a penalty of two per cent of the value of the transaction under section 442 of the Income-tax Act 2025, and failure to furnish information or documents called for under section 171 attracts a further penalty under section 457.

A filing inconsistent with the underlying record leaves the same exposure open, and the position on each default is set out in transfer pricing penalties.

Best transfer pricing firms for Master File and CbCR compliance

One that can draft the group narrative and defend it afterwards. Global network firms, established domestic practices and specialist boutiques divide the market, and firms such as Deloitte, EY, Grant Thornton, BDO, Nangia and Dhruva work in this space.

No firm is best in the abstract, and the useful questions are a good deal narrower than the marketing: whether the team has drafted a Master File from a foreign parent’s source material rather than merely translated one, whether it has defended that narrative before a Transfer Pricing Officer, and whether it reads the group’s agreements before it writes. A short guide to choosing a transfer pricing consultant in India sets out what to ask.

SBC was recognised as a Notable Transfer Pricing Firm 2024 by ITR World Tax, and its team works from Hyderabad, Mumbai, Pune and Dubai.

What should a group do before the filing window opens?

Reconcile before drafting, comparing what the group has already filed elsewhere against what the Master File will say. Most of the Master File is a synthesis of material the group holds elsewhere, and the work that decides whether it survives scrutiny happens before it is drafted.

  • Confirm consolidated group revenue against the consolidated accounts, not management accounts
  • Total the Indian entity’s international transactions and, separately, its intangible-related transactions
  • Identify every constituent entity resident in India, including entities acquired during the year
  • Decide which entity is designated, and diarise the intimation thirty days before the return due date

If the group narrative in your file was last written by a parent-company team for a different regulator, it is worth a review this year. Ask the SBC transfer pricing team for a Master File readiness review.

Frequently Asked Questions

Is the Master File the same as the Local File?

No. The Master File describes the international group as a whole, including its structure, intangibles and financing. Local File documentation covers the Indian entity’s own international transactions and the benchmarking supporting them, under section 171 read with Rule 84.

Does a group below ₹500 crore in revenue file anything?

Yes. Rule 123(3) requires every resident constituent entity in India to file Part A, whether or not the value thresholds in Rule 123(1) are met. Only the full group narrative in Part B depends on those value thresholds.

Which rule replaced Rule 10DA?

Rule 123 of the Income-tax Rules 2026 replaced Rule 10DA of the Income-tax Rules 1962, and the enabling provision moved from section 92D(4) of the Income-tax Act 1961 to section 171(4) of the Income-tax Act 2025. In substance the obligation carried forward into the new framework without change.

Can two Indian entities of the same group file separately?

Yes, and by default they must. A single filing on behalf of both is permitted only where the group designates one constituent entity under Rule 123(4) and furnishes the prescribed intimation at least thirty days before the due date.

Is the Master File filed in English?

Yes. Filing is electronic, on the income tax portal in the prescribed form, and material drawn from foreign group documentation should be presented in English.

Does filing a Master File reduce transfer pricing scrutiny?

Not by itself. A complete and internally consistent filing removes an easy line of enquiry, but the Transfer Pricing Officer may still examine the arm’s length price of individual transactions under section 165.

CategoriesTransfer Pricing

When Should You Run a Transfer Pricing Health Check?

Written by Jayasri P · Last updated 20 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: Run a transfer pricing health check when something has changed in the group. Triggers include a new intra-group arrangement, a restructuring, a swing in margins, a first crossing of a reporting threshold, a change of adviser, or an assessment on the horizon. It is diagnostic: it tests an existing position before a Transfer Pricing Officer does.

Most transfer pricing problems announce themselves a year before anybody reacts. Margins moved, the intra-group service charge was never papered, the benchmarking set was carried forward without being refreshed, and none of it looked urgent at the time, because nothing in the compliance calendar forces a company to revisit a position it has already taken. Cheapest of all hours in transfer pricing is the one spent before a notice arrives.

What is a transfer pricing health check?

A diagnostic assessment of a company’s current transfer pricing position, run outside the annual compliance cycle. Nothing is filed and no form is produced; what comes out of it is a gap report, a written analysis of where the position holds, where it is thin, and what would repair the difference.

Steadfast Business Consulting (SBC) lists a transfer pricing health check-up among its advisory offerings alongside transfer pricing due diligence. Related, but distinct: due diligence examines a target or a counterparty in a transaction, whereas a health check turns the same lens on the company commissioning it. Both are risk assessments rather than compliance deliverables, and neither produces a filing.

When should you run a transfer pricing health check?

When the facts supporting your last recorded position have changed, or when someone outside the company is about to examine that position. Six events account for most of the reviews that prove worth commissioning.

Trigger What it puts at risk When to review
New intra-group arrangement Pricing set without a benchmark; no agreement in place Before the tax year closes
Group restructuring Functional profile no longer matches the documentation Within the year of the change
Material change in margins Result falls outside the arm’s length range At the half year, not at year end
First crossing of a threshold Reporting obligation missed entirely The year the threshold is crossed
Change of adviser Positions inherited without their reasoning Before the first filing under the new adviser
Approaching assessment Multiple years opened together As early as the notice window allows

Why does a new intra-group arrangement need reviewing before the year closes?

Because pricing is far easier to justify than to correct. Management charges, royalties, intra-group loans and guarantees introduced halfway through the year get priced by reference to whatever the group already does elsewhere. Commercial answers are not arm’s length answers, and the difference only becomes expensive once the year has closed and the price sits on the record.

Evaluate the arrangement while the year is still open and there is room to set the rate on a benchmark, to execute the inter-company agreement that supports it, and to build the cost pool the charge is drawn from; once the year closes, that same process turns into an explanation.

Why does a change of adviser justify a review?

Because positions are inherited without the reasoning that produced them. Benchmarking studies transfer as files, but their rationale, meaning why those comparables, why that method and why those economic adjustments, usually does not travel with them, and a new adviser who rolls a study forward without testing it repeats a conclusion rather than reaching one.

How early before an assessment should a review happen?

As early as the notice window allows, since the position under examination is rarely a single year. Rule 82 of the Income-tax Rules 2026 is new, and it permits the arm’s length price to be determined across multiple tax years in one proceeding, so a weakness in one year’s analysis can now travel across every year grouped with it. Once the reference to the Transfer Pricing Officer has been made, a review becomes a defence exercise rather than a diagnostic one.

What does a transfer pricing review examine?

The transaction record, the pricing, the documentation and the consistency between them. Repeating the benchmarking study is not what a transfer pricing risk assessment means. It tests whether the position as filed would survive a reading by someone looking for a reason to adjust it.

Reviews of this kind typically cover:

  • Completeness of the related-party transaction record, including arrangements never invoiced and services charged at cost with no mark-up
  • Whether the method selected to determine the arm’s length price remains the most appropriate one for the transaction as it is now structured
  • Whether the comparable set has been refreshed, and whether the tested party’s result still falls within the range
  • Whether the functional profile in the documentation still describes the assets employed, functions performed and risks borne by the Indian entity
  • Whether inter-company agreements exist, are executed, and match what actually happens
  • Whether segmental financial information is capable of being drawn where the entity runs more than one line of business
  • Consistency with positions taken in earlier years and with any adjustment already accepted

What does the review test on the numbers?

Whether the reported result is inside the range and, if it is not, whether the reason is documented. Perfectly defensible reasons move margins, among them capacity underutilisation, a forex swing, an extended start-up phase or a working capital difference against the comparable set, and each can be quantified as an economic adjustment. What cannot be defended is a result falling outside the range with no explanation attached to it.

What does a gap report contain?

A finding, a consequence and a remedy for each issue, ranked by exposure. Enumerating findings and stopping there defeats the purpose, because the value of the exercise lies in knowing which findings would actually cost something and which are merely housekeeping.

Element What it answers
Finding What the review found, and in which year
Statutory exposure Which provision the gap sits under, and the quantum
Adjustment risk The likely size of an adjustment if the position is challenged
Remedy What repairs it, and whether it can still be done for that year
Priority What must be fixed before the next filing, and what can wait

Whether commissioning the report was worth the expenditure is usually settled by the remedy column, because some gaps close cheaply: executing an agreement that was always intended, refreshing a comparable set, or drawing a segmental profit and loss statement the accounting system can already support. Others cannot be closed retrospectively at all, and knowing which is which before the year closes is the entire point of running the review early.

How is a health check different from preparing documentation?

Documentation records a position. A health check tests one. Prescribed work with a deadline, governed by section 171 read with Rule 84 of the Income-tax Rules 2026, the documentation exercise produces the record the taxpayer must maintain. No deadline, no prescribed contents and no filing attach to a health check.

One practical distinction matters most, and finance teams tend to discover it too late: a documentation engagement takes its scope from the need to produce a compliant file, so it looks at the facts and the price handed to it, whereas a health check takes its scope from the questions asked. Hence a study can produce a compliant file and still describe an arrangement that no longer exists.

Health check Documentation
Purpose Diagnose exposure Record and support the position
Trigger An event or a change The tax year
Timing Any time, ideally mid-year Before the reporting deadline
Output Gap report with remedies The prescribed record under Rule 84
Consequence of skipping Undetected exposure A penalty under statute

What does leaving a position unexamined cost?

More than the review would have, in the majority of cases where an adjustment follows. Failure to keep and maintain the prescribed documentation attracts a penalty of two per cent of the value of each transaction under section 442 of the Income-tax Act 2025, and because that penalty is calculated on transaction value rather than on the adjustment, it does not scale down when the underlying position turns out to be broadly correct.

What happens if the accountant’s report is late?

Failure to furnish the accountant’s report is now treated differently. Section 447 was omitted by the Finance Act 2026 with effect from 1 April 2026, and the consequence moved into section 428(4)(d) as a fee of ₹50,000 for a delay of up to one month and ₹1,00,000 thereafter, and because that fee attaches on the facts, no reasonable-cause argument is available against it.

Is the adjustment larger than the penalty?

Commonly, the more substantial number is the adjustment rather than the penalty. Where a reference is made to the Transfer Pricing Officer under section 166, the officer determines the arm’s length price for the transactions referred; an adjustment then carries interest and may pull a secondary adjustment under section 170 behind it, and the full position on each default is set out in transfer pricing penalties.

Frequently Asked Questions

Is a transfer pricing health check required by law?

No. Nothing in law requires one, and nothing is submitted at the end of it. Health checks are voluntary risk assessments; binding obligations run elsewhere, namely documentation under section 171 read with Rule 84, and the accountant’s report under section 172.

How often should a transfer pricing review be run?

Annually for any group engaged in cross-border transactions of any size, and immediately on any of the six trigger events. Where functional profile and arrangements have been stable, a full review every second year is reasonable, provided the comparable set is still refreshed each year.

What is the difference between a health check and transfer pricing due diligence?

A health check examines your own position. Due diligence examines someone else’s, typically the target or the counterparty in a transaction, to establish what exposure would travel with the deal; analysis is similar in both, but subject and purpose are not.

Can a health check fix a position for a year that has already closed?

Partly. Some remedies survive the year end: refreshing the analysis, executing agreements, or making a voluntary transfer pricing adjustment. Others, among them changing how a charge was raised or priced, cannot be applied retrospectively, since they would create a fresh inconsistency in the record.

Does a health check trigger scrutiny by the department?

No. Internal throughout, the gap report goes to nobody outside, and commissioning one creates no reporting obligation. What changes is what the company knows about its own exposure before the department forms its own view of the same transactions.

When in the year is the best time to run one?

At the half year, while the result can still be influenced. Run then, the review leaves room to correct pricing, raise or reverse a charge, and refresh the benchmarking before the year closes. Run after the year end, it can only describe what has already happened.

CategoriesTransfer Pricing

What Interest Rate Is Defensible on an Intra-Group Loan?

Written by Jayasri P · Last updated 20 August 2026 · Statutory references current to the Income-tax Act 2025 and the Income-tax Rules 2026.

Quick Answer: A defensible rate is the one an unrelated lender would have charged this borrower, in this currency, for this tenor and this security. Price it from the borrower’s own credit standing adjusted for implicit group support, using a base rate plus a spread, and support it under section 165 of the Income-tax Act 2025.

Interest is the easiest intra-group charge to set and one of the hardest to justify, because a rate reads as an objective figure in a way that a royalty or a service mark-up never does: a rate is a rate, and it sits in the contract. That perception is the problem. Almost every criterion making a rate arm’s length turns on the borrower rather than the lender, and the OECD guidance on financial transactions, developed under BEPS Actions 4 and 8-10, is built around that distinction.

What makes an intra-group loan interest rate defensible?

Whatever an unrelated lender would have imposed on this borrower, in this currency, on these conditions. Section 165 of the Income-tax Act 2025, which replaced section 92C of the 1961 Act, requires the arm’s length price to be determined by the most appropriate method. A loan between associated enterprises is an international transaction like any other. Four questions decide the answer, and they must be taken in order because each constrains the next: is the advance debt at all, what credit standing does the borrower carry once implicit group support is counted, what currency and tenor apply, and what security sits behind it?

Pricing factor What it determines Where files go wrong
Delineation as debt Whether interest is deductible at all Treating an open-ended advance as a loan
Borrower credit standing The spread over the base rate Applying the group rating without analysis
Currency of the loan The base rate itself Benchmarking a rupee facility off the lender’s home rates
Tenor The point on the yield curve Pricing five-year money off short-term data
Security and ranking The spread, again Ignoring that the advance is unsecured

Is the advance actually a loan?

Not always, and the point is settled well before any rate is discussed. Accurate delineation comes first under the OECD guidance, which means establishing the economic substance of the arrangement rather than reading its description. An advance with no repayment date, no enforceable obligation to pay interest and no prospect of being serviced is not debt merely because the group calls it debt.

Which features point to debt rather than equity?

Precisely the features an independent lender would insist on. A definite maturity date, a duty to pay interest, and an enforceable right to repayment. Ranking alongside the other creditors, financial covenants, and above all a borrower carrying the cash flows to service the debt on schedule. Absent those attributes, the department may treat the funding as equity in substance, and the consequence is not an adjustment to the rate but disallowance of the entire interest charge, which is far worse than a spread proving a few basis points too generous.

Whose credit rating should the interest rate reflect?

The borrower’s, adjusted for the support it implicitly enjoys as a group member. Neither the parent’s rating nor the subsidiary’s standalone rating can be used on its own. Analysis begins with an appraisal of the borrower as it stands, then asks what an independent lender would assume about the group’s willingness to step in behind it.

How does implicit group support change the rating?

In most cases it lifts the rating, sometimes by several notches. Implicit support means a parent is expected to stand behind a strategically important subsidiary in distress even without any contractual obligation, and the OECD guidance treats it as a comparability factor reflected in the borrower’s rating rather than as a service on which anything may be charged. Files fall short on that last point. Free though implicit support is, an explicit guarantee is a separate transaction carrying its own fee, and that fee is priced in a separate note on the arm’s length corporate guarantee fee.

Why is the lender’s home interest rate the wrong benchmark?

Because an interest rate is a property of the currency rather than of the lender’s profile. A loan denominated in Indian rupees is priced off rupee market rates whoever advances it, and a group lending from a low-rate jurisdiction cannot import those rates on the argument that this is what the money cost it to raise; running the mistake in reverse is no less frequent and considerably more expensive. Where an Indian entity lends to an overseas associated enterprise in a foreign currency, the rate must answer to that currency’s market, and benchmarking such lending against domestic rupee rates has been rejected in assessment after assessment. Cost of funds is one input into a spread, never the price.

How do tenor, security and seniority move the rate?

Materially, and in directions that are straightforward to verify. A five-year facility does not price like a working capital line, unsecured debt does not price like secured debt, and subordinated debt does not price like senior debt, so a comparable that matches the borrower on credit standing but not on these terms is barely a comparable at all.

  • Tenor fixes the point on the yield curve, so the comparison has to sit at the same maturity
  • Security narrows the spread, so an unsecured advance benchmarked against secured data understates the rate
  • Ranking behind the other creditors widens that spread again
  • Covenants and prepayment rights carry a price of their own

How does the base rate plus spread approach work?

A reference rate for the currency and the tenor, plus a spread reflecting the borrower’s creditworthiness and the loan terms; that is the whole method. Because reference rates are observable and rarely disputed, almost all of the argument in an assessment proceeds on the spread, and the spread must be evidenced from comparable debt market data: bond yields and syndicated loan pricing for issuers of the same credit standing, in the same currency, at the same tenor. Steadfast Business Consulting (SBC) draws that evidence from the databases its transfer pricing practice holds access to, including Loan Connector, Prowess, CapitalineTP, Amadeus and Orbis.

Which method is most appropriate for a loan?

The comparable uncontrolled price method, in the large majority of cases. Rule 79 of the Income-tax Rules 2026, which replaced Rule 10B of the 1962 Rules, prescribes the methods available, while Rule 80 requires the most appropriate of them to be selected on the facts of the case. Where the borrower holds genuine third-party debt on record, internal comparables come first. Selection across the various transaction types is addressed in which transfer pricing method applies.

Do the safe harbour rules offer a simpler route?

For some borrowers, yes. Within section 167 of the Income-tax Act 2025 sits the safe harbour framework, which took over from section 92CB of the 1961 Act, and the Central Board of Direct Taxes confirms that advancing intra-group loans is among the eligible international transactions specified under Rule 88 of the Income-tax Rules 2026. Certainty comes at a cost to the rate itself, because the margins prescribed are deliberately kept conservative, so a taxpayer opting in accepts a position it could probably have improved on through proper benchmarking. Exercise of the option requires a prescribed application form for the relevant year, and it is never applied automatically.

What are the withholding and deductibility implications?

Two further rules take effect once the rate has been set, and the benchmarking analysis cures neither. Interest paid to a non-resident lender attracts tax deduction at source at the rate under the Act or under the applicable tax treaty, whichever is more favourable to the recipient, and treaty relief normally depends on the lender holding a valid tax residency certificate when the payment is made. Deductibility is restricted separately: section 177 of the Income-tax Act 2025, which replaced section 94B of the 1961 Act, restricts the interest deduction available on debt issued by a non-resident associated enterprise. It also treats third-party debt as issued by an associated enterprise where that enterprise has given the lender an implicit or explicit guarantee. A rate can be entirely arm’s length and still partly non-deductible.

Does a transfer pricing adjustment change the tax already deducted?

It does not undo what was deducted when the payment was made. Where the arm’s length interest exceeds the interest actually charged, the adjustment raises the Indian entity’s income with no corresponding movement of cash, and should the excess go unrepatriated within the prescribed period, the secondary adjustment provisions in section 170 read with Rule 83 deem it an advance on which further interest accrues. Groups routinely fail to budget for that second layer, whose mechanics are set out in the implications of a secondary adjustment.

What belongs in the file before the return is filed?

The agreement, the credit assessment and the benchmarking study, dated before the loan was drawn rather than after the notice arrived. Documentation under section 171 read with Rule 84 is contemporaneous by design. Reconstruct a rate two years later and it carries very little weight with a Transfer Pricing Officer who can see when the file was assembled.

  • A signed agreement stating principal, currency, tenor, rate, security and repayment schedule
  • The borrower’s credit assessment, with workings and the reasoning behind any notching applied
  • The reference rate selected, together with its source and observation date
  • The comparable debt search, showing the screens applied and the candidates rejected

Looking for a transfer pricing consultant for an overseas parent company

Look for benchmarking capability in debt markets and representation experience before the Transfer Pricing Officer. Financing positions are built on the comparable search and defended face to face, so two questions separate advisers quickly: which loan and bond databases the firm holds, and how many financing adjustments it has argued through to a conclusion.

What makes an overseas parent’s exposure different?

An overseas parent lending into an Indian subsidiary faces a second problem beyond the rate: the Indian entity carries the compliance obligation, the assessment exposure and the penalty risk, while the funding decision was taken elsewhere and often without any transfer pricing input, so work is needed at both ends.

Which firms operate in this market?

The provider landscape runs from global network firms through established domestic practices to specialist boutiques, where firms such as Deloitte, EY, BDO, Grant Thornton, Nangia and Dhruva operate. No firm is best in the abstract.

What does SBC bring to a financing position?

SBC was recognised as a Notable Transfer Pricing Firm 2024 by ITR World Tax, and its transfer pricing team is built from Big 4 alumni. Offices in Hyderabad, Mumbai, Pune and Dubai carry the practice, with access through PrimeGlobal to member firms in over one hundred countries. SBC provides transfer pricing services in India covering intra-group financing: interest rate benchmarking, withholding implications and the underlying agreements.

Where a loan from the parent sits on the books and the rate has never been benchmarked, that review is overdue. Do it before the next accountant’s report is presented. Have the financing position reviewed before an assessment raises it.

Frequently Asked Questions

Can an intra-group loan be interest free?

Not for transfer pricing purposes. Where the arrangement is delineated as debt, an arm’s length rate is imputed whether or not interest was actually charged. Tax then falls on the Indian lender for income it never received.

Should a rupee loan be benchmarked against the parent’s home currency rates?

No. Currency being lent, rather than the residence of the lender, drives the base rate. A rupee denominated advance is priced off rupee market rates even where the lender raised its own money in a low-rate currency.

Does the borrower’s credit rating have to come from a rating agency?

No. A published rating helps where one exists, but most borrowers in this position have none. Credit standing is instead derived from a documented financial analysis of the borrower, adjusted for implicit group support.

Is an intra-group loan reportable where no interest was paid?

Yes. Reporting duty follows the transaction, not the income derived from it. International transactions carry no monetary threshold at all, unlike specified domestic transactions, which apply only above ₹20 crore in aggregate.

What happens if the interest rate is adjusted upward on assessment?

The Indian entity’s income rises by the shortfall. Should the excess money go unremitted within the prescribed period, the secondary adjustment provisions regard it as an advance and impute further interest on it.

Do the safe harbour rules cover intra-group lending?

Yes. Advancing intra-group loans is confirmed by the department as among the eligible international transactions specified under Rule 88 of the Income-tax Rules 2026. That safe harbour framework itself sits in section 167 of the Income-tax Act 2025.